Food Starch Market Summary
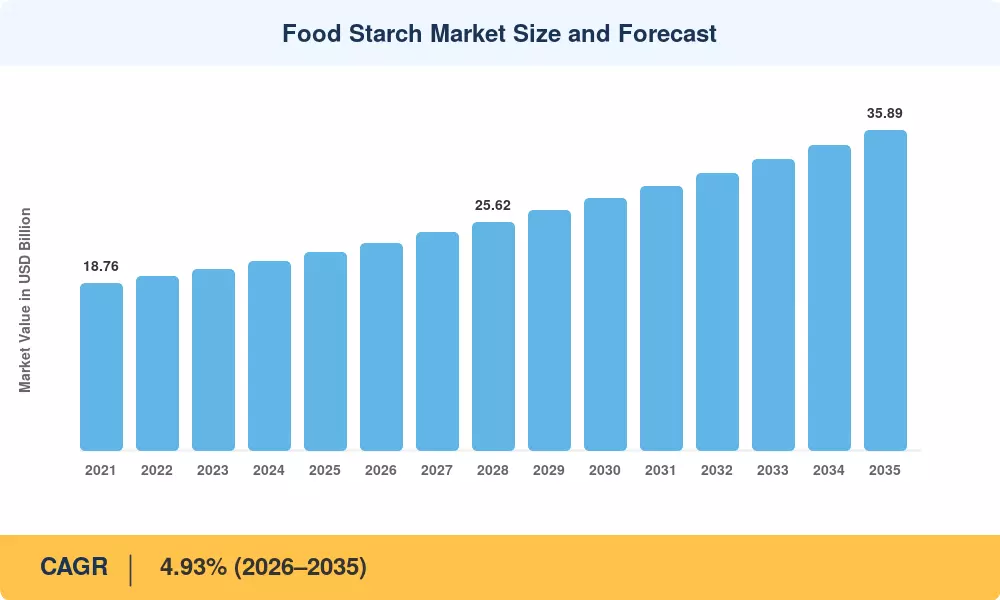
The global food starch market reached a valuation of USD 22.18 Billion in 2025 and is projected to climb from USD 23.27 Billion in 2026 to USD 35.89 Billion by 2035, expanding at a CAGR of 4.93% during the forecast period. This growth trajectory is anchored in two structural forces: the persistent reformulation of processed food products to meet evolving texture and stability requirements, and the accelerating shift toward plant-based food systems that rely heavily on starch as a functional ingredient. Government programs such as the USDA's BioPreferred initiative and the European Commission's Farm to Fork Strategy have catalyzed investment in sustainable starch processing infrastructure, with an estimated USD 2.3 Billion committed to next-generation bio-refinery capacity between 2023 and 2025 [1].
A quiet transformation is reshaping the food starch market from the inside out. Legacy chemical modification techniques — once the industry's default approach — are giving way to enzymatic and physical modification platforms that deliver comparable functional performance while satisfying clean-label demands. Ingredion alone invested over USD 400 Million between 2022 and 2024 in proprietary enzyme-conversion facilities across three continents [2]. These newer processing methods reduce chemical inputs by as much as 60%, aligning with EU Regulation 231/2012 amendments and FDA's GRAS pathway updates that increasingly favor process-clean ingredients.
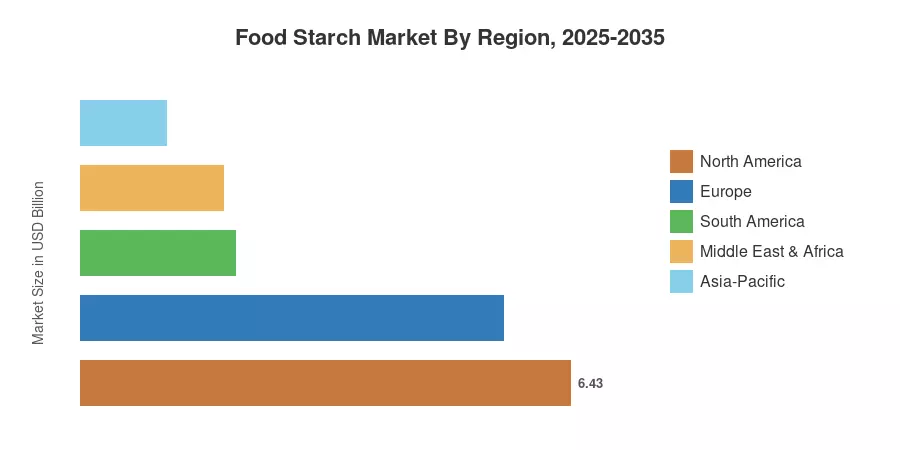
Regionally, North America commands roughly 29% of the food starch market, driven by the continent's massive processed food manufacturing base and sophisticated supply chains. Asia-Pacific is the fastest-growing region, expanding at a 5.10% CAGR through 2035, propelled by rapid urbanization in India, China, and ASEAN nations where packaged food adoption is accelerating sharply. Europe holds the second-largest share at approximately 25%, supported by strong demand from bakery, dairy, and convenience food sectors. The decade ahead will be defined by how effectively producers bridge the gap between functional performance and ingredient transparency.
Key Report Takeaways
• By Product Type
- Modified starch accounted for approximately 69% of the food starch market in 2025, reflecting the ingredient's indispensable role in freeze-thaw stability and high-shear processing environments.
- Native starch is gaining renewed attention from clean-label formulators, posting a CAGR of 4.21% through 2035 as consumer preference shifts toward minimally processed ingredients.
• By Source
- Maize-derived starch commanded a 67% share of the food starch market in 2025, leveraging established agricultural supply chains in the US and China.
- Potato starch is projected to expand at a 4.82% CAGR, driven by its superior gel clarity and allergen-free profile in European food applications.
• By Application
- Bakery and confectionery dominated the food starch market with a 35% share in 2025, reflecting starch's critical function as a texturizer and moisture manager in baked goods.
- Pharmaceutical applications are set to grow at a 5.45% CAGR as starch-based excipients gain traction in tablet binding and capsule manufacturing.
• By Region
- North America led the food starch market with approximately 29% share in 2025.
- Asia-Pacific will record the highest growth at a 5.10% CAGR through 2035, fueled by packaged food demand in China and India.
Market Size and Forecast (2021–2035)
Market sizing for the food starch market draws on a triangulated methodology incorporating proprietary primary surveys across 120+ starch manufacturers and food processors, secondary intelligence from FAO trade databases, USDA crop reports, and customs data from 32 countries, supplemented by financial disclosures of publicly listed industry participants [3]. Historical figures (2021–2024) reflect actual reported data adjusted for currency effects; forecast projections (2026–2035) apply a calibrated compound growth model validated against macro indicators, including global food production indices and urbanization rate trajectories.



 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA


