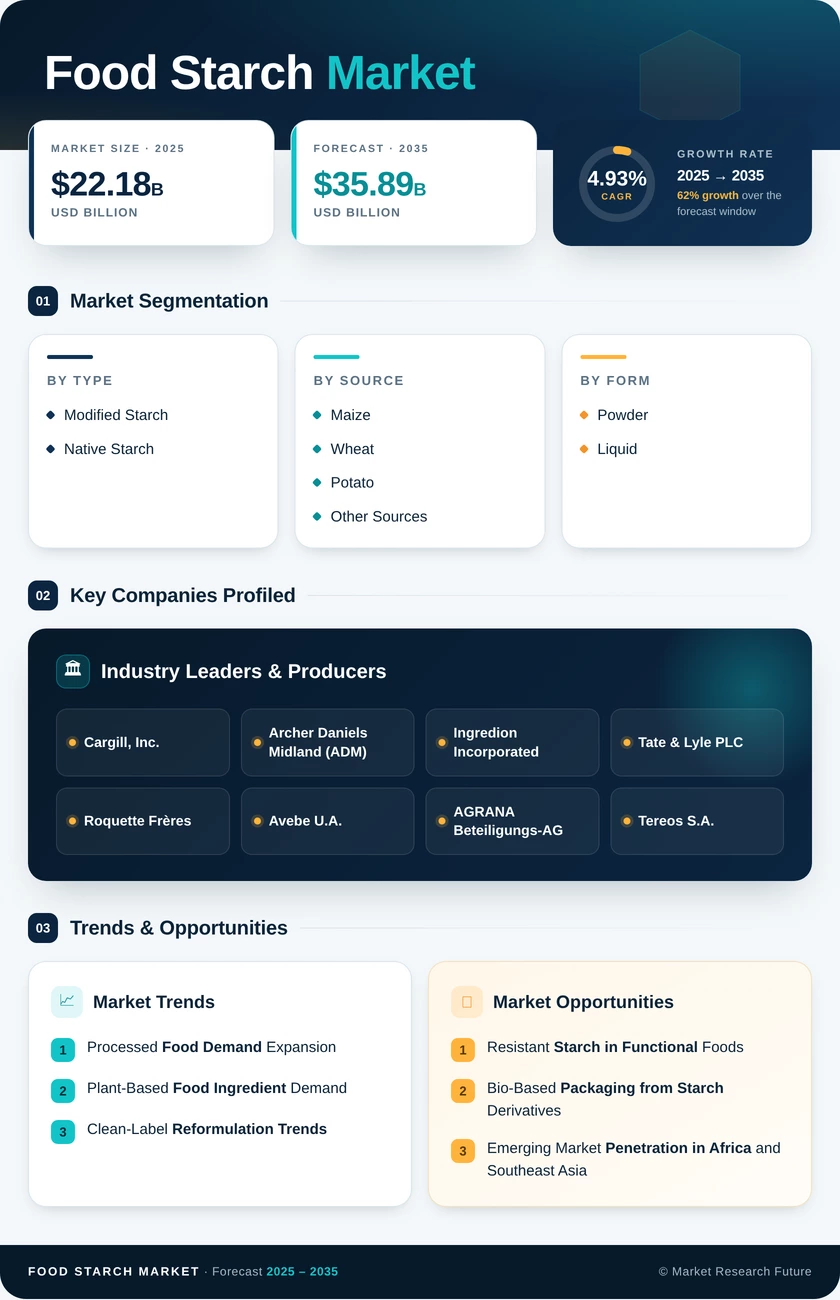
Food Starch Market (2026 - 2035)

ID: MRFR/FnB/39488-HCR 128 Pages Varsha More Last Updated: September 17, 2026
Food Starch Market Size, Share, Industry Trend & Analysis Research Report By Product Type (Modified Starch, Native Starch), By Source (Maize, Wheat, Potato, Other Sources), By Form (Powder, Liquid), By Application (Bakery & Confectionery, Snacks, Soups/Sauces/Dressings, Dairy Products, Meat & Meat Products, Pharmaceuticals, Others), By Geography (North America, Europe, Asia-Pacific, South America, Middle East & Africa) - Forecast to 2035
Food Starch Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)4.93%
2025 Market SizeUSD 22.18 Billion
2035 Market SizeUSD 35.89 Billion
Key Players
Cargill, Inc.
Archer Daniels Midland
Ingredion Incorporated
Tate & Lyle PLC
Roquette Frères
Avebe U.A.
Opportunities
  • Resistant Starch in Functional Foods
  • Bio-Based Packaging from Starch Derivatives
  • Emerging Market Penetration in Africa and Southeast Asia
  1. 1 Market Overview |
    1. 1.1 Study Assumptions & Market Definition |
    2. 1.2 Scope of the Study |
    3. 1.3 Research Methodology
  2. 2 Market Summary & Key Takeaways
  3. 3 Market Dynamics |
    1. 3.1 Market Drivers Analysis | |
      1. 3.1.1 Processed Food Demand Expansion | |
      2. 3.1.2 Plant-Based Food Ingredient Demand | |
      3. 3.1.3 Clean-Label Reformulation Trends | |
      4. 3.1.4 Bakery Sector Volume Growth | |
      5. 3.1.5 Pharmaceutical Excipient Expansion | |
      6. 3.1.6 Urbanization and Packaged Food Adoption | |
      7. 3.1.7 E-Commerce Food Retail Acceleration |
    2. 3.2 Market Restraints Analysis | |
      1. 3.2.1 Raw Material Price Volatility | |
      2. 3.2.2 Competition from Alternative Hydrocolloids | |
      3. 3.2.3 Water and Energy Intensity in Processing | |
      4. 3.2.4 Regulatory Complexity for Modified Starches | |
      5. 3.2.5 Supply Chain Disruptions in Grain Markets |
    3. 3.3 Market Opportunity Analysis | |
      1. 3.3.1 Resistant Starch in Functional Foods | |
      2. 3.3.2 Bio-Based Packaging from Starch Derivatives | |
      3. 3.3.3 Emerging Market Penetration in Africa and Southeast Asia | |
      4. 3.3.4 Digital Supply Chain and Demand Forecasting | |
      5. 3.3.5 Organic and Non-GMO Starch Premiums |
    4. 3.4 Industry Value Chain Analysis |
    5. 3.5 Porter's Five Forces Analysis
  4. 4 Global Food Starch Market Size & Forecast (2021–2035) |
    1. 4.1 Historical Market Size (2021–2025) |
    2. 4.2 Current & Forecast Market Size (2026–2035) |
    3. 4.3 Market Size by Revenue (USD Billion) |
    4. 4.4 Year-over-Year Growth Analysis
  5. 5 Segmentation Analysis |
    1. 5.1 By Product Type | |
      1. 5.1.1 Modified Starch | |
      2. 5.1.2 Native Starch |
    2. 5.2 By Source | |
      1. 5.2.1 Maize | |
      2. 5.2.2 Wheat | |
      3. 5.2.3 Potato | |
      4. 5.2.4 Other Sources (Tapioca, Rice, Cassava) |
    3. 5.3 By Form | |
      1. 5.3.1 Powder | |
      2. 5.3.2 Liquid |
    4. 5.4 By Application | |
      1. 5.4.1 Bakery & Confectionery | |
      2. 5.4.2 Snacks | |
      3. 5.4.3 Soups, Sauces & Dressings | |
      4. 5.4.4 Dairy Products | |
      5. 5.4.5 Meat & Meat Products | |
      6. 5.4.6 Pharmaceuticals | |
      7. 5.4.7 Others
  6. 6 Regional Analysis |
    1. 6.1 North America | |
      1. 6.1.1 United States | |
      2. 6.1.2 Canada | |
      3. 6.1.3 Mexico |
    2. 6.2 Europe | |
      1. 6.2.1 Germany | |
      2. 6.2.2 United Kingdom | |
      3. 6.2.3 France | |
      4. 6.2.4 Italy | |
      5. 6.2.5 Spain | |
      6. 6.2.6 Nordic Countries | |
      7. 6.2.7 Russia | |
      8. 6.2.8 Rest of Europe |
    3. 6.3 Asia-Pacific | |
      1. 6.3.1 China | |
      2. 6.3.2 India | |
      3. 6.3.3 Japan | |
      4. 6.3.4 South Korea | |
      5. 6.3.5 ASEAN | |
      6. 6.3.6 Rest of Asia-Pacific |
    4. 6.4 South America | |
      1. 6.4.1 Brazil | |
      2. 6.4.2 Argentina | |
      3. 6.4.3 Rest of South America |
    5. 6.5 Middle East & Africa | |
      1. 6.5.1 Saudi Arabia | |
      2. 6.5.2 UAE | |
      3. 6.5.3 South Africa | |
      4. 6.5.4 Egypt | |
      5. 6.5.5 Rest of MEA
  7. 7 Competitive Landscape |
    1. 7.1 Market Share Analysis (2025) |
    2. 7.2 Competitive Benchmarking Matrix |
    3. 7.3 Company Profiles | |
      1. 7.3.1 Cargill, Inc. | |
      2. 7.3.2 Archer Daniels Midland (ADM) | |
      3. 7.3.3 Ingredion Incorporated | |
      4. 7.3.4 Tate & Lyle PLC | |
      5. 7.3.5 Roquette Frères | |
      6. 7.3.6 Avebe U.A. | |
      7. 7.3.7 AGRANA Beteiligungs-AG | |
      8. 7.3.8 Tereos S.A. | |
      9. 7.3.9 SMS Corporation | |
      10. 7.3.10 Grain Processing Corporation
  8. 8 Future Outlook & Strategic Recommendations (2026–2035) |
    1. 8.1 AI-Driven Formulation and Process Optimization |
    2. 8.2 Sustainability and Circular Processing |
    3. 8.3 Precision Fermentation and Hybrid Starch Systems |
    4. 8.4 Regulatory Convergence and Global Trade Facilitation
  9. 9 Recent Developments & News
  10. 10 Frequently Asked Questions (FAQs)
  11. 11 Report Scope & Methodology |
    1. 11.1 Study Period & Base Year |
    2. 11.2 Data Sources & Citations |
    3. 11.3 Abbreviations
  12. 12 LIST OF TABLES |
  13. TABLE 1 Global Food Starch Market Size & Forecast, by Revenue (USD Billion), 2021–2035 |
  14. TABLE 2 Global Food Starch Market – Year-over-Year Growth Analysis, 2021–2035 |
  15. TABLE 3 Global Food Starch Market – Driver Impact Analysis |
  16. TABLE 4 Global Food Starch Market – Restraint Impact Analysis |
  17. TABLE 5 Global Food Starch Market Size, by Product Type, 2021–2035 (USD Billion) |
  18. TABLE 6 Global Food Starch Market Size, by Source, 2021–2035 (USD Billion) |
  19. TABLE 7 Global Food Starch Market Size, by Form, 2021–2035 (USD Billion) |
  20. TABLE 8 Global Food Starch Market Size, by Application, 2021–2035 (USD Billion) |
  21. TABLE 9 Global Food Starch Market Size, by Region, 2021–2035 (USD Billion) |
  22. TABLE 10 North America Food Starch Market Size, by Country, 2021–2035 (USD Billion) |
  23. TABLE 11 Europe Food Starch Market Size, by Country, 2021–2035 (USD Billion) |
  24. TABLE 12 Asia-Pacific Food Starch Market Size, by Country, 2021–2035 (USD Billion) |
  25. TABLE 13 South America Food Starch Market Size, by Country, 2021–2035 (USD Billion) |
  26. TABLE 14 Middle East & Africa Food Starch Market Size, by Country, 2021–2035 (USD Billion) |
  27. TABLE 15 Competitive Benchmarking Matrix – Global Food Starch Market, 2025 |
  28. TABLE 16 Company Profiles – Key Players, Global Food Starch Market |
  29. TABLE 17 Recent Developments & Strategic Announcements, 2023–2024 |
  30. TABLE 18 Report Scope & Methodology Summary |
  31. TABLE 19 Detailed Sources and Citations
  32. 13 LIST OF FIGURES |
  33. FIGURE 1 Global Food Starch Market Dynamics (Drivers, Restraints, Opportunities) |
  34. FIGURE 2 Industry Value Chain Analysis – Food Starch Market |
  35. FIGURE 3 Porter's Five Forces Analysis – Food Starch Market |
  36. FIGURE 4 Global Food Starch Market Size Trend & Forecast (USD Billion), 2021–2035 |
  37. FIGURE 5 Food Starch Market Share, by Product Type (2025) |
  38. FIGURE 6 Food Starch Market Share, by Source (2025) |
  39. FIGURE 7 Food Starch Market Share, by Form (2025) |
  40. FIGURE 8 Food Starch Market Share, by Application (2025) |
  41. FIGURE 9 Food Starch Market Share, by Region (2025) |
  42. FIGURE 10 North America Food Starch Market Share, by Country (2025) |
  43. FIGURE 11 Europe Food Starch Market Share, by Country (2025) |
  44. FIGURE 12 Asia-Pacific Food Starch Market Share, by Country (2025) |
  45. FIGURE 13 South America Food Starch Market Share, by Country (2025) |
  46. FIGURE 14 Middle East & Africa Food Starch Market Share, by Country (2025) |
  47. FIGURE 15 Competitive Landscape – Market Share Analysis (2025)

Segmentation Quick Reference

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
Product TypeModified Starch, Native StarchModified StarchNative Starch
SourceMaize, Wheat, Potato, Other SourcesMaizePotato
FormPowder, LiquidPowderLiquid
ApplicationBakery & Confectionery, Snacks, Soups/Sauces/Dressings, Dairy Products, Meat & Meat Products, Pharmaceuticals, OthersBakery & ConfectioneryPharmaceuticals
GeographyNorth America, Europe, Asia-Pacific, South America, Middle East & AfricaNorth AmericaAsia-Pacific


Market Segmentation Overview

By Product Type

Sub-SegmentKey Trend
Modified StarchDominant segment; essential for freeze-thaw stability and high-shear processing in industrial food manufacturing
Native StarchGrowing clean-label demand driving reformulation from chemically modified to unmodified starch variants


Modified starch remains the backbone of industrial food processing, while native starch is experiencing renewed investment as consumer preference for minimally processed ingredients continues to strengthen across Western markets.

By Source

Sub-SegmentKey Trend
MaizeLargest source globally; cost-efficient wet-milling infrastructure in the US, China, and Brazil
WheatStrong demand in European bakery and patisserie applications
PotatoFastest growing source; superior gel clarity and allergen-free credentials
Other SourcesTapioca and rice starches gaining traction in Asian and specialty Western applications


Maize dominates global starch sourcing due to production scale, but potato and tapioca starches are carving premium niches based on functional differentiation and regional agricultural strengths.

By Form

Sub-SegmentKey Trend
PowderIndustry standard; favored for shelf stability, ease of transport, and flexible dosing
LiquidGrowing adoption among large-scale processors seeking reduced preparation time and dust-free operations


Powder form continues to lead, though liquid starch formats are gaining favor as food manufacturers prioritize operational efficiency and workplace safety in high-throughput production environments.

By Application

Sub-SegmentKey Trend
Bakery & ConfectioneryLargest application; starch serves as texturizer, moisture regulator, and coating agent
SnacksStarch coatings enhance crispness and adhesion in extruded and fried snack products
Soups, Sauces & DressingsModified starches provide viscosity stability across temperature and pH ranges
Dairy ProductsFat replacement and stabilization in yogurt, ice cream, and cheese analogues
Meat & Meat ProductsWater binding and yield improvement in processed meats
PharmaceuticalsFastest growing application; excipient demand for tablet binding and controlled release
OthersPet food, paper coating, and industrial adhesive applications


Bakery and confectionery commands the largest share of starch consumption, while pharmaceutical applications represent the most dynamic growth opportunity driven by expanding drug delivery technologies.

By Geography

Sub-SegmentKey Trend
North AmericaLargest market; mature corn starch supply chain and strong processed food sector
EuropeRegulatory-driven clean-label demand; strong potato and wheat starch production
Asia-PacificFastest growing; urbanization and packaged food adoption across China, India, and ASEAN
South AmericaCassava and corn starch production growth; export-oriented capacity expansion
Middle East & AfricaImport-dependent but developing domestic cassava and corn starch processing


Regional dynamics are shaped by agricultural resource availability, food processing maturity, and regulatory frameworks governing ingredient labeling and food safety.


 

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.