Military Power Solutions Market Summary
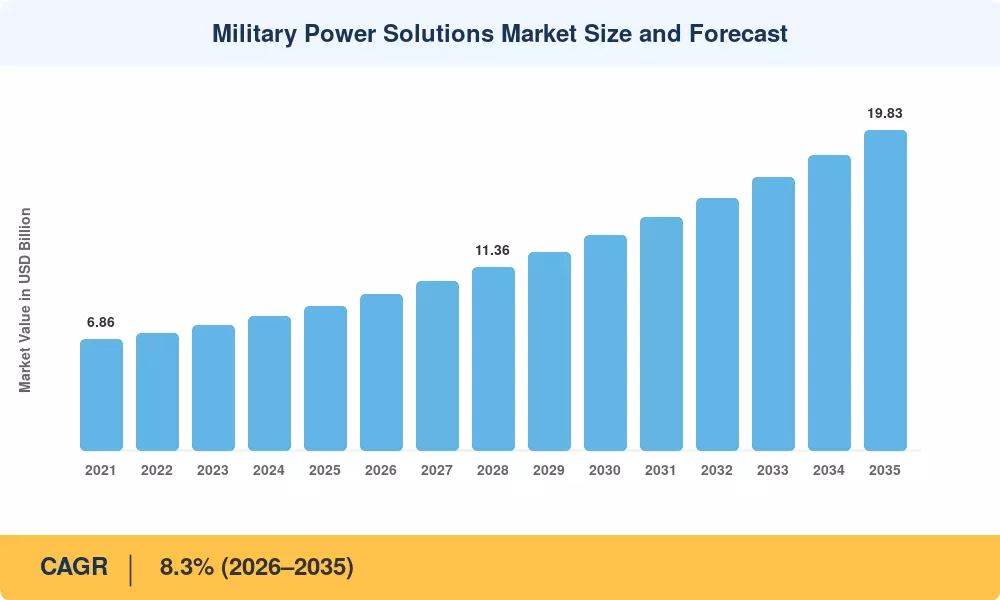
The Military Power Solutions Market reached USD 8.95 billion in 2025 and enters the forecast window at USD 9.69 billion in 2026, climbing to USD 19.83 billion by 2035 at a compound annual growth rate of 8.3%. Two catalysts anchor that trajectory. NATO's 2024 Washington Summit commitment to lift member defence spending toward 2% of GDP unlocked roughly USD 96 billion in incremental European procurement authority [1], while the U.S. Department of Defence allocated USD 143.2 billion to research, development, test and evaluation in FY2025 — a pool from which mobile electrification programs draw heavily [2]. Growth in the Military Power Solutions Market is therefore budget-backed rather than speculative.
Legacy diesel gensets and lead-acid vehicle batteries are being displaced faster than most procurement offices anticipated. Lithium-iron-phosphate and lithium-sulphur packs, silent-watch auxiliary units, and hybrid drive architectures now dominate new-start requirements. The U.S. Army's Climate Strategy targets fully electric tactical vehicle fleets by 2050 and hybrid-drive tactical vehicles by 2035, with USD 1.2 billion committed across installation microgrid pilots through 2030 [3].
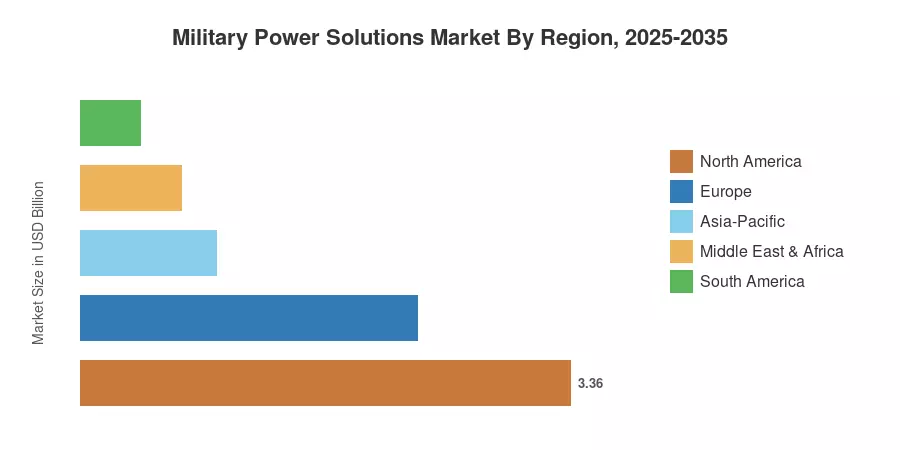
Regionally, North America holds 37.5% of global value on the strength of sustained Army and Navy modernization lines. Asia-Pacific expands quickest at a 10.4% CAGR, driven by Indian and South Korean indigenization mandates. Europe follows as the second-largest bloc at 25.8%, propelled by the European Defence Fund's energy-resilience calls. Expect the competitive centre of gravity to shift toward integrators who can certify cells, not merely assemble them.
Key Report Takeaways
• By Type
- Non-Portable systems command the largest slice of the Military Power Solutions Market, holding a 61.5% revenue share in 2025 on the back of shelter, radar and vehicle auxiliary demand
- Portable units post the faster trajectory at a 9.6% CAGR through 2035 as dismounted soldier loads shift to rechargeable conformal packs
• By Sector
- Batteries generated USD 4.13 billion in 2025, the single largest source category across the Military Power Solutions Market
- Generators retain a 38.4% share, sustained by forward operating base and expeditionary shelter requirements
- Land platforms account for USD 4.01 billion, reflecting armoured vehicle silent-watch retrofits
• By Region
- North America contributes 37.5% of 2025 global value
- Asia-Pacific grows at 10.4% CAGR, the fastest of any region
- Middle East & Africa reached USD 0.69 billion in 2025
Market Size and Forecast (2021–2035)
Historical values were reconstructed from defence appropriation line items, prime contractor segment disclosures, and customs-level trade data for battery and generator HS codes, then triangulated against programme-of-record award volumes. Forecast years apply a demand-weighted build from platform production schedules rather than a flat top-down extrapolation, which is why the Military Power Solutions Market shows uneven acceleration around programme milestone years.