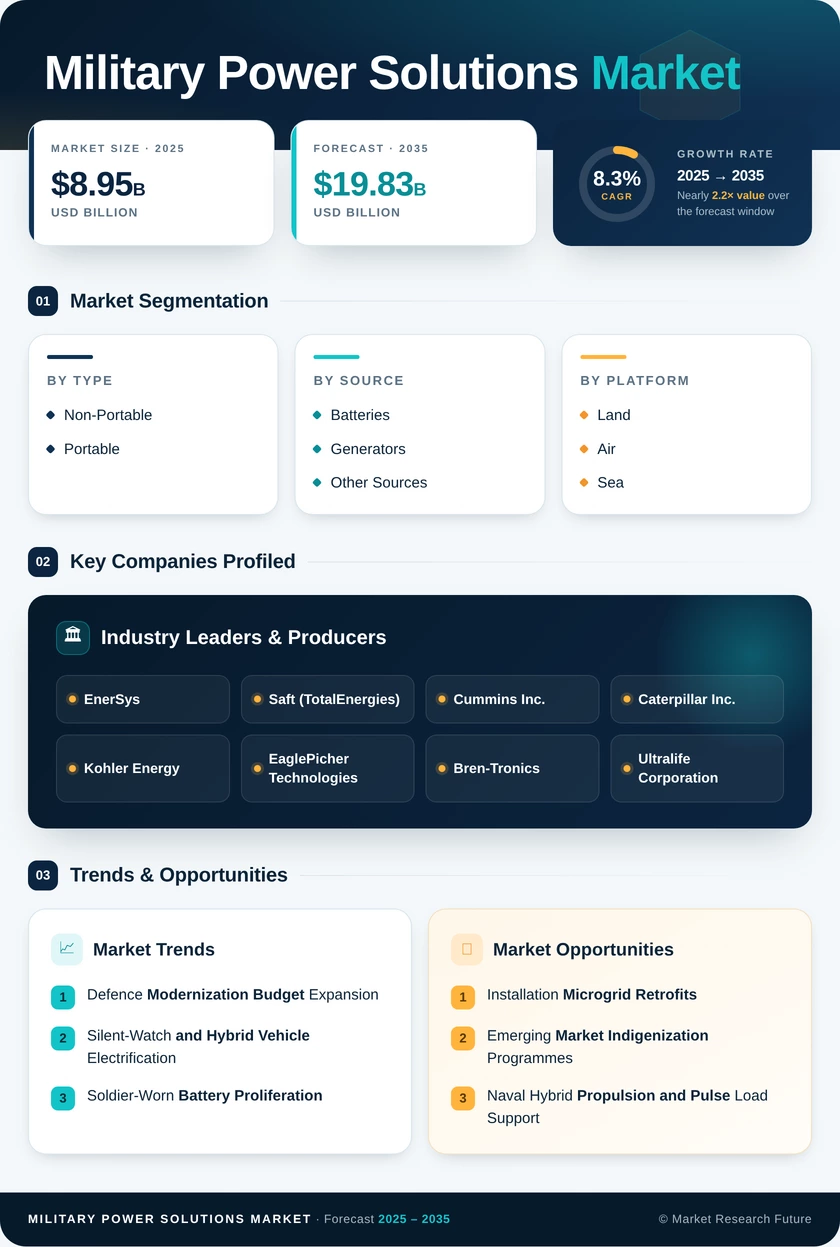
Military Power Solutions Market (2026 - 2035)

ID: MRFR/AD/8832-CR 168 Pages Abbas Raut Last Updated: September 15, 2026
Military Power Solutions Market Size, Share, Industry Trend & Analysis Research Report Information By Type (Portable, Non-Portable), By Source (Batteries, Generators, Other Sources), By Platform (Air, Land, Sea), By Geography (North America, Europe, Asia-Pacific, South America, Middle East & Africa) — Forecast till 2035
Military Power Solutions Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)8.3%
2025 Market SizeUSD 8.95 Billion
2035 Market SizeUSD 19.83 Billion
Key Players
EnerSys
Saft
Cummins Inc.
Caterpillar Inc.
Kohler Energy
EaglePicher Technologies
Opportunities
  • Installation Microgrid Retrofits
  • Emerging Market Indigenization Programmes
  • Naval Hybrid Propulsion and Pulse Load Support
  1. 1 Market Summary |
    1. 1.1 Study Assumptions & Market Definition |
    2. 1.2 Scope of the Study |
    3. 1.3 Research Methodology
  2. 2 Key Report Takeaways |
    1. 2.1 By Type |
    2. 2.2 By Source |
    3. 2.3 By Geography
  3. 3 Market Size & Forecast (2021–2035) |
    1. 3.1 Historical Market Size (2021–2024) |
    2. 3.2 Base Year Assessment (2025) |
    3. 3.3 Forecast Market Size (2026–2035) |
    4. 3.4 Year-over-Year Growth Analysis
  4. 4 Driver Impact Analysis |
    1. 4.1 Defence Modernization Budget Expansion |
    2. 4.2 Silent-Watch and Hybrid Vehicle Electrification |
    3. 4.3 Soldier-Worn Battery Proliferation |
    4. 4.4 Unmanned Platform Fleet Expansion
  5. 5 Restraints Impact Analysis |
    1. 5.1 Lithium and Graphite Supply Concentration |
    2. 5.2 Qualification Cost and Duration |
    3. 5.3 Appropriation Volatility
  6. 6 Opportunities |
    1. 6.1 Installation Microgrid Retrofits |
    2. 6.2 Emerging Market Indigenization Programmes |
    3. 6.3 Naval Hybrid Propulsion and Pulse Load Support |
    4. 6.4 Power-as-a-Service and Fleet Telemetry Monetization |
    5. 6.5 Second-Life and Circular Battery Programmes
  7. 7 Regional Market Share & Country-Level Analysis |
    1. 7.1 North America | |
      1. 7.1.1 US | |
      2. 7.1.2 Canada | |
      3. 7.1.3 Mexico |
    2. 7.2 Europe | |
      1. 7.2.1 Germany | |
      2. 7.2.2 UK | |
      3. 7.2.3 France | |
      4. 7.2.4 Italy | |
      5. 7.2.5 Spain | |
      6. 7.2.6 Nordic Countries | |
      7. 7.2.7 Russia | |
      8. 7.2.8 Rest of Europe |
    3. 7.3 Asia-Pacific | |
      1. 7.3.1 China | |
      2. 7.3.2 India | |
      3. 7.3.3 Japan | |
      4. 7.3.4 South Korea | |
      5. 7.3.5 ASEAN | |
      6. 7.3.6 Rest of Asia-Pacific |
    4. 7.4 South America | |
      1. 7.4.1 Brazil | |
      2. 7.4.2 Argentina | |
      3. 7.4.3 Rest of South America |
    5. 7.5 Middle East & Africa | |
      1. 7.5.1 Saudi Arabia | |
      2. 7.5.2 UAE | |
      3. 7.5.3 South Africa | |
      4. 7.5.4 Egypt | |
      5. 7.5.5 Rest of Middle East & Africa
  8. 8 Future Outlook (2026–2035) |
    1. 8.1 Autonomy and Load Profile Evolution |
    2. 8.2 Availability Contracting and Supplier Economics |
    3. 8.3 The Electrification Supercycle |
    4. 8.4 Sustainability Reporting in Defence
  9. 9 Market Segmentation Analysis |
    1. 9.1 By Type | |
      1. 9.1.1 Portable | |
      2. 9.1.2 Non-Portable |
    2. 9.2 By Source | |
      1. 9.2.1 Batteries | |
      2. 9.2.2 Generators | |
      3. 9.2.3 Other Sources |
    3. 9.3 By Platform | |
      1. 9.3.1 Air | |
      2. 9.3.2 Land | |
      3. 9.3.3 Sea
  10. 10 Competitive Landscape |
    1. 10.1 Market Concentration Analysis |
    2. 10.2 Competitive Benchmarking Matrix |
    3. 10.3 Company Profiles | |
      1. 10.3.1 EnerSys | |
      2. 10.3.2 Saft (TotalEnergies) | |
      3. 10.3.3 Cummins Inc. | |
      4. 10.3.4 Caterpillar Inc. | |
      5. 10.3.5 Kohler Energy | |
      6. 10.3.6 EaglePicher Technologies | |
      7. 10.3.7 Bren-Tronics | |
      8. 10.3.8 Ultralife Corporation | |
      9. 10.3.9 Eaton Corporation | |
      10. 10.3.10 Rolls-Royce Power Systems | |
      11. 10.3.11 Denchi Group
  11. 11 Recent News & Developments
  12. 12 Report Scope & Methodology |
    1. 12.1 Study Period & Base Year |
    2. 12.2 Data Sources & Triangulation |
    3. 12.3 Abbreviations
  13. 13 Detailed Sources & Citations
  14. 14 Frequently Asked Questions
  15. 15 LIST OF TABLES |
  16. TABLE 1 Global Military Power Solutions Market Size & Forecast, by Revenue (USD Billion), 2021–2035 |
  17. TABLE 2 Global Military Power Solutions Market – Year-over-Year Growth Analysis, 2021–2035 |
  18. TABLE 3 Driver Impact Analysis Matrix, 2026–2035 |
  19. TABLE 4 Restraint Impact Analysis Matrix, 2026–2035 |
  20. TABLE 5 Global Market Size, by Region (USD Billion / Share), 2021–2035 |
  21. TABLE 6 North America Market Size, by Country, 2021–2035 (USD Billion) |
  22. TABLE 7 Europe Market Size, by Country, 2021–2035 (USD Billion) |
  23. TABLE 8 Asia-Pacific Market Size, by Country, 2021–2035 (USD Billion) |
  24. TABLE 9 South America Market Size, by Country, 2021–2035 (USD Billion) |
  25. TABLE 10 Middle East & Africa Market Size, by Country, 2021–2035 (USD Billion) |
  26. TABLE 11 Global Market Size, by Type, 2021–2035 (USD Billion) |
  27. TABLE 12 Global Market Size, by Source, 2021–2035 (USD Billion) |
  28. TABLE 13 Global Market Size, by Platform, 2021–2035 (USD Billion) |
  29. TABLE 14 North America Market Size, by Type, Source and Platform, 2021–2035 (USD Billion) |
  30. TABLE 15 Europe Market Size, by Type, Source and Platform, 2021–2035 (USD Billion) |
  31. TABLE 16 Asia-Pacific Market Size, by Type, Source and Platform, 2021–2035 (USD Billion) |
  32. TABLE 17 South America Market Size, by Type, Source and Platform, 2021–2035 (USD Billion) |
  33. TABLE 18 Middle East & Africa Market Size, by Type, Source and Platform, 2021–2035 (USD Billion) |
  34. TABLE 19 Competitive Benchmarking Matrix, 2026 |
  35. TABLE 20 Company Profiles – Key Players |
  36. TABLE 21 Recent Developments & Strategic Announcements, 2023–2025 |
  37. TABLE 22 Report Scope & Methodology Summary |
  38. TABLE 23 Detailed Sources & Citations Index
  39. 16 LIST OF FIGURES |
  40. FIGURE 1 Market Dynamics Overview – Drivers, Restraints and Opportunities |
  41. FIGURE 2 Industry Value Chain Analysis |
  42. FIGURE 3 Porter's Five Forces Analysis |
  43. FIGURE 4 Global Market Size Trend & Forecast, 2021–2035 (USD Billion) |
  44. FIGURE 5 Year-over-Year Growth Curve, 2022–2035 |
  45. FIGURE 6 Market Share by Type, 2025 vs 2035 |
  46. FIGURE 7 Market Share by Source, 2025 vs 2035 |
  47. FIGURE 8 Market Share by Platform, 2025 vs 2035 |
  48. FIGURE 9 Regional Revenue Share Distribution, 2025 |
  49. FIGURE 10 Regional CAGR Comparison, 2026–2035 |
  50. FIGURE 11 Country-Level Contribution Heat Map, 2025 |
  51. FIGURE 12 Competitive Landscape – Estimated Revenue Share Bands, 2026 |
  52. FIGURE 13 Strategic Positioning Matrix – Capability vs Scale |
  53. FIGURE 14 Technology Adoption Timeline, 2026–2035

Segmentation Quick Reference

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
By TypePortable; Non-PortableNon-PortablePortable
By SourceBatteries; Generators; Other SourcesBatteriesOther Sources
By PlatformAir; Land; SeaLandSea
By GeographyNorth America; Europe; Asia-Pacific; South America; Middle East & AfricaNorth AmericaAsia-Pacific


Market Segmentation Overview

By Type

Sub-SegmentKey Trend
PortableConsolidation of soldier-carried units onto a single distributed bus, cutting carried weight by roughly 30%
Non-PortableMigration from standalone diesel units toward hybridized shelter and vehicle-integrated architectures


Type demand splits along weight and mobility constraints. Non-portable equipment stays tied to programmes of record with long sustainment tails, while portable products refresh every three to five years and carry materially higher price per watt-hour.

By Source

Sub-SegmentKey Trend
BatteriesShift from lead-acid and primary lithium toward LFP and lithium-sulphur chemistries with domestic supply provenance
GeneratorsHybridization into range-extender roles rather than outright replacement of engine-driven generation
Other SourcesRising qualification activity for fuel cells and hybrid auxiliary units in low-signature applications


Source mix is moving decisively toward electrochemical storage, but engine-driven generation retains an irreplaceable role at expeditionary kilowatt and megawatt scale. Hybrid pairing of the two is now the default architecture on new-start requirements.

By Platform

Sub-SegmentKey Trend
AirRapid unit growth from unmanned aircraft fleets and associated field recharge infrastructure
LandSilent-watch retrofits and hybrid drive integration across armoured and tactical vehicle fleets
SeaInstalled electrical margin expansion to support directed-energy and advanced radar loads


Platform demand tracks fleet size for land and air, but value per unit for sea. Naval programmes deliver fewer, larger awards with longer qualification cycles and correspondingly higher barriers to entry.




Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.