Textile Waste Management Market Summary
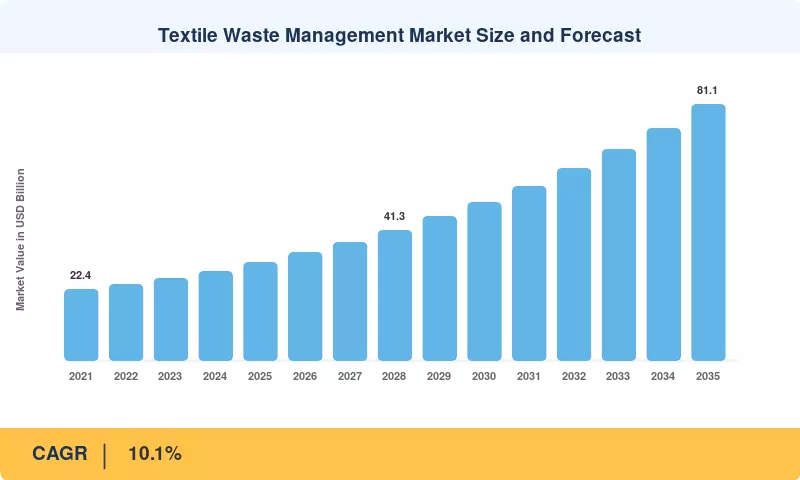
The Textile Waste Management Market was valued at USD 31.0 Billion in 2025 and is projected to reach USD 34.1 Billion in 2026, rising to USD 81.1 Billion by 2035 at a CAGR of 10.1% over 2026–2035. Two policy shifts anchor this trajectory. The European Union made separate collection of textiles mandatory for all member states from January 2025, and the revised Waste Framework Directive now requires producer-funded extended producer responsibility (EPR) schemes for textiles [19]. In the United States, California's SB 707 created the country's first statewide textile EPR program in 2024 [5].
Legacy disposal is giving way to engineered recovery. Roughly 73% of discarded clothing worldwide is still landfilled or incinerated, and less than 1% of clothing material is recycled into new garments [1]. Collection networks originally built for second-hand resale are being retrofitted with near-infrared sorting lines, mechanical fiber-opening plants and chemical depolymerization units. Brands are now underwriting capacity directly: H&M Group's USD 600 million, seven-year offtake agreement with recycler Syre is the clearest signal that fiber-to-fiber output has a committed buyer base [13].
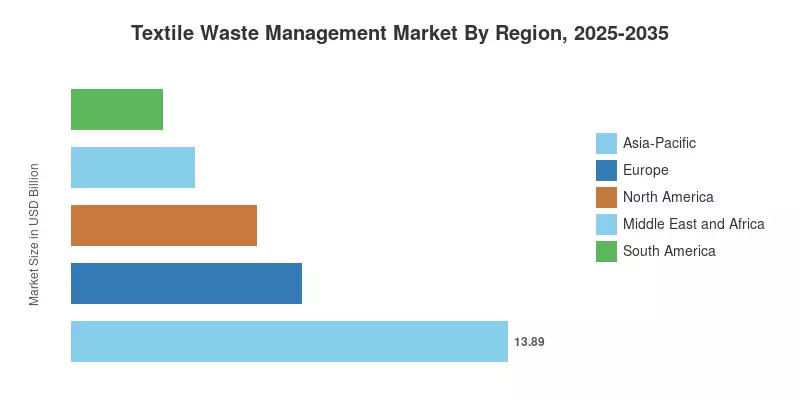
Asia-Pacific dominates with a 44.8% share in 2025, reflecting the concentration of garment manufacturing in China, Bangladesh, India and ASEAN economies. Middle East and Africa is the fastest-growing region at a 12.6% CAGR, supported by Gulf landfill-diversion programs . Europe ranks second with a 23.6% share, driven by EPR rollout. Over the next decade, the Textile Waste Management Market will be judged less by collection volume and more by how much of that volume returns to fiber-grade quality.
Key Report Takeaways
• By Waste Source
- Pre-consumer (Manufacturing Scrap) accounts for 66.4% of the Textile Waste Management Market in 2025, as homogeneous cutting-room scrap is simpler to bale and recycle.
- Post-consumer (Used Garments & Household Textiles) is set to expand at a 10.3% CAGR through 2035 as household separate-collection mandates take hold.
• By Waste Type
- Synthetic Fibers hold a 50.4% share, led by polyester from fast-fashion apparel.
- Cellulosic & Regenerated Fibers are forecast at a 9.2% CAGR, the quickest among fiber cohorts, as dissolving-pulp routes mature.
• By Service
- Landfill / Open Dumping still absorbs a 50.6% share of handled volumes, exposing a large processing gap.
- Recycling (Mechanical, Chemical/Enzymatic, Reuse) is projected at a 10.7% CAGR, the fastest-expanding service line in the Textile Waste Management Market.
• By End-User
- Industrial Manufacturing (Apparel & Footwear) commands a 57.0% share, supported by predictable mill and factory waste streams.
- Residential / Household posts the highest end-user growth at a 13.1% CAGR.
• By Region
- Asia-Pacific leads with a 44.8% share in 2025.
- Middle East and Africa is forecast to grow at a 12.6% CAGR.
- North America generated USD 5.9 Billion in 2025.
Market Size and Forecast (2021–2035)
Estimates for the Textile Waste Management Market combine bottom-up tallies of collected, sorted, recycled and disposed tonnage with service-fee benchmarks, validated top-down against public waste statistics from the US EPA, the European Environment Agency and national textile ministries [3][4]. Growth steps up in 2025–2026 as the EU separate-collection mandate and the July 2026 ban on destroying unsold apparel convert previously unmanaged volumes into paid service contracts [19][22].



 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA


