Passenger Vehicle Telematics Market Summary
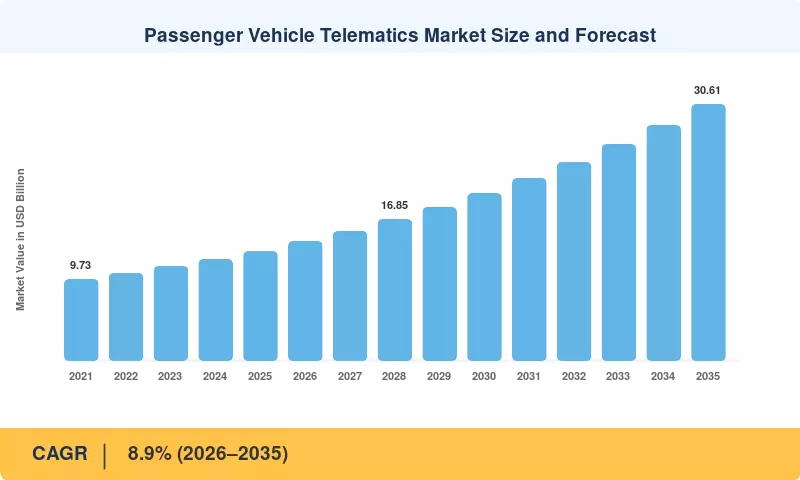
The Passenger Vehicle Telematics Market reached USD 13.05 Billion in 2025 and enters the forecast window at USD 14.21 Billion in 2026, advancing to USD 30.61 Billion by 2035 at an 8.9% CAGR. Two catalysts anchor that trajectory. The European Union's eCall regulation, which obliges every new passenger car type-approved in the bloc to carry an emergency call unit, converted telematics hardware from an option into a homologation requirement [1]. Second, automakers have committed heavily to software-defined vehicle architectures, with combined announced spending across the top ten global OEMs exceeding USD 60 billion through 2030 on electrical architecture and connected-services platforms [2].
Legacy proprietary head units, single-purpose GPS boxes and 2G-era modems are being retired. In their place sit domain-controller architectures with always-on 4G/5G modems, over-the-air update pipelines and cloud data lakes that treat the vehicle as a managed endpoint. GSMA estimates cellular IoT connections in automotive will pass 500 million units globally by 2030, a shift that redefines the cost base of the Passenger Vehicle Telematics Market [3].
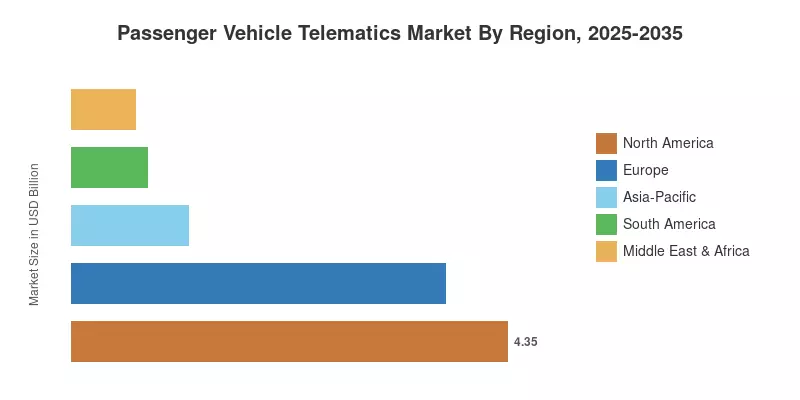
North America holds 33.3% of 2025 revenue, supported by mature insurance telematics underwriting and dense fleet-leasing penetration. Asia-Pacific is the fastest-growing region at a 9.0% CAGR through 2035, driven by China's national vehicle-connectivity mandates and India's push on commercial-vehicle tracking compliance. Europe follows North America closely on the strength of regulatory fitment, and its share is expected to erode only marginally as Asian volumes scale. The next decade will decide whether OEMs or independent platform vendors capture the recurring-revenue layer of the Passenger Vehicle Telematics Market.
Key Report Takeaways
• By Service
- Fleet management commanded 35.2% of Passenger Vehicle Telematics Market revenue in 2025, reflecting mature logistics and corporate-fleet adoption
- Insurance telematics is the fastest-expanding service line at a 12.2% CAGR across 2026–2035
• By Sales Channel
- OEM-fitted platforms accounted for 70.4% of installed value in 2025
- The aftermarket channel is projected to grow at an 11.0% CAGR through 2035
• By Connectivity Solution
- Embedded modems represented 66.6% of the Passenger Vehicle Telematics Market in 2025
- Integrated-smartphone architectures are forecast to advance at a 13.6% CAGR
• By End User
- Fleet operators held a 39.0% revenue share in 2025
- Car-sharing and mobility providers post the steepest growth at a 13.4% CAGR
• By Region
- North America led with 33.3% of 2025 revenue
- Asia-Pacific is the fastest-growing geography in the Passenger Vehicle Telematics Market at a 9.0% CAGR
- Europe generated USD 3.73 billion in 2025
Market Size and Forecast (2021–2035)
Figures below are built bottom-up from passenger-car production and parc data, cross-checked against OEM connected-services disclosures, tier-one supplier segment reporting and telecom operator automotive-IoT connection counts. Historical years are reconciled to registration statistics from ACEA, CAAM, and the US Bureau of Transportation Statistics; forecast years apply attach-rate curves by region and price band. Currency is held at constant 2025 US dollars throughout the Passenger Vehicle Telematics Market model.




 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA



