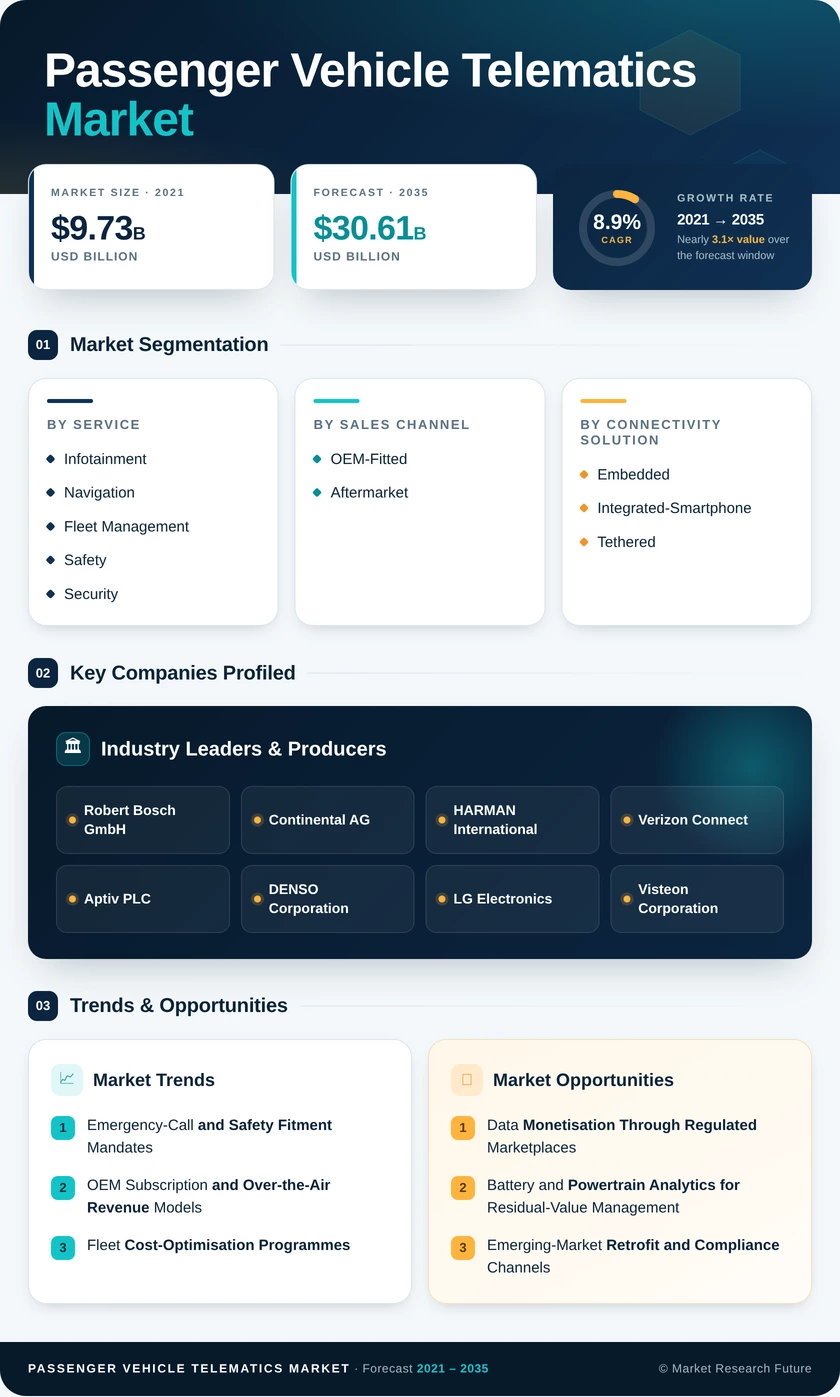
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| By Service | Infotainment and Navigation; Fleet Management; Safety and Security; Diagnostics and Prognostics; Insurance Telematics; Other Services | Fleet Management (35.2% share, 2025) | Insurance Telematics (12.2% CAGR, 2026–2035) |
| By Sales Channel | OEM-Fitted; Aftermarket | OEM-Fitted (70.4% share, 2025) | Aftermarket (11.0% CAGR, 2026–2035) |
| By Connectivity Solution | Embedded; Integrated-Smartphone; Tethered | Embedded (66.6% share, 2025) | Integrated-Smartphone (13.6% CAGR, 2026–2035) |
| By End-User | Private Consumers; Fleet Operators; Insurance and Leasing Companies; Car-Sharing and Mobility Providers; Other End Users | Fleet Operators (39.0% share, 2025) | Car-Sharing and Mobility Providers (13.4% CAGR, 2026–2035) |
Market Segmentation Overview
By Service
| Sub-Segment | Key Trend |
| Infotainment and Navigation | Margin compression as smartphone feature parity erodes premium positioning |
| Fleet Management | Consolidation of routing, coaching, and maintenance into single-pane dashboards |
| Safety and Security | Regulatory fitment guarantees a hardware floor independent of consumer demand |
| Diagnostics and Prognostics | Increasingly bundled into fleet subscriptions rather than sold standalone |
| Insurance Telematics | Move from pilot programmes to standard underwriting inputs |
| Other Services | Early smart-city, V2X and digital-twin deployments building long-run optionality |
Fleet Management leads this dimension because its savings appear directly on fuel and maintenance invoices, giving procurement teams a defensible payback case that Infotainment and Navigation cannot match once smartphone mirroring covers the same functions. Insurance Telematics grows fastest as carriers accept behavioural data into rating models and regulators clarify consent requirements. Diagnostics and Prognostics quietly expands its footprint by riding inside fleet contracts, while Safety and Security holds a stable share anchored to mandatory emergency-call fitment rather than discretionary spend.
By Sales Channel
| Sub-Segment | Key Trend |
| OEM-Fitted | Factory integration secures data ownership and enables over-the-air monetisation |
| Aftermarket | Modular plug-and-play devices sold through insurers, banks and telecom retail |
OEM-Fitted dominates because homologation certainty and warranty alignment make factory installation the default for any vehicle sold into a mandate market, and it gives manufacturers the data rights needed to sell subscriptions after delivery. Aftermarket grows faster from a smaller base by serving the ageing parc in India, Brazil and South Africa, where new-vehicle penetration is low, and theft or compliance pressures justify retrofit. Regional certification schemes for retrofit hardware have narrowed the credibility gap that previously kept insurers from underwriting aftermarket-derived data.
By Connectivity Solution
| Sub-Segment | Key Trend |
| Embedded | Always-on links required for emergency calls, secure updates and 5G edge services |
| Integrated-Smartphone | Low-cost route to connected features on entry and mid-tier models |
| Tethered | Retained for rental fleets and short-cycle deployments despite lifecycle mismatch |
Embedded holds the commanding share because only a vehicle-owned modem satisfies emergency-call regulation and can deliver authenticated software updates, and premium brands are restricting third-party mirroring specifically to protect that position. Integrated-Smartphone posts the fastest growth as automakers extend connectivity to price bands where a dedicated modem cannot be justified on bill of materials. Tethered dongles persist in rental and pilot applications, but their dependence on handset operating-system cycles makes them a poor fit for a vehicle service life measured in more than a decade.
By End-User
| Sub-Segment | Key Trend |
| Private Consumers | Largest unit base but weakest revenue per vehicle after free-trial expiry |
| Fleet Operators | Highest-utilisation assets sustaining hardware refresh and software upsell |
| Insurance and Leasing Companies | Buying data to price risk and protect residual values on electrified assets |
| Car-Sharing and Mobility Providers | Remote access and per-trip billing are operational prerequisites |
| Other End Users | Government and emergency fleets procuring through public tender cycles |
Fleet Operators lead because last-mile delivery and corporate pools run assets hard enough that fuel and maintenance savings recover hardware cost within a year, which sustains a replacement cycle Private Consumers never generate. Car-Sharing and Mobility Providers grow fastest since keyless access, remote immobilisation and damage attribution are not optional features for them but the operating system of the business. Insurance and Leasing Companies increasingly buy the same data streams for underwriting and residual-value protection, making them the most commercially attractive counterparty per connected vehicle.

 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA