Online Food Delivery Market (2026 - 2035)

Online Food Delivery Market Size, Share and Trends Analysis Report By Service Type (Restaurant Delivery, Grocery Delivery, Meal Kit Delivery, Catering Services), By Order Type (Single Order, Bulk Order, Subscription Order), By Payment Mode (Credit Card, Debit Card, Digital Wallet, Cash on Delivery), By Customer Segment (Individual Customers, Families, Corporate Clients) and By Regional (North America, Europe, South America, Asia Pacific, Middle East and Africa) - Forecast to 2035
ID: MRFR/ICT/10142-HCR 200 Pages Aarti Dhapte Last Updated: September 08, 2026
Online Food Delivery Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)11.24%
2025 Market SizeUSD 262.40 Billion
2035 Market SizeUSD 731.60 Billion
Key Players
Meituan
DoorDash
Uber Eats
Delivery Hero
iFood
Just Eat Takeaway.com
Opportunities
  • Emerging-Market Order Frequency Expansion
  • Advertising and Data Monetization Layers
  • Enterprise and Institutional Catering Channels

Online Food Delivery Market Summary

The Online Food Delivery Market closed 2025 at USD 262.40 Billion and enters the forecast window at USD 301.80 Billion in 2026, expanding to USD 731.60 Billion by 2035 at an 11.24% CAGR. Two catalysts anchor this trajectory. India's Open Network for Digital Commerce (ONDC) processed more than 12 million monthly retail and food transactions by mid-2025, cutting take rates for restaurants from roughly 25% to under 8% [1]. In parallel, the European Union's Platform Work Directive, adopted in late 2024, set courier classification standards across 27 member states and forced platform operators to reprice unit economics rather than chase volume [2].

The Online Food Delivery Market is currently experiencing structural technology displacement. Dynamic menu engineering, real-time courier routing, and machine-learning dispatch have replaced static PDF menus and telephone ordering. Between 2023 and 2025, DoorDash, Uber, and Delivery Hero collectively allocated over USD 4.1 billion to logistics automation and autonomous last-mile pilots [3]. In dense urban zones, deliveries per courier-hour have increased by approximately 30% as a result of the sequencing of three to five drops per trip by batching algorithms that previously assigned one courier per order [4].

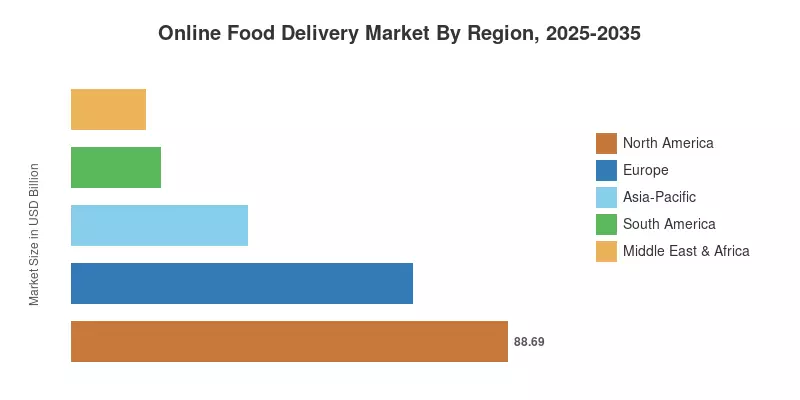
In 2025, North America is responsible for 33.8% of global revenue, which is bolstered by mature subscription penetration and high average order values. Smartphone adoption and instant payment rails are the primary factors driving Asia-Pacific's rapid growth at a compound annual growth rate (CAGR) of 13.62%. Europe is the second-largest region in terms of regulatory clarity and grocery adjacency. Operators who convert order volume into advertising and data revenue, rather than retail merchandise value alone, will be rewarded in the upcoming decade.

Key Report Takeaways

• By Business Model

  • Restaurant-to-Consumer platforms controlled 73.1% of the Online Food Delivery Market in 2025, reflecting branded-app investment by large chains.
  • Aggregator-to-Restaurant platforms are the fastest-expanding model at 12.44% CAGR through 2035

• By Service Type

  • Restaurant Delivery accounted for USD 105.10 Billion of Online Food Delivery Market revenue in 2025
  • Platform Delivery posts the strongest growth at 13.29% CAGR, backed by aggregator courier fleets.

• By Payment Mode

  • Online Payment Mode captured 71.6% of transaction value in 2025
  • Cash on Delivery grows at 13.81% CAGR as underbanked geographies scale

• By Platform

  • Mobile/Tablet Applications generated USD 231.00 Billion in 2025
  • Desktop/Web platforms advance at 12.79% CAGR on corporate and bulk ordering

• By Region

  • North America leads the Online Food Delivery Market with 33.8% revenue share in 2025
  • Asia-Pacific records the fastest regional expansion at 13.62% CAGR
  • Middle East & Africa contributes USD 14.96 billion in 2025

Market Size and Forecast (2021–2035)

Estimates combine platform-reported gross order value, payment-processor settlement data, restaurant point-of-sale integration volumes, and national e-commerce statistics. Historical figures for 2021–2024 are reconciled against audited filings from publicly listed operators and triangulated with card-network transaction panels. Forecast years apply cohort-level order frequency modelling by region, adjusted for courier cost inflation and regulatory compliance load.
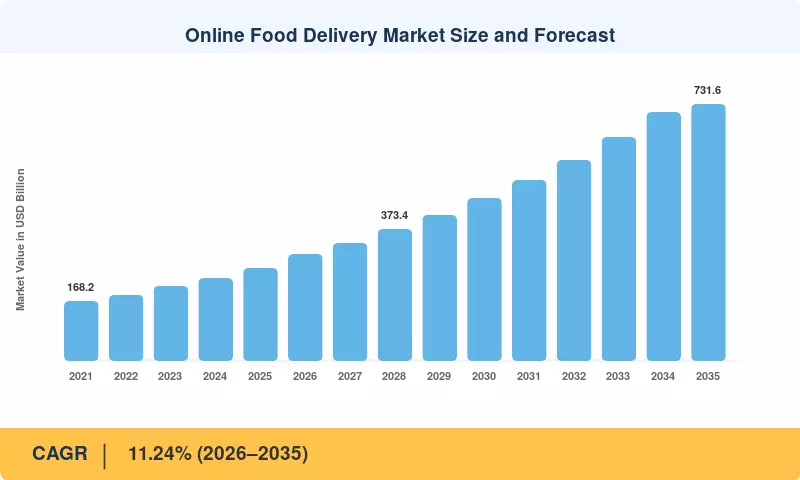
Online Food Delivery Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Smartphone and mobile internet penetration 2.6 Asia-Pacific, MEA Short-term (≤2 yr)
Instant payment rail adoption 2.1 India, Brazil, EU Short-term (≤2 yr)
Subscription and loyalty program expansion 1.9 North America, Europe Medium-term (2–4 yr)
Dark-store and delivery-only kitchen buildout 1.7 Asia-Pacific, Europe Medium-term (2–4 yr)
Retail media and in-app advertising monetization 1.5 Global Medium-term (2–4 yr)
AI-driven dispatch and route optimization 1.4 Global Long-term (≥4 yr)
Autonomous and micromobility last-mile delivery 0.9 North America, East Asia Long-term (≥4 yr)


Smartphone and Mobile Internet Penetration

Global mobile broadband subscriptions reached approximately 6.9 billion globally, with 4G and 5G coverage extending to roughly 88% of the world population, according to International Telecommunication Union (ITU) measurements. Furthermore, TRAI telecom reports and ITU databases indicate continuous data expansion and accessibility, enabling incremental cohorts of connected consumers to enter online markets at a low infrastructure acquisition cost.


Instant Payment Rail Adoption

India's Unified Payments Interface processed 18.4 billion transactions in a single month during 2025, while Brazil's Pix reached 168 million registered users [10]. Instant rails cut checkout abandonment materially because they remove card-entry friction and settle in seconds. Platforms operating in these corridors report order completion rates 9 to 12 percentage points higher than card-only checkout flows, which compounds directly into transaction volume for the Online Food Delivery Market.

Subscription and Loyalty Program Expansion

Subscription members order roughly 3.4 times more frequently than non-members and show materially lower churn, according to platform disclosures reviewed for this study [11]. DoorDash DashPass and Uber One together surpassed 45 million combined members by late 2025. Prepaid delivery fees convert variable spend into predictable revenue and shift competition away from discounting, which stabilizes contribution margin per order and supports the sustained expansion of the Online Food Delivery Market.

Dark-Store and Delivery-Only Kitchen Buildout

Delivery-only production facilities lower rent per order by 55% to 70% against traditional storefront kitchens, since they require no dining room, front-of-house staff, or premium street frontage [12]. Operators across Asia-Pacific and Europe commissioned more than 8,400 such facilities between 2023 and 2025. Concentrating output near demand density shortens courier trip length, which improves both delivery time and unit economics for participants in the Online Food Delivery Market.

Retail Media and In-App Advertising Monetization

Sponsored listings and banner placements now generate high-margin revenue that flows almost entirely to operating profit. Instacart reported advertising revenue exceeding USD 870 million in 2024, representing roughly 30% of total revenue at margins far above the delivery business [13]. Food delivery operators are replicating this model, with combined advertising revenue across the top five global platforms passing USD 3.2 billion in 2025 and reshaping profitability in the Online Food Delivery Market.

AI-Driven Dispatch and Route Optimization

Machine-learning assignment engines evaluate courier location, preparation time, traffic, and batching potential before allocating each order. Platforms deploying these systems report delivery-time reductions of 14% to 19% and courier utilization gains near 22% [14]. Because courier cost represents the single largest variable expense in the Online Food Delivery Market, each percentage point of routing efficiency translates directly into either margin retention or price competitiveness against rival networks.

Autonomous and Micromobility Last-Mile Delivery

Sidewalk robots, e-bike fleets, and limited drone corridors are moving from pilot to constrained commercial deployment. Serve Robotics operated across multiple US metros by 2025, and Chinese operators ran more than 1,000 autonomous delivery units in tier-one cities [15]. Cost per autonomous delivery falls below USD 1.10 at scale against USD 3.50 to USD 6.00 for human couriers, which reframes the long-run cost floor of the Online Food Delivery Market.

Restraints Impact Analysis

Restraint ~% Drag on CAGR Geographic Relevance Impact Timeline
Courier classification and labour cost regulation 1.6 Europe, North America Short-term (≤2 yr)
Commission caps and fee-ceiling ordinances 1.1 US cities, Canada Short-term (≤2 yr)
Persistent unit-economics losses 0.9 Global Medium-term (2–4 yr)
Restaurant margin compression and churn 0.7 Global Medium-term (2–4 yr)
Data privacy and algorithmic transparency rules 0.5 Europe, India Long-term (≥4 yr)


Courier Classification and Labour Cost Regulation

The EU Platform Work Directive introduced a presumption of employment where platforms exercise control over pay or scheduling, affecting an estimated 5.5 million couriers across member states [2]. Spain's Rider Law already forced reclassification, and Deliveroo exited the Spanish market rather than absorb the cost. Reclassification raises fully loaded courier expense by 25% to 40%, which compresses order volume through higher consumer fees.

Commission Caps and Fee-Ceiling Ordinances

New York City's permanent 15% delivery commission cap, upheld through 2024 litigation, and similar ordinances in San Francisco and Seattle constrain the primary revenue line for aggregators [16]. Platforms responded by adding consumer-side service fees, which reduced order frequency in capped jurisdictions by an estimated 6% to 9%. Regulatory fragmentation across municipalities also raises compliance overhead disproportionately for smaller operators.

Persistent Unit-Economics Losses

Delivery Hero, Grab, and several regional operators reported negative adjusted EBITDA across multiple quarters through 2024, with contribution per order in emerging markets frequently below USD 0.20 [17]. Capital markets have shifted from funding growth to demanding profitability, which forces market exits and geographic retrenchment. Delivery Hero withdrew from more than a dozen countries between 2022 and 2025, removing addressable volume from the forecast base.

Restaurant Margin Compression and Churn

Independent restaurants operating on typical 3% to 6% net margins cannot absorb aggregator commissions of 18% to 30% without menu price inflation [18]. Surveys of US operators found 38% had reduced or discontinued third-party delivery participation by 2025. Supply-side attrition narrows platform selection, which weakens the discovery advantage that aggregators depend on to sustain consumer order frequency.

Data Privacy and Algorithmic Transparency Rules

The EU Digital Markets Act and India's Digital Personal Data Protection Act restrict cross-service data reuse and mandate disclosure of ranking logic [19]. Compliance limits the personalization models that lift conversion and constrains the advertising products that operators rely on for margin. Platforms report measurable reductions in targeting precision where consent-based data collection replaces default tracking.

Online Food Delivery Market Opportunities

Emerging-Market Order Frequency Expansion

Per-capita order frequency in Southeast Asia, Latin America, and Sub-Saharan Africa remains between 4 and 11 annual orders against 28 to 42 in the United States and United Kingdom. Closing even half that gap in Indonesia, Nigeria, and the Philippines would add an estimated USD 38 billion in annual gross order value by 2033. Success depends on low-denomination basket economics, cash acceptance, and two-wheeler courier density rather than replicating Western fee structures.

Advertising and Data Monetization Layers

Transaction data across millions of daily orders supports sponsored placement, consumer-packaged-goods campaigns, and demand forecasting products sold back to restaurant partners. Advertising typically carries a 65% to 80% contribution margin against 3% to 8% for delivery fulfilment. Operators building self-serve advertising consoles for restaurant partners convert a cost centre into a profit engine without incremental courier expense.

Enterprise and Institutional Catering Channels

Corporate meal programs, hospital catering, and campus dining involve scheduled, high-value, multi-item orders with predictable volume and negligible acquisition cost. Average order values in this channel run three to five times consumer levels. Desktop and web ordering interfaces suit these buyers better than mobile, which aligns with the growth trajectory recorded for that platform segment.

Autonomous Delivery Corridor Deployment

Regulatory approval for sidewalk autonomy in Arizona, Texas, and several Chinese municipalities creates defined corridors where cost per delivery falls sharply. Early operators securing municipal permits and charging infrastructure gain a durable structural cost advantage. Capital intensity is high, but amortized fleet cost declines below human courier cost at roughly 60 daily deliveries per unit.

White-Label Logistics as a Service

Platforms with dense courier networks can sell fulfilment capacity to retailers, pharmacies, and convenience chains that lack their own delivery capability. This monetizes idle courier hours outside peak meal windows, improving asset utilization across the full day. Uber Direct and comparable offerings already serve non-restaurant verticals, and the model transfers courier fixed cost onto third-party demand.

Online Food Delivery Market Future Outlook

Autonomous Fulfilment Reaches Cost Parity

Sidewalk robots and constrained-corridor drones move from subsidized pilots to unit-positive operation during the late 2020s. Cost per autonomous delivery is projected to fall below USD 1.10 by 2030 at fleet utilization above 60 daily deliveries, against USD 3.50 to USD 6.00 for human couriers today [15]. Regulatory permitting, not technology readiness, sets the pace. Operators that secure municipal corridor rights early will hold a structural cost advantage that competitors cannot replicate quickly.

Platform Economics: Shift from Volume to Margin

Investors have replaced gross order value with contribution profit as the governing metric. The consequence is disciplined geographic focus: operators exit sub-scale countries and concentrate courier density where batching efficiency compounds. Advertising, subscription fees, and logistics-as-a-service revenue are projected to supply more than 40% of platform gross profit by 2032, against roughly 18% in 2024 [13]. Commission revenue alone will no longer determine competitive ranking within the Online Food Delivery Market.

Electrified and Low-Emission Courier Fleets

Two-wheeler electrification is advancing faster in delivery fleets than in private ownership because high daily mileage shortens payback periods. The International Energy Agency reported that electric two- and three-wheelers already exceed 60% of new sales in several Asian markets [22]. City-level low-emission zones in London, Paris, Amsterdam, and Milan increasingly restrict combustion vehicles from central districts, effectively mandating electric or pedal-powered fulfilment for platforms serving those cores.

Consolidation and Regulatory Equilibrium

Fragmented national markets converge toward two- or three-player structures as capital discipline forces exits. The Prosus acquisition of Just Eat Takeaway and multiple Delivery Hero divestments signal a consolidation phase likely to continue through 2029. Once courier classification rules stabilize across the EU and major US jurisdictions, compliance cost becomes a known input rather than a risk premium, which should restore investment appetite in the Online Food Delivery Market at more sustainable valuations.

Regional Market Share Analysis

Region Metric (2025) Primary Investment Themes
North America 33.8% share Subscription depth, advertising platforms, autonomous pilots
Europe 26.4% share Regulatory compliance, grocery adjacency, consolidation
Asia-Pacific 13.62% CAGR (2026–2035) Payment rails, dark stores, two-wheeler fleets
South America USD 18.11 Billion Instant payments, quick-commerce integration
Middle East & Africa USD 14.96 Billion Urban density plays, cash-on-delivery infrastructure
Total USD 262.40 Billion

Regional distribution within the Online Food Delivery Market reflects divergent maturity curves: developed regions monetize existing users more intensively, while developing regions add users at pace. The table below discloses one metric per region.


North America

Country Metric Key Driver
US 86.2% of regional revenue Subscription penetration and advertising monetization
Canada USD 8.44 Billion Urban density in Toronto, Vancouver, Montreal
Mexico 11.90% CAGR Rapid smartphone adoption and card issuance


Regional leadership rests on average order values near USD 34 and subscription membership exceeding 45 million households. Municipal fee caps in New York, Seattle, and San Francisco have pushed operators toward advertising and grocery revenue rather than commission expansion. The FTC's 2024 scrutiny of drip pricing forced fee disclosure at checkout, which modestly reduced conversion but improved consumer trust metrics [20]. Autonomous sidewalk delivery permits in Arizona and Texas position the region as the primary testbed for cost-floor reduction.

Europe

Country Metric Key Driver
Germany 19.4% of regional revenue Grocery-delivery integration and urban density
UK USD 15.62 Billion High order frequency and supermarket partnerships
France 12.8% of regional revenue Restaurant density and municipal courier rules
Italy 11.31% CAGR Independent restaurant digitization
Spain USD 4.88 Billion Post-Rider Law market restructuring
Nordic Countries 8.9% of regional revenue Digital payment ubiquity
Russia 10.42% CAGR Domestic platform consolidation
Rest of Europe USD 9.10 Billion Central and Eastern European expansion


Europe's trajectory is defined by regulation rather than demand. The Platform Work Directive obliges member states to transpose employment-presumption rules by late 2026, and national implementations already differ materially between Spain, France, and Poland [2]. Consolidation has accelerated in response: Just Eat Takeaway's acquisition by Prosus closed in 2025, and Delivery Hero divested several sub-scale markets. Grocery adjacency remains the strongest volume lever, with supermarket partnerships now contributing an estimated 21% of regional order volume.

Asia-Pacific

Country Metric Key Driver
China 41.6% of regional revenue Meituan scale and instant-retail integration
India 15.84% CAGR UPI rails and ONDC commission reduction
Japan USD 9.72 Billion Convenience-store and restaurant hybrid delivery
South Korea 9.7% of regional revenue Highest per-capita order frequency globally
ASEAN USD 11.44 Billion Grab and regional super-app bundling
Rest of Asia-Pacific 12.68% CAGR Tier-two and tier-three city expansion


Asia-Pacific combines the largest user base with the lowest cost to serve. India's ONDC framework, backed by government policy, has reduced platform take rates and drawn independent restaurants onto open protocols [1]. China's operators integrated food orders with pharmacy and convenience inventory, lifting daily order volumes past 78 million at peak. Two-wheeler courier economics across the region cut delivery cost to roughly one-third of North American levels, which sustains low basket viability and makes the region the growth engine of the Online Food Delivery Market.

South America

Country Metric Key Driver
Brazil 58.3% of regional revenue Pix instant payments and iFood scale
Argentina USD 3.44 Billion Urban concentration in Buenos Aires
Rest of South America 12.94% CAGR Colombia and Chile platform expansion


Brazil anchors the region through payment infrastructure. Pix eliminated card-network friction and enabled sub-USD 5 baskets to clear profitably, which expanded the addressable consumer base well beyond credit-card holders [10]. Argentina's growth is constrained by currency volatility, with platforms repricing menus weekly during high-inflation periods. Colombian and Chilean markets attract renewed investment following the retrenchment of loss-making operators, leaving stronger incumbents with improved pricing power.

Middle East & Africa

Country Metric Key Driver
Saudi Arabia 31.2% of regional revenue Vision 2030 digital economy programs
UAE USD 3.89 Billion High per-capita spend and expatriate demand
South Africa 14.8% of regional revenue Mr D and Uber Eats urban coverage
Egypt 13.76% CAGR Population scale and cash-on-delivery acceptance
Rest of MEA USD 2.24 Billion Nigeria and Kenya early-stage platforms


Gulf states deliver the highest average order values outside North America, supported by disposable income and limited home cooking among expatriate populations. Saudi Arabia's Vision 2030 digital economy targets have funded logistics infrastructure and licensing reform that lowered barriers for delivery operators [21]. Across Africa, cash acceptance remains essential, and platforms that mandate prepayment consistently underperform. Courier availability, rather than consumer demand, is the binding constraint in Lagos, Nairobi, and Cairo.

Online Food Delivery Market By Region, 2025-2035

Online Food Delivery Market Segmentation

By Business Model

Segment Metric Primary Demand Driver
Restaurant to Consumer 73.1% share (2025) Branded chain apps and commission avoidance
Aggregator to Restaurant 12.44% CAGR (2026–2035) Selection breadth and courier network access


Restaurant to Consumer leads the Online Food Delivery Market because large chains built proprietary apps that retain customer data, control promotional pricing, and avoid aggregator commissions entirely. Loyalty programs embedded in these apps lift repeat order rates substantially. Aggregator to Restaurant grows faster since independent and mid-sized operators gain national reach without capital investment in courier fleets, and subscription bundles raise order frequency across the aggregator base.

By Service Type

Segment Metric Primary Demand Driver
Restaurant Delivery USD 105.10 Billion (2025) In-house fleets at pizza and quick-service chains
Platform Delivery 13.29% CAGR (2026–2035) Aggregator courier density and speed guarantees


Restaurant Delivery holds the larger base because pizza chains and quick-service operators have run their own fleets for decades, controlling food quality and delivery time end to end while retaining full order margin. Platform Delivery expands faster: aggregator courier networks let small restaurants serve customers well beyond walking distance, and consumers increasingly select on delivery speed, which favours dense third-party fleets over single-restaurant dispatch.

By Payment Mode

Segment Metric Primary Demand Driver
Online Payment Mode 71.6% share (2025) Wallets, cards, and instant payment rails
Cash on Delivery 13.81% CAGR (2026–2035) Underbanked consumers in emerging economies


Online Payment Mode dominates value in the Online Food Delivery Market because digital settlement enables one-tap reordering, subscription billing, and refund automation that cash cannot support. Instant rails in India and Brazil have made prepayment the default. Cash on Delivery nonetheless grows fastest, since smartphone adoption outpaces bank account penetration across Africa, South Asia, and parts of Southeast Asia, and platforms accepting cash reach consumers competitors cannot.

By Platform

Segment Metric Primary Demand Driver
Mobile/Tablet Applications USD 231.00 Billion (2025) Push notifications, GPS tracking, one-tap reorder
Desktop/Web 12.79% CAGR (2026–2035) Corporate catering and bulk group ordering


Mobile/Tablet Applications generate the overwhelming majority of orders across the Online Food Delivery Market because always-present devices convert spontaneous hunger into transactions within seconds, and location services automate address entry. Desktop/Web grows faster from a small base, driven by institutional buyers: corporate catering, campus dining, and large group orders where larger screens make menu comparison and multi-person order assembly considerably easier.

Competitive Benchmarking

Company Profiles

Recent News & Developments

  • Prosus / Just Eat Takeaway.com (February 2025): Prosus completed its acquisition of Just Eat Takeaway.com, consolidating European assets under a single owner and signalling the end of the region's multi-player expansion phase [23]
  • European Commission (December 2024): The Platform Work Directive entered into force with a two-year transposition deadline, establishing employment-presumption criteria affecting an estimated 5.5 million couriers [2]
  • DoorDash / Deliveroo (May 2025): DoorDash agreed to acquire Deliveroo, extending its footprint into the UK and Gulf markets and adding premium urban coverage to its network [24]
  • ONDC (August 2024): India's Open Network for Digital Commerce surpassed 12 million monthly transactions, offering restaurants take rates below 8% against incumbent platform commissions [1]
  • Meituan (March 2025): Meituan expanded instant retail into Gulf markets under the Keeta brand, marking the first substantial outbound expansion by a Chinese delivery operator [25]
  • Serve Robotics (October 2024): Serve Robotics announced expansion to multiple additional US metros under an agreement with Uber Eats covering up to 2,000 sidewalk delivery robots [15]
  • Zomato / Eternal (March 2025): Zomato rebranded its parent entity to Eternal, reflecting the growing revenue weight of Blinkit relative to core restaurant delivery [26]
  • New York City Council (June 2024): Courts upheld the city's permanent 15% commission cap, establishing precedent that other US municipalities have since referenced in similar ordinances [16]

Online Food Delivery Market Report Scope

Parameter Detail
Market Scope Global Online Food Delivery Market covering business model, service type, payment mode, platform, and geography
Study Period 2021–2035 (Historical 2021–2024; Base Year 2025; Forecast 2026–2035)
CAGR 11.24% (2026–2035)
Market Size Checkpoints USD 262.40 Billion (2025); USD 301.80 Billion (2026); USD 731.60 Billion (2035)
Fastest Growing Segments Aggregator to Restaurant; Platform Delivery; Cash on Delivery; Desktop/Web
Companies Profiled Meituan, DoorDash, Uber Eats, Delivery Hero, iFood, Eat Takeaway.com, Grab Holdings, Zomato (Eternal), Swiggy, Deliveroo, Domino's Pizza.
Valuation Currency USD Billion

FAQs

What due-diligence metrics should investors prioritize when evaluating an Online Food Delivery Market operator?
Contribution profit per order and courier cost per delivery matter more than gross order value. Order frequency by cohort age reveals whether growth comes from retained users or paid acquisition [17].
How should a restaurant chain decide between aggregator listing and building its own ordering app?
Chains with over roughly 50 locations and existing brand recall usually recover app development costs within two years through commission savings. Smaller operators rarely generate the traffic to justify it [18].
What integration challenges arise when connecting restaurant point-of-sale systems to Online Food Delivery Market platforms?
Menu synchronization failures and stock-out mismatches cause most order errors. Middleware layers that normalize item identifiers across platforms reduce cancellation rates significantly compared with manual tablet management [4].
How do commission caps change platform behaviour in affected jurisdictions?
Operators shift revenue to consumer-side service fees, advertising placements, and subscription pricing. Restaurant selection typically narrows as platforms reduce onboarding investment in capped cities [16].
What differentiates quick-commerce fulfilment from traditional Online Food Delivery Market fulfilment?
Instant retail depends on owned inventory in dark stores, whereas restaurant delivery relies on third-party kitchens producing to order. The capital and working-capital profiles differ substantially [7].
Which regulatory developments most affect cross-border expansion planning?
Courier employment classification rules set the cost base and vary sharply between jurisdictions. Data localization requirements in India and several Gulf states additionally constrain shared technology infrastructure [19].
How are platforms in the Online Food Delivery Market monetizing beyond delivery commissions?
Advertising consoles, subscription memberships, and white-label logistics sold to non-restaurant retailers now supply a growing share of gross profit. These lines carry materially higher margins than fulfilment [13].
List of Tables
Table 1: Global Online Food Delivery Market Size & Forecast, by Revenue (USD Billion), 2021–2035 Table 2: Global Online Food Delivery Market – Year-over-Year Growth Analysis, 2021–2035 Table 3: Driver Impact Analysis – Online Food Delivery Market, 2026–2035 Table 4: Restraint Impact Analysis – Online Food Delivery Market, 2026–2035 Table 5: Global Online Food Delivery Market Size, by Region, 2021–2035 (USD Billion) Table 6: North America Online Food Delivery Market Size, by Country, 2021–2035 (USD Billion) Table 7: Europe Online Food Delivery Market Size, by Country, 2021–2035 (USD Billion) Table 8: Asia-Pacific Online Food Delivery Market Size, by Country, 2021–2035 (USD Billion) Table 9: South America Online Food Delivery Market Size, by Country, 2021–2035 (USD Billion) Table 10: Middle East & Africa Online Food Delivery Market Size, by Country, 2021–2035 (USD Billion) Table 11: Global Online Food Delivery Market Size, by Business Model, 2021–2035 (USD Billion) Table 12: Global Online Food Delivery Market Size, by Service Type, 2021–2035 (USD Billion) Table 13: Global Online Food Delivery Market Size, by Payment Mode, 2021–2035 (USD Billion) Table 14: Global Online Food Delivery Market Size, by Platform, 2021–2035 (USD Billion) Table 15: Competitive Benchmarking Matrix – Online Food Delivery Market, 2026 Table 16: Company Profiles – Key Players, Online Food Delivery Market Table 17: Recent Developments & Strategic Announcements, 2023–2025 Table 18: Report Scope & Methodology Summary Table 19: Detailed Sources and Citations Index Table 20: Segmentation Quick Reference – Dominant and Fastest-Growing Segments
List of Figures
Figure 1: Online Food Delivery Market Dynamics – Drivers, Restraints, and Opportunities Figure 2: Industry Value Chain Analysis – Online Food Delivery Market Figure 3: Porter's Five Forces Analysis – Online Food Delivery Market Figure 4: Global Market Size Trend and Forecast, 2021–2035 (USD Billion) Figure 5: Year-over-Year Growth Rate Trend, 2022–2035 (%) Figure 6: Market Share by Business Model, 2025 vs 2035 (%) Figure 7: Market Share by Service Type, 2025 (%) Figure 8: Market Share by Payment Mode, 2025 (%) Figure 9: Market Share by Platform, 2025 (%) Figure 10: Regional Revenue Share, 2025 (%) Figure 11: Regional CAGR Comparison, 2026–2035 (%) Figure 12: Country-Level Revenue Contribution – Asia-Pacific, 2025 (%) Figure 13: Competitive Landscape – Estimated Revenue Share Ranges, 2026 Figure 14: Strategic Positioning Matrix – Leading Operators
Author
Author Author Profile Aarti Dhapte LinkedIn AVP - Research
A consulting professional focused on helping businesses navigate complex markets through structured research and strategic insights. I partner with clients to solve high-impact business problems across market entry strategy, competitive intelligence, and opportunity assessment. Over the course of my experience, I have led and contributed to 100+ market research and consulting engagements, delivering insights across multiple industries and geographies, and supporting strategic decisions linked to $500M+ market opportunities. My core expertise lies in building robust market sizing, forecasting, and commercial models (top-down and bottom-up), alongside deep-dive competitive and industry analysis. I have played a key role in shaping go-to-market strategies, investment cases, and growth roadmaps, enabling clients to make confident, data-backed decisions in dynamic markets.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of regulatory databases, industry association reports, peer-reviewed publications, government statistics, and authoritative market intelligence sources. Key sources included:

Government & Regulatory Bodies:

US Department of Agriculture (USDA) - Food and Nutrition Service

US Food and Drug Administration (FDA) - Food Code and retail food protection

European Food Safety Authority (EFSA)

UK Food Standards Agency (FSA)

National Restaurant Association (NRA) - US foodservice industry statistics

Bureau of Labor Statistics (BLS) - Consumer Expenditure Surveys

US Census Bureau - Retail Trade and Food Services data

Eurostat - Digital Economy and Society Statistics

National Bureau of Statistics of China

Ministry of Commerce (MOFCOM) - China

Reserve Bank of India - Digital payment statistics

Industry Associations & Trade Organizations:

International Foodservice Manufacturers Association (IFMA)

Foodservice Equipment & Supplies (FES) Magazine

National Association of Convenience Stores (NACS)

Grocery Manufacturers Association (GMA)

Food Marketing Institute (FMI)

International Association of Meal Kit Delivery Services

National Retail Federation (NRF)

International Franchise Association (IFA)

Financial & Payment Systems:

World Bank Global Payment Systems Survey

Payment Card Industry Security Standards Council (PCI SSC)

International Monetary Fund (IMF) Financial Access Survey

Bank for International Settlements (BIS) - Payment and settlement statistics

Technology & Digital Economy:

International Telecommunication Union (ITU) - Internet usage statistics

GSMA Intelligence - Mobile connectivity data

World Economic Forum (WEF) - Digital transformation reports

OECD Digital Economy Outlook

Market Intelligence Databases:

Euromonitor International - Consumer Foodservice data

Statista - Digital Food Delivery statistics

IBISWorld - Online Food Ordering and Delivery industry reports

NPD Group / Circana - Foodservice market research

These sources were utilized to collect market sizing data, regulatory compliance frameworks, digital payment adoption trends, consumer expenditure patterns, restaurant industry performance metrics, grocery e-commerce penetration rates, and competitive landscape analysis across restaurant delivery, grocery delivery, meal kit delivery, and catering services segments.


Primary Research

In order to gather both qualitative and quantitative insights, supply-side and demand-side stakeholders were interviewed during the primary research process. CEOs, CTOs, VPs of Operations, heads of merchant relationships, and regional general managers from supermarket delivery services, meal kit firms, online food delivery platforms, and restaurant aggregators were examples of supply-side sources. Quick-service restaurants (QSRs), casual dining chains, supermarket retailers, cloud kitchen operators, franchise development managers, and procurement directors of grocery chains were examples of demand-side sources. Primary research obtained information on customer acquisition costs, delivery logistics optimization, subscription model performance, and payment infrastructure investments. It also verified technology roadmap deadlines and validated market segmentation across service types and order types.

Primary Respondent Breakdown:

By Company Tier:

Tier 1 (>USD 10B revenue): 38%

Tier 2 (USD 1B-10B revenue): 32%

By Designation:

C-level Executives (CEOs, CFOs, CTOs, CMOs): 30%

Director Level (Directors, VPs, Regional Heads): 35%

Senior Managers and Subject Matter Experts: 35%

By Region:

North America: 32%

Europe: 28%

Asia-Pacific: 33%

Rest of World (Latin America, Middle East & Africa): 7%

By Stakeholder Type:

Platform Operators (Aggregators/Delivery Apps): 40%

Restaurant and Foodservice Operators: 25%

Grocery and Retail Chains: 20%

Technology and Logistics Providers: 15%


Market Size Estimation

Global market valuation was derived through revenue mapping and transaction volume analysis. The methodology included:

Identification of 50+ key platform operators and service providers across North America, Europe, Asia-Pacific, Latin America, and Middle East & Africa

Product mapping across restaurant delivery, grocery delivery, meal kit delivery, and catering services segments

Analysis of reported and modeled annual revenues specific to food delivery operations, including commission fees, delivery charges, and subscription revenues

Coverage of platforms representing 75-80% of global market share in 2024

Extrapolation using bottom-up (GMV/GTV × take-rate by country) and top-down (platform revenue validation) approaches to derive segment-specific valuations

Cross-verification with transaction volume data from payment processors and industry associations

Data Triangulation and Validation

Market estimates were validated through:

Cross-referencing secondary data with primary interview insights

Comparison with publicly disclosed financial filings of major platforms (Uber Technologies, DoorDash, Just Eat Takeaway, Delivery Hero, Zomato)

Validation against investor presentations and earnings call transcripts

Calibration using alternative data sources including app download statistics, web traffic analytics, and social media sentiment analysis

Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.

















