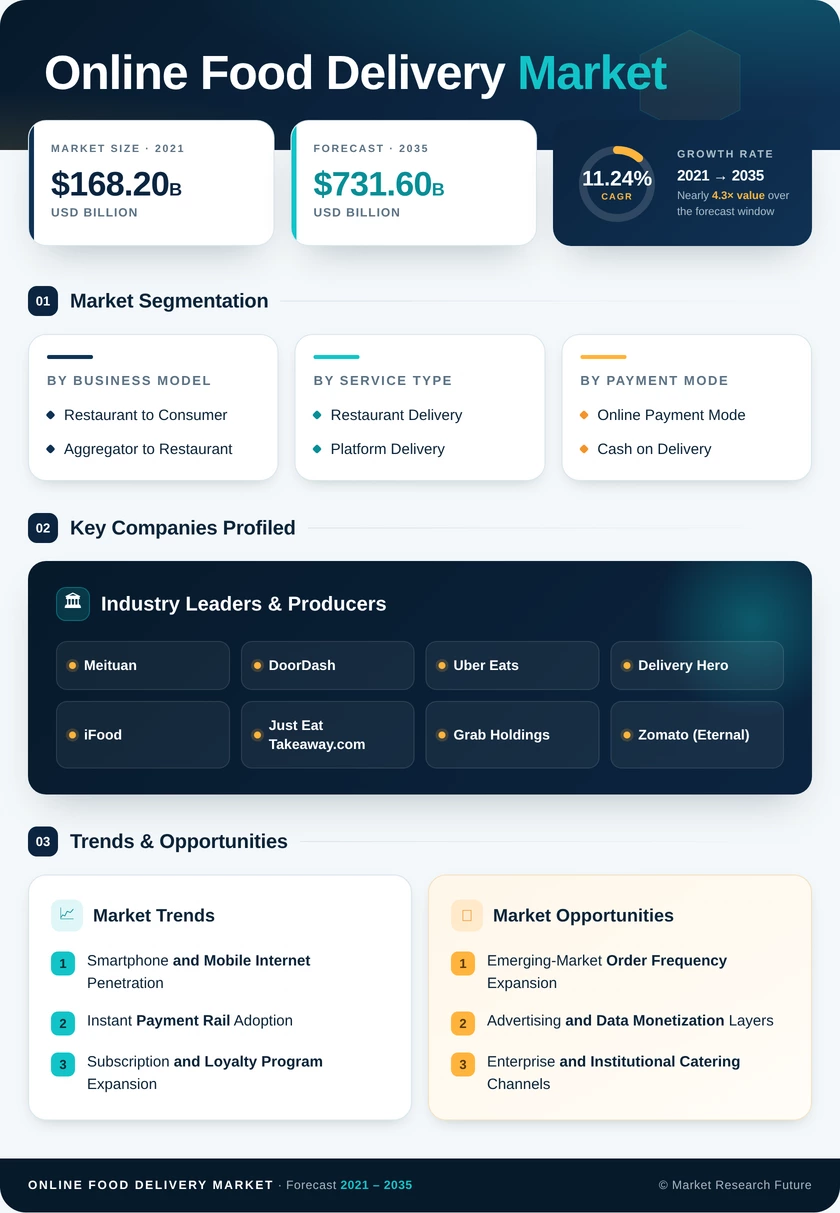
Market Segmentation Analysis
By Business Model
9.1.1 Restaurant to Consumer
9.1.2 Aggregator to Restaurant
By Service Type
9.2.1 Restaurant Delivery
9.2.2 Platform Delivery
By Payment Mode
9.3.1 Online Payment Mode
9.3.2 Cash on Delivery
By Platform
9.4.1 Mobile/Tablet Applications
9.4.2 Desktop/Web
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| By Business Model | Restaurant to Consumer; Aggregator to Restaurant | Restaurant to Consumer (73.1% share, 2025) | Aggregator to Restaurant (12.44% CAGR) |
| By Service Type | Restaurant Delivery; Platform Delivery | Restaurant Delivery (USD 105.10 Billion, 2025) | Platform Delivery (13.29% CAGR) |
| By Payment Mode | Online Payment Mode; Cash on Delivery | Online Payment Mode (71.6% share, 2025) | Cash on Delivery (13.81% CAGR) |
| By Platform | Mobile/Tablet Applications; Desktop/Web | Mobile/Tablet Applications (USD 231.00 Billion, 2025) | Desktop/Web (12.79% CAGR) |
Market Segmentation Overview
By Business Model
| Sub-Segment | Key Trend |
| Restaurant to Consumer | Chain-owned apps embed loyalty tiers and first-party data capture to bypass commissions. |
| Aggregator to Restaurant | Subscription bundles and courier network scale draw independent restaurants onto shared platforms. |
Restaurant to Consumer holds the larger position because national chains with existing brand recall can drive app downloads without paid discovery, then retain the full order margin that aggregator commissions would otherwise consume. Aggregator to Restaurant grows more quickly since independent and mid-sized restaurants gain immediate delivery capability and multi-neighbourhood reach without buying vehicles or hiring couriers. Regulatory commission caps in several US and Canadian cities narrow the cost gap between the two models, but they have not reversed the direction of travel.
By Service Type
| Sub-Segment | Key Trend |
| Restaurant Delivery | Pizza and quick-service chains retain in-house fleets for quality and timing control. |
| Platform Delivery | Aggregator courier density enables sub-30-minute guarantees across dense urban zones. |
Restaurant Delivery remains the larger revenue base, anchored by pizza and quick-service operators whose in-house fleets predate digital platforms and whose delivery timing is central to product quality. Platform Delivery expands faster because consumers now sort by estimated arrival time, and only aggregator courier pools carry enough density to compress that number reliably. Municipal courier classification rules raise the cost of platform fleets in Europe, which partially slows conversion in those specific jurisdictions.
By Payment Mode
| Sub-Segment | Key Trend |
| Online Payment Mode | Instant rails and stored credentials enable one-tap reorder and subscription billing |
| Cash on Delivery | Platforms retain cash acceptance to reach consumers without bank accounts or cards |
Online Payment Mode carries the dominant share of transaction value because stored credentials remove checkout friction and make recurring subscription charges possible, which is the mechanism behind rising order frequency in developed markets. Cash on Delivery records the faster growth rate, since smartphone ownership across Africa, South Asia, and parts of Southeast Asia is outrunning banking access. Platforms that drop cash acceptance in these geographies lose measurable order volume, so most maintain hybrid checkout.
By Platform
| Sub-Segment | Key Trend |
| Mobile/Tablet Applications | Location services, push notifications, and one-tap reorder drive impulse conversion |
| Desktop/Web | Larger screens support corporate catering, group assembly, and bulk order comparison |
Mobile/Tablet Applications dominate order volume because the device is always within reach, GPS removes address entry, and push notifications create demand rather than merely serving it. Desktop/Web grows faster from a much smaller base, driven by institutional buyers assembling multi-person orders where side-by-side menu comparison and expense-code entry are impractical on a phone. Corporate catering procurement teams in particular default to web interfaces, which keeps that channel structurally relevant despite low consumer share.

 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA