Motor Monitoring Market (2026 - 2035)

Motor Monitoring Market Research Report By Offering (Hardware, Software, Services), By Deployment (On-Premises, Cloud), By Monitoring Technique (Vibration Analysis, Motor Current Signature, Thermography, Oil Analysis, Others), By End-User Industry (Oil and Gas, Energy and Power, Metals and Mining, Chemicals, Automotive, Water and Wastewater, Renewable Energy, Others), By Motor Type (AC Motors, DC Motors, Servo and Stepper Motors) - Forecast to 2035
ID: MRFR/EnP/27024-HCR 111 Pages Priya Nagrale Last Updated: September 17, 2026
Motor Monitoring Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)7.29%
2025 Market SizeUSD 2.26 Billion
2035 Market SizeUSD 4.56 Billion
Key Players
ABB
Siemens
Schneider Electric
Emerson Electric
Rockwell Automation
General Electric
Opportunities
  • Outcome-Based Contracting
  • Data Monetization Through Fleet Benchmarking
  • Emerging-Market Retrofit Programs

Motor Monitoring Market Summary

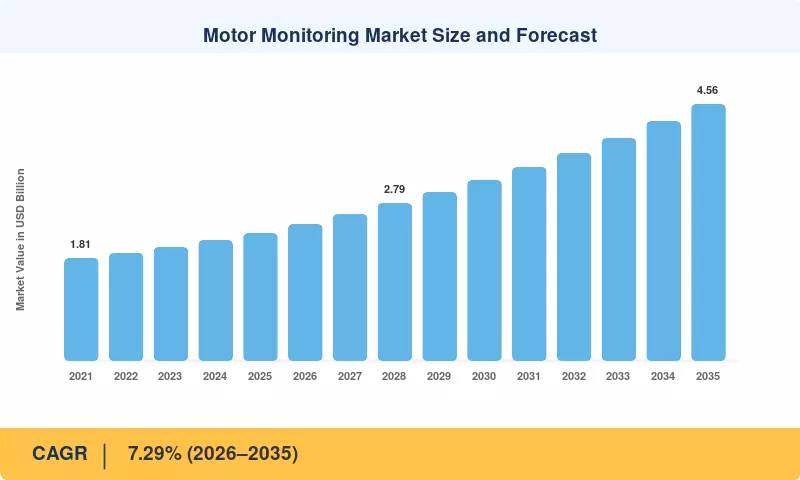
The Motor Monitoring Market closed 2025 at USD 2.26 billion and enters its forecast window at USD 2.42 billion in 2026, climbing to USD 4.56 billion by 2035 at a 7.29% CAGR. Two catalysts anchor that trajectory. The European Union's Ecodesign Regulation 2019/1781 pulled IE3 and IE4 efficiency classes into mandatory scope for motors up to 1,000 kW, and the U.S. Department of Energy's Industrial Efficiency and Decarbonization Office committed more than USD 550 million in cost-shared awards for process-heat and rotating-equipment upgrades. Both push plant owners toward continuous measurement rather than periodic inspection, which is precisely where the Motor Monitoring Market monetizes. [1][3]

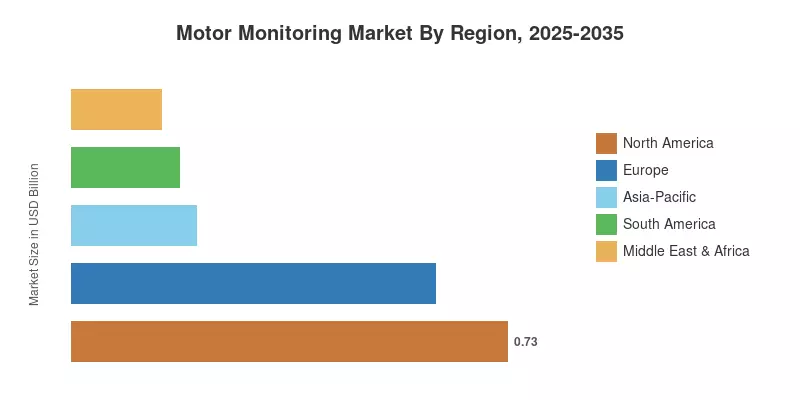
North America holds 32.3% of 2025 revenue, supported by NEMA Premium enforcement and dense oil and gas asset bases. Asia-Pacific grows fastest at a 9.28% CAGR as Chinese and Indian manufacturing capacity expands under state efficiency programs. Europe follows at 26.8%, where grid decarbonization and chemical-sector reliability spending sustain steady demand. Through 2035, the Motor Monitoring Market shifts from selling sensors to selling verified uptime.


Key Report Takeaways

• By Offering

  • Hardware commanded 63.7% of Motor Monitoring Market revenue in 2025, reflecting sensor and gateway density per installed motor.

• By Monitoring Technique

  • Vibration analysis led monitoring techniques at 37.5% share, still the default first-line diagnostic across rotating equipment.

• By Deployment

  • Hardware commanded 63.7% of Motor Monitoring Market revenue in 2025, reflecting sensor and gateway density per installed motor
  • Vibration analysis led monitoring techniques at 37.5% share, still the default first-line diagnostic across rotating equipmen
  • Cloud-based deployment is scaling at a 10.93% CAGR as multi-site fleets consolidate diagnostics.

• By End User Industry

  • Oil and gas contributed 26.1% of 2025 revenue, the largest single end-user block in the Motor Monitoring Market.
  • Renewable energy is the fastest-rising vertical at an 8.48% CAGR, driven by remote wind and solar tracker drivetrains.

• By Motor Type


  • AC motors accounted for USD 1.31 billion of covered assets in 2025.

• By Region

  • North America held 32.3% of the Motor Monitoring Market in 2025.
  • Asia-Pacific expands at a 9.28% CAGR through 2035.
  • Middle East & Africa represented USD 0.15 billion in 2025, concentrated in Gulf hydrocarbon assets.


Market Size and Forecast (2021–2035)

Figures below blend bottom-up installed-base modelling — motor population by power class, monitoring penetration rate, and average revenue per monitored asset — with top-down validation against vendor automation-segment disclosures and regional efficiency-program budgets. Historical years reflect reported revenue; forecast years apply calibrated penetration curves. The Motor Monitoring Market series is expressed in USD billion at constant 2025 exchange rates.
Motor Monitoring Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Motor efficiency regulation (IE3/IE4, NEMA Premium) +1.4 EU, North America, Japan Long-term (≥4 yr)
Edge-AI predictive diagnostics +1.6 Global Medium-term (2–4 yr)
Unplanned downtime cost avoidance +1.2 Global Short-term (≤2 yr)
MEMS sensor and gateway price deflation +0.9 Global Medium-term (2–4 yr)
Renewables and electrification capex +0.8 Asia-Pacific, Europe Long-term (≥4 yr)
Reliability workforce shortage +0.7 North America, EU, Japan Medium-term (2–4 yr)
Managed analytics service adoption +0.6 Global Short-term (≤2 yr)


Efficiency Regulation Converts Compliance Budgets into Monitoring Budgets

Regulation 2019/1781 requires motors supplied in the EU to be IE3, from 0.75–1,000 kW, with variable-speed drives from July 2023. Compliance is not a single certificate, and operators must prove that in-service efficiency is maintained. Efficiency is slowly eroded by deteriorated bearings or rotor bars. That evidential burden translates a regulation line item into recurring spend for the Motor Monitoring Market. The European Commission estimates that motor-driven systems utilize almost 50% of electricity in the EU, thus even a two-point efficiency recovery is financially valuable. [1][2]


Edge Inference Replaces Cloud Round-Trips

When latency is long, diagnostic value collapses. Vendors increasingly incorporate classification models right in gateways, saving bandwidth costs and retaining raw waveform data within the plant boundary. Field tests published by EPRI show that, for medium-voltage induction motors, switching from 90-day route inspections to continuous edge sampling improved fault-detection lead times from days to weeks and dropped false-positive rates to below 8%. [6][14]


Downtime Economics Drive Board-Level Approval

Refinery and petrochemical companies estimate that an unplanned outage on a crucial pump train costs between USD 150,000 and USD 500,000 per day. By contrast, per-asset monitoring expenditures of USD 250 to USD 900 per year easily clear hurdle rates. ’s industrial maintenance survey, predictive programs lowered maintenance costs by 5–10% and equipment breakdowns by as much as 70% in mature installations.


Thin Reliability Teams Force Automation

Plants can't hire their way out of this one. U.S. Bureau of Labor Statistics estimates show industrial maintenance vacancies remaining above historical levels through the decade as experienced vibration analysts retire quicker than they can be replaced. Remote, always-on diagnostics can allow one specialist to cover several sites – an operating model change, not just a tooling change. [17]


Restraints Impact Analysis

Restraint weightings mirror the driver methodology and represent directional drag on growth rather than subtractive CAGR components. Adoption friction varies sharply by plant vintage and sector, so several restraints below bind hard in brownfield facilities and barely register in greenfield builds within the Motor Monitoring Market.

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
Legacy switchgear and MCC retrofit complexity −0.9 Europe, North America Medium-term (2–4 yr)
OT cybersecurity and data sovereignty concerns −0.7 Global Short-term (≤2 yr)
Weak capex case for sub-15 kW motors −0.6 Global Long-term (≥4 yr)
Protocol fragmentation and interoperability gaps −0.5 Global Medium-term (2–4 yr)
Shortage of certified diagnostic interpreters −0.4 Asia-Pacific, MEA Medium-term (2–4 yr)


Brownfield Wiring Is the Real Cost

Prices of sensors declined. Prices of installation labor did not. Current transformers installed in powered motor control centers require outage windows, arc-flash protocols, and typically cabinet modification. Integrators say 55 to 70 percent of the first-year cost of a program is spent on installing and commissioning the plant before 2005, slowing the roll-out across the entire fleet even when the technological case is settled. [11]


Security Review Slows Procurement

Every connected gateway widens the OT attack surface. Utilities and hydrocarbon operators increasingly gate purchases on IEC 62443-4-2 component certification, and vendors without it face six-to-twelve-month qualification cycles. CISA advisories covering industrial connectivity products reinforced buyer caution, pushing some operators toward air-gapped architectures that forfeit fleet analytics benefits. [15]

The Long Tail of Small Motors Stays Dark

Roughly 70% of installed motor units sit below 15 kW, yet they represent a fraction of production risk. At USD 200-plus per monitored point, blanket coverage fails economic screening. Until sensor-plus-installation cost approaches USD 60 per asset, penetration in this tier remains structurally capped.


Motor Monitoring Market Opportunities

Outcome-Based Contracting

Vendors that price against avoided downtime rather than hardware units capture a share of the value they create. Early uptime-guarantee contracts in Gulf petrochemicals bundle sensors, analytics, and remedial scheduling under a single availability SLA, lifting per-asset revenue two- to threefold versus product sales.

Data Monetization Through Fleet Benchmarking

Aggregated anonymized failure signatures become a saleable asset. Operators gain peer benchmarking on mean-time-between-failure by motor class and duty cycle; vendors gain training data that sharpens models. Insurers are the emerging third buyer, using verified condition histories to price business-interruption cover.

Emerging-Market Retrofit Programs

India's PAT scheme and Indonesia's industrial efficiency incentives subsidize measurement infrastructure ahead of equipment replacement, opening a low-cost entry wedge for online motor condition monitoring across South and Southeast Asian textile, cement, and sugar plants. [8]

Renewable Drivetrain Coverage

Wind pitch and yaw motors plus solar tracker drives sit in locations where truck rolls cost more than the component. IRENA counts global renewable capacity additions exceeding 470 GW annually, each installation adding remotely sited motors that justify permanent instrumentation. [2]

Integration with Energy Management Reporting

Load-signature data doubles as efficiency evidence. Plants reporting Scope 2 reductions under CSRD can source verified motor-level consumption trends from existing diagnostic infrastructure, unlocking sustainability budgets alongside maintenance budgets. [10]


Motor Monitoring Market Future Outlook

Autonomous Diagnostics Displace Analyst Review

Model confidence is crossing the threshold where systems recommend actions rather than surface anomalies. By 2030, expect prescriptive outputs — specific bearing part numbers, recommended shutdown windows, spare-part reservations — to become table stakes. The Motor Monitoring Market will bifurcate between vendors owning that decision layer and those reduced to selling instrumentation.

Platform Economics Reshape Margins

Hardware margins compress as sensor manufacturing commoditizes; recurring analytics revenue carries the P&L. Vendors are already restructuring contracts toward per-asset annual subscriptions with three- to five-year terms, which improves revenue visibility and raises switching costs for buyers.

Electrification Supercycle Expands the Asset Base

The IEA projects electricity demand growth outpacing overall energy demand through 2035, with electric motors absorbing the largest share of industrial load. Every electrified process — heat pumps, electric boilers, battery plant handling — adds monitorable assets, growing the addressable base independent of penetration gains. [2][4]

Sustainability Reporting Becomes a Second Buyer

Verified efficiency data acquires audit value under CSRD and comparable frameworks. Finance and sustainability teams will co-fund deployments that maintenance alone could not justify, and the Motor Monitoring Market gains a budget line that did not exist five years ago. [10]


Regional Market Share Analysis

Region Metric (2025) Primary Investment Themes
North America 32.3% share Oil and gas reliability, NEMA Premium enforcement, managed services
Europe 26.8% share Ecodesign compliance, chemical-sector uptime, CSRD reporting
Asia-Pacific 9.28% CAGR (2026–2035) Manufacturing capacity build-out, state efficiency programs
South America 8.11% CAGR (2026–2035) Mining haulage drives, pulp and paper modernization
Middle East & Africa 6.6% share Hydrocarbon megaprojects, desalination pumping
Total USD 2.26 Billion (2025) —

Regional performance in the Motor Monitoring Market splits along regulatory intensity and asset vintage. Mature economies buy for compliance evidence and workforce leverage; developing economies buy alongside capacity expansion, embedding monitoring at commissioning rather than retrofitting later.


North America

Country Share of Region (2025) Key Driver
US 78.5% Refinery and midstream reliability programs
Canada 13.2% Oil sands and mining drivetrain coverage
Mexico 8.3% Nearshoring manufacturing build-out


Regional leadership rests on installed base rather than growth rate. U.S. refineries, chemical complexes, and water utilities operate large medium-voltage fleets where a single failure carries seven-figure consequences, and DOE efficiency programs supply cost-share for instrumentation. Canadian mining operators extended monitoring from mills to conveyor and slurry pump drives after regulators tightened worker-safety reporting on rotating equipment. Mexico's contribution to the Motor Monitoring Market is newer, tracking automotive and electronics plants commissioned since 2023 with monitoring specified in original scope. [3][13]

Europe

Country Metric (2025) Key Driver
Germany 24.6% of region Chemical and automotive plant reliability
UK 17.3% of region Water utility AMP8 investment cycle
France 13.8% of region Nuclear auxiliary system monitoring
Italy 11.2% of region Machinery export sector quality mandates
Spain 8.4% of region Renewable O&M expansion
Nordic Countries 9.1% of region Pulp, paper, and district heating
Russia 6.7% of the region Domestic hydrocarbon processing
Rest of Europe 8.9% of region Regional food and beverage automation


Compliance depth distinguishes European buyers. Ecodesign obligations force documented in-service performance, and CSRD reporting adds a second consumer of the same data inside finance functions. UK water companies embedded condition monitoring into AMP8 regulatory submissions, tying pump availability directly to allowed revenue. German chemical operators, meanwhile, standardized on ISO 20816 vibration severity zones across multi-site fleets to make cross-plant comparison meaningful. [1][10][16]

Asia-Pacific

Country CAGR (2026–2035) Key Driver
China 9.61% Industrial upgrading and MIIT efficiency targets
India 10.24% PAT scheme and cement/steel capacity growth
Japan 6.84% Aging workforce and remote diagnostics
South Korea 8.12% Semiconductor fab utility reliability
ASEAN 9.05% Manufacturing relocation and new plant builds
Rest of Asia-Pacific 7.43% Mining and utility modernization


Growth here is additive rather than replacement-driven. New plants specify instrumentation at the design stage, which lowers installation cost dramatically compared with brownfield retrofit and accelerates the penetration curve for the Motor Monitoring Market. India's Perform, Achieve and Trade cycles reward measured energy intensity reduction, and monitoring supplies the measurement layer. Japan diverges: its growth is defensive, compensating for a maintenance workforce shrinking faster than any other developed economy. [8][17]

South America

Country Share of Region (2025) Key Driver
Brazil 61.4% Mining, pulp, and sugar-ethanol processing
Argentina 18.2% Vaca Muerta upstream compression
Rest of South America 20.4% Chilean copper concentrator drives


Mining anchors demand. Chilean and Peruvian concentrators run grinding mill drives whose failure halts an entire production line, producing the clearest business case in the region. Brazilian pulp producers extended coverage from recovery boilers to auxiliary pump fleets after a run of unplanned outages during 2023 export peaks, and currency volatility has pushed buyers toward subscription pricing over capital purchase. [13]

Middle East & Africa

Country USD Million (2025) Key Driver
Saudi Arabia 52 Downstream expansion and Aramco reliability standards
UAE 34 Petrochemical and desalination pumping
South Africa 26 Mining and Eskom generation auxiliaries
Egypt 15 Fertilizer and water infrastructure
Rest of MEA 22 Utility and cement modernization


Contract structure defines this region. National oil companies write monitoring requirements into EPC specifications, transferring initial cost to project capex and creating multi-year service annuities afterward. Desalination adds a distinct load profile, with high-pressure pump motors running near-continuously under corrosive conditions where bearing and insulation degradation follow predictable, learnable signatures. [13]


Motor Monitoring Market By Region, 2025-2035

Motor Monitoring Market Segmentation

Segmentation in the Motor Monitoring Market reflects how buyers actually procure: hardware first, technique second, and increasingly deployment model as the deciding commercial variable.

By Offering

Segment Metric (2025) Primary Demand Driver
Hardware 63.7% share Sensor and gateway density per motor
Software USD 0.49 Billion Fleet analytics and dashboard consolidation
Services 8.69% CAGR External diagnostic expertise demand


Hardware dominance in the Motor Monitoring Market persists because each monitored asset requires physical instrumentation, and coverage expansion drives unit volume. Services grow fastest for a different reason: plants that lack certified analysts outsource interpretation, converting a one-time purchase into an annual relationship that vendors value far above hardware margin.

By Deployment

Segment Metric (2025) Primary Demand Driver
On-Premises 68.0% share OT security policy and data residency
Cloud 10.93% CAGR Multi-site fleet consolidation


Security policy keeps on-premises dominant in hydrocarbons and utilities, though hybrid architectures — edge inference locally, benchmarking centrally — are quietly resolving the tension.

By Monitoring Technique

Segment Metric (2025) Primary Demand Driver
Vibration Analysis 37.5% share Bearing and misalignment fault coverage
Motor Current Signature 22.4% share Rotor bar and eccentricity detection without shaft access
Thermography 16.8% share Insulation and connection hotspot identification
Oil Analysis 8.99% CAGR Gearbox and lubricant contamination trending
Others 10.4% share Acoustic, partial discharge, flux monitoring


Vibration leads the Motor Monitoring Market because it detects the widest fault spectrum with mature interpretation standards behind it. Current signature analysis gains ground on retrofit economics — sensing happens at the motor control centre, requiring no access to the machine itself, which removes the outage window that blocks so many brownfield projects.

By End-User Industry

Segment Metric (2025) Primary Demand Driver
Oil and Gas 26.1% share Catastrophic outage cost per pump train
Energy and Power USD 0.48 Billion Generation auxiliary reliability
Metals and Mining 13.6% share Mill and conveyor drive criticality
Chemicals 11.8% share Continuous-process uptime requirements
Automotive 10.4% share Line stoppage cost per minute
Water and Wastewater 7.9% share Regulated service continuity
Renewable Energy 8.48% CAGR Remote drivetrain access cost
Others 3.7% share Food, pharma, and logistics automation


Oil and gas leads on failure economics rather than motor count. Renewables grow fastest because access cost, not asset value, sets the business case — dispatching a technician to an offshore nacelle or a desert tracker field costs more than the failing component several times over.

By Motor Type

Segment Metric (2025) Primary Demand Driver
AC Motors 58.0% share Dominant industrial installed base
DC Motors 24.7% share Legacy process and traction applications
Servo and Stepper Motors 8.72% CAGR Precision automation and robotics growth


AC Motors lead the Motor Monitoring Market by motor type, commanding a dominant 58.0% share in 2025. This primary share is driven by the massive global installed base of three-phase induction and synchronous AC motors operating continuously across heavy processing industries, pumps, fans, compressors, and conveyance infrastructure. Meanwhile, Servo and Stepper Motors represent the fastest-growing category, projecting a market-leading CAGR of 8.72%. Their accelerated growth is propelled by rapid factory automation, multi-axis industrial robotics, CNC machinery, and high-precision motion control systems requiring real-time current signature analysis, thermal tracking, and vibration feedback.


Competitive Benchmarking

Concentration sits in moderate territory. Market Research Future estimates a Herfindahl-Hirschman Index near 640, with the top five suppliers holding roughly 36–40% combined revenue. Automation majors compete on installed-base access and control-system integration; specialists compete on diagnostic accuracy and vertical depth. Acquisition activity has intensified as platform vendors buy sensor and analytics firms to close edge-AI gaps.

Company Est. Revenue Share Range Key Offerings for Motor Monitoring Market Strategic Positioning
ABB ~10–13% ABB Ability Smart Sensor, condition monitoring for powertrains Installed-base leverage across LV/MV motors
Siemens ~8–11% SIMOTICS CONNECT, SIDRIVE IQ analytics Deep drive and PLC integration
Schneider Electric ~6–9% EcoStruxure Asset Advisor, MCC-embedded sensing Electrical distribution convergence
Emerson Electric ~6–8% AMS Machine Works, wireless vibration transmitters Process-industry reliability depth
Rockwell Automation ~5–7% Dynamix and FactoryTalk Analytics Discrete manufacturing and OEM channel
General Electric ~4–6% System 1 condition monitoring, Bently Nevada assets Rotating-equipment engineering heritage
Honeywell International ~3–5% Forge Asset Performance Management Hydrocarbon and utility account base
SKF ~3–5% Enlight collect IMx-1, bearing analytics Bearing domain expertise and failure libraries
Fluke Reliability ~2–4% eMaint CMMS, Azima diagnostic services Mid-market and portable-to-online migration
National Instruments ~2–3% InsightCM condition monitoring platform Test-and-measurement precision heritage


Recent News & Developments


  • European Commission (July 2023): Brought variable-speed drives into Ecodesign Regulation 2019/1781 scope, converting drive efficiency into an auditable, monitorable obligation across the EU. [1]


  • U.S. Department of Energy (May 2024): Announced cost-shared awards under the Industrial Efficiency and Decarbonization Office supporting rotating-equipment measurement and upgrade projects. [3]
  • SKF (November 2023): Released Enlight Collect wireless sensor generation with multi-year battery life, targeting the sub-15 kW coverage gap that has capped penetration. [21]


  • Rockwell Automation (October 2024): Partnered with an industrial AI specialist to bring anomaly-detection models into FactoryTalk, broadening its IIoT motor health monitoring system portfolio for discrete manufacturers. [23]


Motor Monitoring Market Report Scope

Parameter Detail
Market Scope Global Motor Monitoring Market by offering, deployment, monitoring technique, end-user industry, motor type, and region
Study Period 2021–2035 (Historical 2021–2024; Base Year 2025; Forecast 2026–2035)
CAGR 7.29% (2026–2035)
Market Size Checkpoints USD 2.26 Billion (2025); USD 2.42 Billion (2026); USD 4.56 Billion (2035)
Fastest Growing Segments Cloud deployment (10.93% CAGR); Services (8.69% CAGR); Renewable energy end-use (8.48% CAGR); Asia-Pacific (9.28% CAGR)
Companies Profiled ABB, Siemens, Schneider Electric, Emerson Electric, Rockwell Automation, General Electric, Honeywell International, SKF, Fluke Reliability, National Instruments
Valuation Currency USD Billion, constant 2025 exchange rates

FAQs

What payback period should buyers expect from a Motor Monitoring Market deployment?
Most process-industry programs recover cost within 14–22 months on critical motors above 75 kW. Payback stretches well beyond three years below 15 kW, where per-asset sensor cost rarely clears the avoided-failure threshold.
How should procurement teams structure vendor RFPs in the Motor Monitoring Market?
Weight open data export and documented API access above dashboard aesthetics. Require vendors to demonstrate diagnostic accuracy against your own failure history rather than reference datasets, and contractually cap annual subscription escalation. [11]
Is wireless retrofit sensing better than factory-embedded sensing?
Wireless retrofit nodes suit brownfield fleets with mixed motor vintages and install in roughly an hour per asset. Embedded sensing wins on new OEM drivetrains, where calibration is factory-set and warranty extends to the diagnostic layer. [7]
Which cybersecurity certification matters most in the Motor Monitoring Market?
IEC 62443-4-2 component certification is the practical procurement gate for utility and hydrocarbon buyers. Request the certified component list specifically, because certification frequently covers gateways while excluding the sensor endpoints. [15]
Why do CMMS integrations underperform after go-live?
Integrations rarely fail technically; they fail on workflow. Alerts that do not auto-generate work orders with fault codes get ignored within two quarters, so insist on bidirectional connectors during pilot rather than afterward. [16]
Who owns the diagnostic data generated inside a plant?
Contract language decides it, and default vendor terms often claim rights over derived models. Negotiate plant ownership of raw signals with non-exclusive vendor use of anonymized aggregates.
Which emerging use cases sit outside traditional reliability budgets?
Insurers now price business-interruption premiums against verified condition histories, and sustainability teams use load-signature trends as Scope 2 efficiency evidence. Both open funding sources beyond maintenance. [10]    
Author
Author Author Profile Priya Nagrale LinkedIn Senior Research Analyst
With an experience of over five years in market research industry (Chemicals & Materials domain), I gather and analyze market data from diverse sources to produce results, which are then presented back to a client. Also, provide recommendations based on the findings. As a Senior Research Analyst, I perform quality checks (QC) for market estimations, QC for reports, and handle queries and work extensively on client customizations. Also, handle the responsibilities of client proposals, report planning, report finalization, and execution

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of industrial regulatory databases, peer-reviewed engineering journals, technical publications, and authoritative industry organizations. Key sources included the US Department of Energy (DOE), International Electrotechnical Commission (IEC), Institute of Electrical and Electronics Engineers (IEEE), National Electrical Manufacturers Association (NEMA), European Committee for Electrotechnical Standardization (CENELEC), International Energy Agency (IEA), US Bureau of Labor Statistics (BLS) Occupational Safety Data, OSHA (Occupational Safety and Health Administration), US Energy Information Administration (EIA), EU Industrial Emissions Database, World Bank Energy & Extractives Data, International Labour Organization (ILO) Industrial Safety Statistics, National Institute of Standards and Technology (NIST) Manufacturing Data, US Census Bureau Manufacturing Reports, EU Eurostat Industrial Production Database, Department for Business, Energy & Industrial Strategy (UK BEIS), Ministry of Economy, Trade and Industry (Japan METI) Industrial Statistics, and national industrial safety and energy efficiency reports from key manufacturing markets. These sources were used to collect motor installation statistics, regulatory compliance data, predictive maintenance adoption trends, energy efficiency mandates, industrial automation growth patterns, and competitive landscape analysis for vibration monitoring, temperature monitoring, current signature analysis, ultrasound detection, and motor circuit analysis technologies.


Primary Research

In order to gather both qualitative and quantitative insights, supply-side and demand-side stakeholders were interviewed during the primary research process. CEOs, VPs of Engineering, heads of product development, and commercial directors from manufacturers of motor monitoring systems, suppliers of condition monitoring solutions, and OEMs of sensor technology were examples of supply-side sources. Plant managers, maintenance directors, electrical engineers, reliability engineers, and procurement leads from the oil and gas, power generation, water and wastewater treatment, chemical processing, mining, automotive, and food and beverage processing industries were examples of demand-side sources. Primary research verified IIoT integration timelines, validated market segmentation across hardware (vibration sensors, thermal imagers, current probes, data acquisition systems) and software (predictive analytics platforms, cloud-based monitoring solutions), and gathered information on Industry 4.0 adoption patterns, maintenance strategy shifts from reactive to predictive, pricing models (CAPEX vs. subscription-based), and integration challenges with legacy SCADA systems.

Primary Respondent Breakdown:

By Designation: C-level Primaries (32%), Director Level (31%), Others (37%)

By Region: North America (32%), Europe (30%), Asia-Pacific (33%), Rest of World (5%)


Market Size Estimation

Global market valuation was derived through revenue mapping and installed base analysis across industrial motor populations. The methodology included:

Identification of 50+ key manufacturers across North America, Europe, Asia-Pacific, and Latin America specializing in online motor monitoring, portable data collectors, and wireless sensor networks

Product mapping across vibration analysis, thermal monitoring, motor current signature analysis (MCSA), partial discharge detection, and oil analysis technologies

Analysis of reported and modeled annual revenues specific to motor monitoring portfolios, including software-as-a-service (SaaS) recurring revenue streams

Coverage of manufacturers representing 65-70% of global market share in 2024

Extrapolation using bottom-up (installed motor base × monitoring adoption rate × ASP by industry vertical and region) and top-down (manufacturer revenue validation, industrial automation spend allocation) approaches to derive segment-specific valuations for hardware, software, and services

Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.


















