Torque Actuator Motor Market (2026 - 2035)

Torque Actuator Motor Market Research Report By Type (Electric, Pneumatic, Mechanical), By Motion Output (Linear, Rotary, Electric), By Application (Electronic Throttle Control, Turbocharger Actuation, Exhaust Gas Recirculation (EGR) Valve Actuation, Variable Valve Timing, Others), By Vehicle Type (Passenger Vehicles, Light Commercial Vehicles, Medium and Heavy Commercial Vehicles), By Sales Channel (OEM, Aftermarket) - Forecast to 2035
ID: MRFR/AT/4682-HCR 100 Pages Triveni Bhoyar, Sejal Akre Last Updated: September 24, 2026
Torque Actuator Motor Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)6.70%
2025 Market SizeUSD 10.68 Billion
2035 Market SizeUSD 20.43 Billion
Key Players
Robert Bosch GmbH
Continental AG
Denso Corporation
Hitachi Astemo
Mitsubishi Electric Corporation
Nidec Corporation
Opportunities
  • Thermal Management and Auxiliary Actuation in Electrified Vehicles
  • Localization in India, Brazil and ASEAN
  • Actuator Health Data and Predictive-Maintenance Services

Torque Actuator Motor Market Summary

The Automotive Torque Actuator Motor Market was valued at USD 10.68 billion in 2025. It is projected to reach USD 11.40 billion in 2026 and USD 20.43 billion by 2035, a CAGR of 6.70% over 2026–2035. Two regulatory catalysts support this trajectory. The European Union's Euro 7 Regulation (EU) 2024/1257 extends emission-durability obligations to 10 years or 200,000 km [1]. The U.S. EPA's Phase 3 heavy-duty greenhouse-gas standards cover model years 2027–2032 [3]. Both reward precise, fault-tolerant control of airflow, boost pressure, and exhaust recirculation.

Engine-bay actuation is being rebuilt around electronics. Cable-driven throttles, vacuum-operated wastegates and pneumatic EGR valves are giving way to electronically commanded actuators built on brushless DC motors, integrated position sensing and on-board diagnostics. China's 6b stage has enforced real-driving emissions testing since July 2023 [9]. India's Bharat Stage VI Phase 2 added RDE and tighter OBD thresholds in April 2023 [8]. Both mandates make non-diagnosable mechanical actuation increasingly difficult to certify.

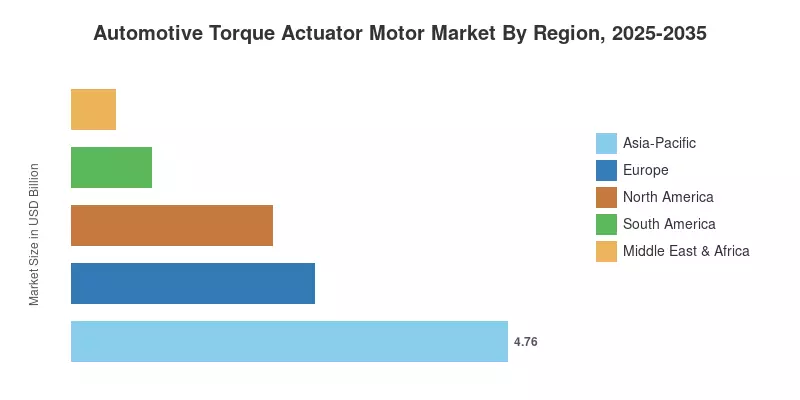
Regionally, Asia-Pacific anchors the Automotive Torque Actuator Motor Market with a 44.6% share, supported by China's production scale and India's rising output. South America is the fastest-growing region at an 8.1% CAGR, as Brazil's PROCONVE L8 phase and the Mover industrial program lift electronic content per vehicle. Europe ranks second, driven by Euro 7 homologation cycles and a large base of turbocharged hybrids. Over the next decade, growth will depend on how quickly suppliers redeploy combustion-actuator expertise into hybrid, thermal-management, and chassis functions.

Key Report Takeaways

• By Type

  • Electric actuators hold a 71.4% share of the Automotive Torque Actuator Motor Market, reflecting universal drive-by-wire adoption and OEM demand for diagnosable designs.
  • Mechanical overlay units grow at a modest 3.9% CAGR as a low-cost transitional option for entry-level engines.

• By Motion Output

  • Rotary actuators account for a 57.3% share, anchored by throttle bodies and turbo vane control.
  • Linear actuators expand at a 6.81% CAGR on precision EGR valve and exhaust-flap demand.

• By Application

  • Electronic Throttle Control leads with a 43.4% share across gasoline and hybrid platforms.
  • Turbocharger Actuation grows at a 6.73% CAGR, supported by variable-geometry turbines and electric boosting.

• By Vehicle Type

  • Passenger Vehicles capture a 60.2% share on high unit volumes and multiple actuators per engine.
  • Light Commercial Vehicles expand at a 6.77% CAGR as last-mile fleets adopt compact 48 V actuators.

• By Sales Channel

  • OEM supply represents an 81.4% share, secured through co-engineering and multiyear platform awards.
  • Aftermarket sales grow at a 6.83% CAGR, the fastest-growing channel in the Automotive Torque Actuator Motor Market.

• By Region

  • Asia-Pacific leads with a 44.6% share on the strength of Chinese and Indian production.
  • South America records the highest regional growth at an 8.1% CAGR.
  • Europe generates USD 2.65 billion in 2025 revenue, driven by Euro 7 compliance programs.

Market Size and Forecast (2021–2035)

Market Research Future sized the Automotive Torque Actuator Motor Market through a bottom-up model that multiplies regional vehicle production by actuator content per powertrain type, cross-checked against supplier segment disclosures, trade data, and interviews with tier-1 purchasing and engineering staff. Historical values reflect reported production and pricing; forecast values incorporate regulatory timelines, powertrain mix scenarios, and aftermarket replacement curves.
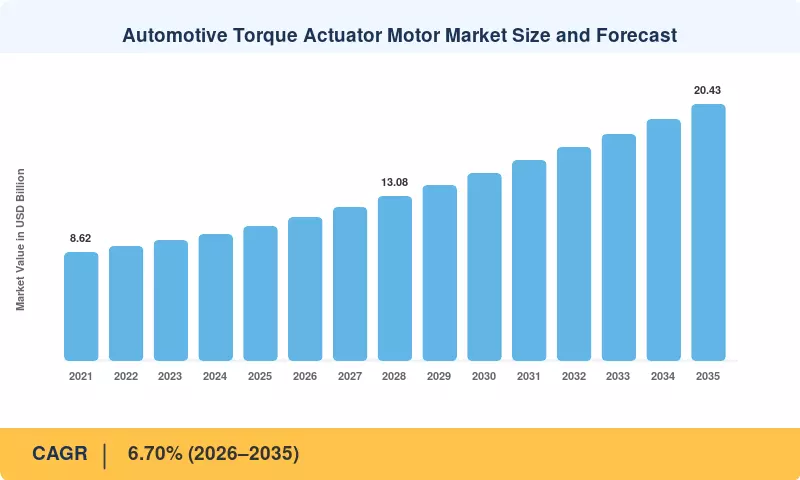
Automotive Torque Actuator Motor Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Emission regulation tightening across major markets ~+1.4% Europe, China, India Medium-term (2–4 yr)
Downsized turbocharged and hybrid powertrains ~+1.1% Global Medium-term (2–4 yr)
Drive-by-wire and 48 V electrical architectures ~+0.9% Europe, North America, China Long-term (≥4 yr)
Heavy-duty greenhouse-gas standards ~+0.7% North America, Europe Long-term (≥4 yr)
Functional-safety and component qualification requirements ~+0.5% Global Short-term (≤2 yr)
Vehicle production growth in emerging economies ~+0.8% Asia-Pacific, South America Short-term (≤2 yr)
Ageing vehicle fleets and replacement demand ~+0.4% North America, Europe Medium-term (2–4 yr)


Emission Regulation Tightening Across Major Markets

Adopted as Regulation (EU) 2024/1257, Euro 7 extends compliance durability to 10 years or 200,000 kilometers and applies to new passenger-car types starting in November 2026 and to all new registrations a year later [1]. Real-driving emissions testing has been mandated by China's 6b stage since July 2023 [9], while India's BS-VI Phase 2 introduced RDE and more stringent OBD standards in April 2023 [8]. Each rule increases the number of actuators needed for EGR, throttle, and exhaust-flap functions, expanding the operating window that an engine must regulate.


Downsized Turbocharged and Hybrid Powertrains

Although sales of electric cars exceeded 17 million in 2024, plug-in and full hybrid vehicles still have combustion engines that require throttle, boost, and EGR management [4]. Many hybrid platforms rely on electric motors and downsized turbocharged engines, and variable-geometry turbines require positional reaction of less than 250 milliseconds at loads of 5–12 Nm. Even as pure combustion output flattens, this profile favors electric turbo actuators over vacuum units, increasing content per vehicle.


Drive-by-Wire and 48 V Electrical Architectures

Mild-hybrid 48 V networks deliver four times the voltage of legacy 12 V systems, cutting current by 75% for the same power and freeing headroom for faster, higher-torque actuators without bulky relays. Digital position feedback over SAE J2716 SENT [18] and dual-channel drivers help suppliers meet ISO 26262 ASIL-C targets for throttle functions [6]. As cable linkages disappear, OEMs specify redundant sensing and limp-home logic that only electronically commanded actuators can provide.

Heavy-Duty Greenhouse-Gas Standards

The EPA's Phase 3 rule, finalized in March 2024, tightens CO2 limits for vocational vehicles and tractors across model years 2027–2032, with the agency estimating roughly 1 billion metric tons of avoided greenhouse-gas emissions through 2055 [3]. Compliance requires precise EGR metering, variable-geometry turbo control, and intake throttling for aftertreatment thermal management. Truck-grade actuators command premium pricing because of extended durability and temperature specifications, raising value per unit well above passenger-car levels.

Functional-Safety and Component Qualification Requirements

Semiconductors used in engine-bay actuators must pass AEC-Q100 Grade 0 qualification, covering operation from −40 °C to 150 °C [7], while ISO 26262 assigns integrity levels up to ASIL-D for functions whose failure could harm occupants [6]. Integrated diagnostics that detect stuck valves, open windings, or sensor drift are now standard OEM requirements. Suppliers with in-house driver ICs and certified development processes win nominations faster, accelerating the retirement of legacy, non-diagnosable actuators.

Vehicle Production Growth in Emerging Economies

Global vehicle production reached roughly 92 million units in 2024, with China alone producing more than 31 million [5]. India, Brazil, Indonesia and Thailand continue to add capacity while moving their emission rules toward Euro 5 and Euro 6 equivalence, which effectively mandates electronic throttle and EGR control. Local assembly lines that once fitted mechanical throttles now source electric actuators, producing volume growth that outpaces mature markets by two to three percentage points annually.

Ageing Vehicle Fleets and Replacement Demand

The average light vehicle in the United States reached about 12.6 years of age in 2024, and the EU passenger-car fleet averages more than 12 years [20]. Electronic throttle bodies, EGR valves, and turbo actuators installed during the 2010s now enter peak failure windows, typically after 150,000–200,000 km. Independent workshops increasingly replace complete actuator assemblies rather than cleaning them, lifting aftermarket unit volumes and value.

Restraints Impact Analysis

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
Battery-electric substitution ~−1.0% China, Europe Long-term (≥4 yr)
Rare-earth magnet supply concentration ~−0.6% Global Short-term (≤2 yr)
OEM price-down pressure ~−0.4% Global Medium-term (2–4 yr)
U.S. regulatory uncertainty ~−0.3% North America Short-term (≤2 yr)
Validation cost and qualification time ~−0.3% Global Medium-term (2–4 yr)


Battery-Electric Substitution

In 2024, more than 20% of new cars sold worldwide were electric, with China's share coming close to half [4]. By doing away with the throttle body, EGR valve, wastegate, and turbo actuator, a battery-electric car can save between $150 and $400 per actuator. Although some of that loss is recovered by thermal-management and chassis actuators, the net content per BEV is still lower than that of a turbocharged combustion vehicle.


Rare-Earth Magnet Supply Concentration

In 2024, China dominated magnet processing and produced over 69% of the world's rare-earth mine output [22]. Seven medium and heavy rare earths, such as terbium and dysprosium, which stabilize NdFeB magnets at high temperatures, were subject to export licensing in April 2025 by China's Ministry of Commerce [23]. Within weeks, a number of automakers reported production interruptions, revealing actuator manufacturers lacking suitable substitute magnet supplies.


OEM Price-Down Pressure

Long-term supply agreements commonly embed annual price reductions of 2–3%, and tier-1 suppliers report persistent customer price pressure alongside higher labor and energy costs [13]. Actuators are mature, multi-sourced components, so OEMs benchmark quotes aggressively. Margin compression limits reinvestment in new platforms and pushes smaller suppliers without scale in motors, electronics, and gearing toward consolidation.

5.4 U.S. Regulatory Uncertainty

In July 2025, the EPA proposed rescinding the 2009 endangerment finding along with greenhouse-gas standards for light-, medium- and heavy-duty vehicles [25]. If finalized, the proposal would weaken a key driver behind the MY2027 light-duty rule [2] and the Phase 3 heavy-duty rule [3]. Criteria-pollutant limits would remain, but OEMs may defer some advanced EGR and boost-control programs until litigation settles.

Validation Cost and Qualification Time

Engine-bay actuators must survive 150 °C ambients, soot exposure, and heavy vibration, and heavy-truck programs can require up to 1 million actuation cycles at 145 °C. Full qualification, spanning AEC-Q100 component testing [7], design validation, and vehicle durability runs, often takes 12–18 months. These costs deter new entrants and slow the adoption of novel motor topologies, even where they promise lower magnet content.

Torque Actuator Motor Market Opportunities

Thermal Management and Auxiliary Actuation in Electrified Vehicles

Battery-electric and plug-in hybrid platforms replace combustion actuators with a new cluster of motorized valves: coolant routing valves, refrigerant expansion valves, active grille shutters and e-axle park locks. With more than 17 million electric cars sold in 2024 [4], suppliers that adapt existing gear-motor platforms to these low-torque, high-cycle duties can defend content per vehicle as the powertrain mix shifts. Multi-port coolant valves are an especially attractive entry point because a single heat-pump architecture can require several actuators.

Localization in India, Brazil and ASEAN

Emerging economies offer the clearest volume headroom in the Automotive Torque Actuator Motor Market. India's Production Linked Incentive scheme for automobiles and auto components carries an outlay of ₹25,938 crore [21], and Brazil's Mover program grants tax credits tied to local R&D and efficiency gains [11]. Suppliers that localize motor winding, gear molding, and final assembly can undercut imported units on duty and logistics costs while meeting local-content thresholds.

Actuator Health Data and Predictive-Maintenance Services

Smart actuators already log position error, current draw, and winding temperature. Packaging that data for fleet operators creates a service revenue stream, flagging degraded EGR valves or turbo actuators before they trigger derates or roadside failures. Over-the-air update rules under UNECE Regulation No. 156 [19] give OEMs a compliant channel to push diagnostic firmware, enabling subscription-based health monitoring and performance-linked replacement contracts.

By-Wire Chassis Functions and Electrified Drivelines

Brake-by-wire modules, rear-wheel steering actuators and clutch-based torque vectoring systems all rely on compact, high-response motor actuators with redundant sensing. These functions carry higher safety integrity levels and higher value per unit than throttle actuation, and they are powertrain-agnostic, serving BEVs and hybrids alike. Suppliers with ASIL-D development processes and dual-winding motor designs are best positioned to transfer engine-bay expertise into chassis programs.

Torque Actuator Motor Market Future Outlook

Powertrain Mix Shift and Actuator Redeployment

The IEA projects that electric cars could exceed 40% of global sales by 2030 under current policies [4], while BloombergNEF trimmed its 2025 long-term outlook on slower U.S. adoption [16]. For the Automotive Torque Actuator Motor Market, the likely outcome is a gradual rather than abrupt decline in combustion actuator volume. Suppliers that redeploy motor, gearing, and sensing platforms into thermal and chassis roles will retain share through the transition.

Software-Defined Vehicles and Zonal Architectures

Zonal electrical architectures consolidate dozens of ECUs into a few domain controllers, turning actuators into networked smart nodes. UNECE Regulations No. 155 and No. 156 [19] require cybersecurity management and secure software updates, raising the bar for actuator firmware. Suppliers able to offer secure bootloaders, standardized diagnostics, and over-the-air calibration will capture higher value per unit than commodity motor-and-gearbox vendors.

Hybrids as the Decade's Volume Bridge

Full and plug-in hybrids keep combustion engines in production well into the 2030s, often with more sophisticated boost and EGR strategies than conventional engines because they cycle on and off frequently. Euro 7's extended durability requirement [1] applies equally to hybrids, sustaining demand for high-reliability electric actuators. Hybrid-heavy markets, particularly Japan, China and Europe, will anchor actuator volumes through the mid-2030s.

Magnet Security and Sustainable Design

Concentrated rare-earth supply [22] and 2025 export licensing [23] are pushing suppliers toward magnet-reduced designs, heavy-rare-earth-free NdFeB grades and ferrite alternatives for low-torque duties. Remanufacturing programs that reclaim magnets and gearsets align with OEM carbon-reduction targets. By 2035, magnet traceability and recycled content are likely to become standard supplier-selection criteria alongside cost and durability.

Regional Market Share Analysis

Region Key Metric (Share / USD / CAGR) Primary Investment Themes
North America 20.5% share Heavy-duty EGR and turbo control, pickup and SUV turbocharging
Europe USD 2.65 Billion Euro 7 compliance, 48 V mild hybrids, aftermarket replacement
Asia-Pacific 44.6% share China 6b and BS-VI compliance, hybrid scale-up, localization
South America 8.1% CAGR PROCONVE L8, flex-fuel turbo engines, Mover incentives
Middle East & Africa USD 0.48 Billion Vehicle assembly localization, export-oriented production
Total USD 10.68 Billion —

Regional demand in the Automotive Torque Actuator Motor Market tracks vehicle production density, emission-rule stringency, and the pace of electrification. Asia-Pacific dominates on volume, Europe on technical complexity, and South America on growth momentum.


North America

Country Key Metric (Share of Region / USD / CAGR) Key Driver
US 78.4% share of region Heavy-duty emission programs and turbocharged truck platforms
Canada 6.2% CAGR Hybrid assembly investments in Ontario
Mexico USD 0.29 Billion Export-oriented engine and vehicle assembly under USMCA


Demand in North America rests on turbocharged pickups, SUVs, and heavy trucks rather than small cars. NHTSA's June 2024 CAFE rule targets an industry average of roughly 50.4 mpg for passenger cars and light trucks by model year 2031 [24], encouraging downsized turbo engines and hybrids that carry multiple electric actuators. Mexico's role as an export hub for engines and complete vehicles channels tier-1 investment into local actuator assembly. Federal rule reviews add uncertainty, but criteria-pollutant limits continue to require precise EGR and throttle control [2].

Europe

Country Key Metric (Share of Region / USD / CAGR) Key Driver
Germany 29.6% share of region Premium turbocharged and plug-in hybrid platforms
UK USD 0.33 Billion Aftermarket replacement and performance vehicle programs
France 5.9% CAGR Mild-hybrid adoption across volume brands
Italy 10.8% share of region Small turbocharged gasoline engines and LCV production
Spain USD 0.21 Billion High-volume vehicle assembly for export
Nordic Countries 6.4% CAGR Thermal-management actuators in high-BEV fleets
Russia 5.2% share of region Localized assembly amid restricted Western supply
Rest of Europe USD 0.36 Billion Central European engine and component plants


Europe's actuator demand is shaped by Euro 7, which extends durability obligations to 10 years or 200,000 km and forces redesign of EGR, throttle, and exhaust-flap systems for longer fault-free life [1]. Germany leads through premium hybrid platforms that pair turbocharged engines with electric drive. The region's ageing fleet, averaging more than 12 years [20], sustains a large aftermarket, while the Nordic markets show how actuator content migrates toward thermal management as BEV adoption rises.

Asia-Pacific

Country Key Metric (Share of Region / USD / CAGR) Key Driver
China 51.3% share of region China 6b RDE compliance and plug-in hybrid volumes
India 8.6% CAGR BS-VI Phase 2 and PLI-backed localization
Japan USD 0.86 Billion Full-hybrid engine platforms and tier-1 engineering base
South Korea 8.9% share of region Turbocharged gasoline and hybrid exports
ASEAN 7.9% CAGR Thai and Indonesian assembly with tightening emission rules
Rest of Asia-Pacific USD 0.24 Billion Australian aftermarket and regional assembly


Asia-Pacific leads the Automotive Torque Actuator Motor Market because it combines the world's largest production base with fast-tightening emission rules. China's 6b stage imposes real-driving emissions limits [9], and its plug-in hybrid boom keeps combustion actuators in high volume even as BEVs grow. India's BS-VI Phase 2 has pushed electronic throttle and EGR control into entry-level cars [8]. Japan's tier-1 base, including Denso [14], supplies hybrid-optimized actuators across the region.

South America

Country Key Metric (Share of Region / USD / CAGR) Key Driver
Brazil 63.5% share of region PROCONVE L8 and flex-fuel turbocharged engines
Argentina 8.4% CAGR Pickup and LCV production for regional export
Rest of South America USD 0.09 Billion Imported vehicle fleets and aftermarket demand


Brazil drives the region's growth. PROCONVE L8, phased in from January 2025 under CONAMA Resolution 492/2018 [10], tightens fleet-average emission limits and pushes automakers toward turbocharged flex-fuel engines with electronic boost and EGR control. The Mover program, established by Law 14,902/2024, links tax credits to efficiency and local R&D [11]. Argentina's pickup production adds diesel actuator demand, while a relatively low starting base amplifies percentage growth across the region.

Middle East & Africa

Country Key Metric (Share of Region / USD / CAGR) Key Driver
Saudi Arabia 6.9% CAGR Vision 2030 vehicle manufacturing localization
UAE USD 0.07 Billion Premium vehicle imports and aftermarket services
South Africa 27.4% share of region Export-focused assembly under the APDP
Egypt 7.2% CAGR Expanding local assembly incentives
Rest of MEA USD 0.11 Billion Imported fleets and replacement demand


South Africa remains the region's manufacturing anchor, with the Automotive Production and Development Programme supporting export-oriented assembly for European brands that specify Euro-compliant actuators. Saudi Arabia's Vision 2030 targets domestic vehicle production of around 300,000 units annually by 2030, creating a nascent OEM channel. Across the Gulf, hot ambient conditions shorten actuator service life, supporting replacement demand in the UAE and neighboring markets.

Automotive Torque Actuator Motor Market By Region, 2025-2035

Torque Actuator Motor Market Segmentation

By Type

Segment Key Metric (Share / USD / CAGR) Primary Demand Driver
Electric 71.4% share Drive-by-wire adoption and diagnosability requirements
Pneumatic USD 2.04 Billion Cost-sensitive heavy-duty and legacy engine applications
Mechanical 3.9% CAGR Low-cost overlay retrofits on entry-level throttle bodies


Across the Automotive Torque Actuator Motor Market, Electric actuators lead and also expand fastest, as 48 V architectures supply ample current and OEMs demand integrated diagnostics for OBD compliance. Pneumatic units retain a meaningful revenue base in heavy trucks where compressed air is already available, though tightening controllability requirements erode their position. Mechanical overlay systems, which add position sensors to legacy hardware, serve as a low-cost bridge for basic emission compliance in price-sensitive vehicles.

By Motion Output

Segment Key Metric (Share / USD / CAGR) Primary Demand Driver
Linear 6.81% CAGR Precision EGR valves and exhaust flaps
Rotary 57.3% share Throttle bodies and turbo vane angle control
Electric USD 1.31 Billion Integrated electric-output modules for multi-axis duties


Rotary devices dominate the Automotive Torque Actuator Motor Market because throttle blades and turbo vanes require angular positioning, and mature gear-reduction platforms deliver scale economies. Linear actuators grow fastest, gaining ground in EGR valves where stroke precision directly governs NOx compliance and direct-drive designs eliminate backlash. Electric output modules, which combine drive electronics with synchronized rotary and linear motion, address niche duties such as variable valve timing.

By Application

Segment Key Metric (Share / USD / CAGR) Primary Demand Driver
Electronic Throttle Control 43.4% share Universal drive-by-wire adoption
Turbocharger Actuation 6.73% CAGR Variable-geometry turbines and electric boosting
Exhaust Gas Recirculation (EGR) Valve Actuation USD 1.92 Billion NOx limits under Euro 7, China 6b and BS-VI
Variable Valve Timing 11.6% share Efficiency gains in downsized engines
Others 5.2% CAGR Exhaust flaps, intake runners and swirl control


Electronic Throttle Control leads the Automotive Torque Actuator Motor Market by application, with dual-spring fail-safe designs meeting ASIL-C requirements on nearly every gasoline and hybrid engine. Turbocharger Actuation grows fastest as variable-geometry turbines and electric boosters demand sub-250-millisecond response. EGR Valve Actuation holds substantial value because multi-valve high- and low-pressure loops add actuator nodes per engine, while Variable Valve Timing benefits from downsizing strategies.

By Vehicle Type

Segment Key Metric (Share / USD / CAGR) Primary Demand Driver
Passenger Vehicles 60.2% share Electronic throttles and turbos on high-volume models
Light Commercial Vehicles 6.77% CAGR Last-mile fleet expansion and compact 48 V actuators
Medium and Heavy Commercial Vehicles USD 1.83 Billion Heavy-duty greenhouse-gas and NOx standards


Passenger Vehicles account for the largest portion of the Automotive Torque Actuator Motor Market, since each turbocharged engine carries several actuators and NVH targets push demand for helical gearing and quieter drive algorithms. Light Commercial Vehicles grow fastest, supported by delivery fleets that favor compact actuators and predictive maintenance. Medium and Heavy Commercial Vehicles generate high value per unit because extended durability specifications and stainless-steel housings command premium pricing.

By Sales Channel

Segment Key Metric (Share / USD / CAGR) Primary Demand Driver
OEM 81.4% share Co-engineering, homologation and multiyear platform awards
Aftermarket 6.83% CAGR Ageing fleets and longer vehicle ownership cycles


OEM supply dominates the Automotive Torque Actuator Motor Market because actuators are co-engineered with engine calibration and locked in through homologation and warranty obligations. The Aftermarket grows faster as vehicles age past 12 years on average and actuators installed in the 2010s reach end of life. Repair kits and remanufactured assemblies lower ownership costs, while performance tuners sustain a small premium niche.

Competitive Benchmarking

Competition in the Automotive Torque Actuator Motor Market is moderately consolidated. Market Research Future estimates a Herfindahl-Hirschman Index of roughly 500–700, which is unconcentrated by antitrust thresholds, yet the top five suppliers together hold an estimated 38–46% of revenue. Leadership rests on vertically integrated motor, electronics, and sensing capabilities, as disclosed in supplier reporting from Robert Bosch [12] and Denso [14]. A long tail of regional motor makers competes on price in pneumatic, mechanical, and aftermarket segments.

Company Est. Revenue Share Range Key Offerings for Automotive Torque Actuator Motor Market Strategic Positioning
Robert Bosch GmbH ~11–14% Electronic throttle bodies, EGR valves, integrated driver ICs Broad powertrain portfolio with in-house semiconductors
Continental AG ~8–11% Turbo and EGR actuators, smart actuator electronics Systems integration across powertrain and chassis
Denso Corporation ~8–10% Throttle bodies and hybrid-optimized actuators Deep ties to Japanese hybrid OEMs
Hitachi Astemo ~5–7% Throttle and valve-timing actuators Hybrid and chassis synergies with Japanese OEMs
Mitsubishi Electric Corporation ~4–6% Turbo wastegate and EGR actuators Motor and power-electronics expertise
Nidec Corporation ~4–6% Actuator motors and gear-motor assemblies Scale in precision motors, expanding into e-mobility
Johnson Electric Holdings ~3–5% Motors for throttle, EGR and thermal valves Cost-competitive motor supply to tier-1s
FORVIA Hella ~3–5% Electronic actuators and position sensors Electronics-led actuator and sensor integration
BorgWarner Inc. ~3–5% Turbocharger actuators and EGR modules Turbo system ownership enabling bundled actuation
Schaeffler AG ~2–4% Valve-train actuators, repair solutions, e-mobility actuators Expanded portfolio after Vitesco merger


Recent News & Developments

  • European Union (April 2024): The Council adopted the Euro 7 Regulation, later published as Regulation (EU) 2024/1257, extending durability obligations and forcing redesign of EGR and throttle actuation for longer fault-free life. [1]
  • U.S. EPA (March 2024): The agency finalized multi-pollutant standards for model year 2027–2032 light- and medium-duty vehicles, favoring turbocharged hybrids with electronic boost and EGR control. [2]
  • U.S. EPA (March 2024): Phase 3 greenhouse-gas standards for heavy-duty vehicles were finalized, supporting demand for precision truck EGR and turbo actuators. [3]
  • Ministry of Road Transport & Highways, India (April 2023): BS-VI Phase 2 introduced real-driving emissions testing and stricter OBD thresholds, pushing electronic actuation into entry-level vehicles. [8]
  • Government of Brazil (June 2024): Law 14,902 established the Mover program, linking tax credits to vehicle efficiency and local R&D investment. [11]
  • Schaeffler AG (October 2024): Schaeffler completed its merger with Vitesco Technologies, combining actuator, sensor, and electrified-powertrain portfolios. [15]
  • China Ministry of Commerce (April 2025): Export licensing on seven medium and heavy rare earths disrupted magnet supply for motor-based actuators worldwide. [23]
  • U.S. EPA (July 2025): The agency proposed rescinding the 2009 endangerment finding and associated vehicle greenhouse-gas standards, adding regulatory uncertainty for North American programs. [25]

Torque Actuator Motor Market Report Scope

Parameter Details
Market Scope Automotive Torque Actuator Motor Market by Type, Motion Output, Application, Vehicle Type, Sales Channel and Region
Study Period 2021–2035 (Historical: 2021–2024; Base Year: 2025; Forecast: 2026–2035)
CAGR 6.70% (2026–2035)
Market Size checkpoints USD 10.68 Billion (2025); USD 11.40 Billion (2026); USD 14.95 Billion (2030); USD 20.43 Billion (2035)
Fastest Growing Segments Aftermarket (6.83% CAGR); Linear (6.81% CAGR); Light Commercial Vehicles (6.77% CAGR); Turbocharger Actuation (6.73% CAGR)
Companies Profiled Robert Bosch GmbH, Continental AG, Denso Corporation, Hitachi Astemo, Mitsubishi Electric Corporation, Nidec Corporation, Johnson Electric Holdings, FORVIA Hella, BorgWarner Inc., Schaeffler AG
Valuation Currency USD Billion (constant 2025 exchange rates)

FAQs

What should investors track when evaluating suppliers in the Automotive Torque Actuator Motor Market?
Hybrid platform awards matter more than headline revenue, because hybrid programs keep combustion actuators in production into the 2030s. A supplier's share of 2027–2030 hybrid nominations is the clearest indicator of durable volume.
When does a brushed DC motor still make sense over a brushless design?
Brushed motors remain cost-effective for low-duty-cycle tasks such as exhaust flaps. They typically cost 20–35% less than brushless equivalents but wear faster, so they suit functions cycling only a few thousand times per year.
How are supply contracts in the Automotive Torque Actuator Motor Market typically priced?
Magnet, copper, and steel content increasingly sits under raw-material indexation clauses that pass quarterly cost changes to the OEM. Buyers should ask suppliers to separate magnet cost from conversion cost so quotes can be benchmarked cleanly.
Does vehicle cybersecurity regulation affect actuator suppliers?
Yes. UNECE Regulation No. 155 has applied to all new vehicles in participating markets since July 2024, bringing networked smart actuators inside OEM cybersecurity audits [19]. Suppliers now need firmware signing and documented vulnerability management.
Which position-sensing technology is gaining ground inside actuators?
Inductive position sensors are displacing Hall-effect sensing in hot exhaust duties because they need no magnet and resist stray fields from nearby electric motors. Hall-effect designs stay cheaper for throttle bodies operating below roughly 125 °C.
Are hydrogen combustion engines an emerging use case for the Automotive Torque Actuator Motor Market?
Yes. Hydrogen engines under development by truck makers need fast throttle and EGR control to manage combustion temperature and NOx, reusing diesel-derived actuator platforms with hydrogen-compatible seals. Volumes should stay at pilot scale before 2030.
What causes most actuator field failures?
Soot and carbon fouling of EGR and wastegate linkages drives most warranty returns across the Automotive Torque Actuator Motor Market, followed by gear-train wear and connector corrosion. Suppliers counter with sealed housings and key-off cleaning routines.
Author
Author Author Profile Triveni Bhoyar LinkedIn Senior Research Analyst
Triveni Bhoyar has over 5 years of experience in the market research industry, specializing in the Automotive and Aerospace & Defense sectors. She has contributed to 200+ reports, including numerous custom projects for leading global companies, delivering solutions to complex business challenges. Renowned for her ability to generate valuable insights, Triveni excels in addressing unique market dynamics with precision and depth. Her expertise spans market sizing, competitive intelligence, and trend analysis, enabling clients to craft data-driven growth strategies. With strong analytical rigor and a client-centric approach, she plays a pivotal role in driving impactful, strategic decision-making.
Co-Author Co-Author Profile Sejal Akre LinkedIn Senior Research Analyst
She has over 5 years of rich experience, in market research and consulting providing valuable market insights to client. Hands on expertise in management consulting, and extensive knowledge in domain including ICT, Automotive & Transportation and Aerospace & Defense. She is skilled in Go-to market strategy, industry analysis, market sizing, in depth company profiling, competitive intelligence & benchmarking and value chain amongst others.
Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.

















