Welding Consumables Market Summary
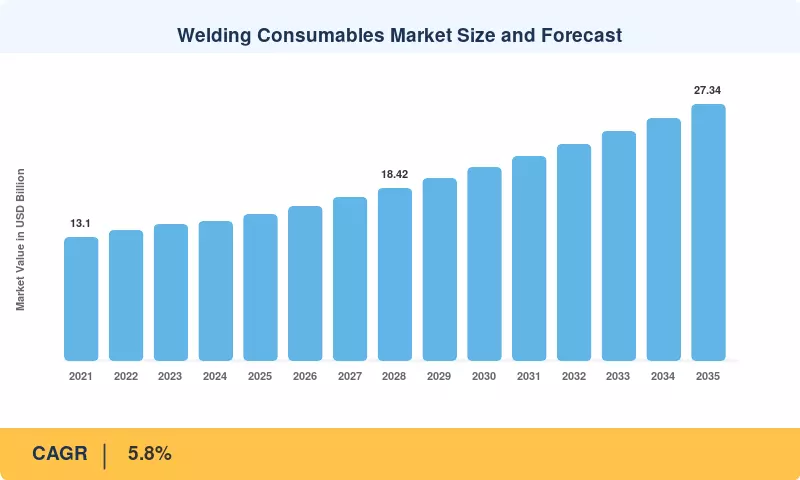
The welding consumables market reached USD 15.56 billion in 2025 and is forecast to open the 2026–2035 period at USD 16.46 billion, expanding at a 5.8% CAGR to USD 27.34 billion by 2035. Public works budgets set the pace. The U.S. Infrastructure Investment and Jobs Act committed USD 1.2 trillion to bridges, rail, water and energy networks [2], while India budgeted ₹11.21 lakh crore of central capital expenditure for FY2025–26 [3]. Both programs translate directly into structural steel tonnage, pipe spools and pressure equipment that must be joined, inspected and certified.
Shop floors are moving away from manual stick processes toward wire-fed semi-automatic and robotic cells. Flux-cored and metal-cored wire grades now displace covered electrodes on repetitive structural and vessel seams because they deposit metal faster and feed reliably into robots. The International Federation of Robotics counted roughly 542,000 industrial robot installations worldwide in 2024 [4], and welding remains one of the largest application groups. That shift moves revenue toward higher-value, traceable products with batch-level quality documentation.
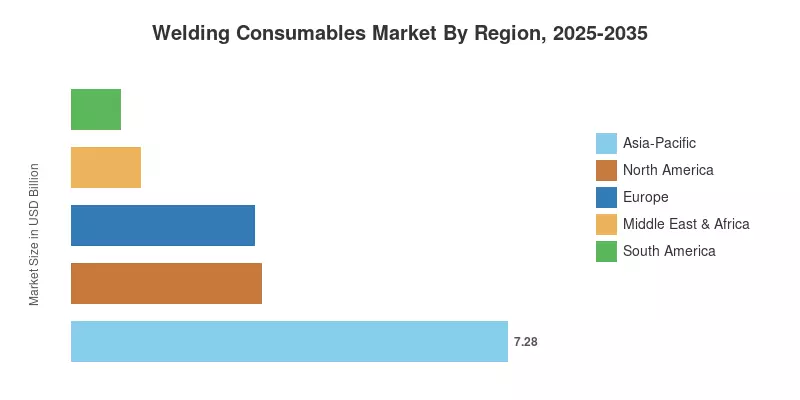
Asia-Pacific dominates with a 46.8% share, anchored by Chinese, Korean and Japanese shipyards and steel fabrication. Middle East & Africa is the fastest-growing region at a 7.4% CAGR, supported by Gulf giga-projects and hydrocarbon capacity expansions. North America ranks second at USD 3.17 billion, lifted by reshored manufacturing and grid investment. Over the next decade, the welding consumables market will reward suppliers that pair certified metallurgy with automation-ready packaging and digital weld records.
Key Report Takeaways
• By Product Type
- Stick Electrodes accounted for 36.5% of the welding consumables market in 2025, reflecting field portability and broad code approvals.
- Flux-Cored Wires are the fastest-expanding product line, posting a 7.6% CAGR through 2035 as robotic cells replace manual seams.
• By Material Type
- Steel grades held a 48.7% share, covering carbon, high-strength low-alloy and stainless fabrication.
- Aluminum is forecast to grow at an 8.8% CAGR on EV battery enclosures and lightweight vehicle bodies.
• By Welding Technique
- Arc-based processes captured 65.6% of 2025 consumption across SMAW, GMAW, GTAW and SAW.
- Laser and Electron-Beam Welding grows at a 10.8% CAGR, although filler use per joint stays comparatively low.
• By End-Use Industry
- Building & Construction remained the largest buyer group in the welding consumables market with a 28.4% share.
- Automotive & Transportation is set to rise at a 6.9% CAGR, driven by EV platform launches.
• By Region
- Asia-Pacific led global demand with a 46.8% share.
- Middle East & Africa is the fastest-growing region at a 7.4% CAGR.
- North America generated USD 3.17 billion in 2025.
Market Size and Forecast (2021–2035)
Market Research Future built the welding consumables market series from company filings, trade statistics for electrode and wire shipments, steel and aluminum consumption data and 350+ interviews with procurement heads, fabricators and distributors[10]. Historical values reconcile shipment volumes with average selling prices, while forecast values apply segment-level demand models validated against capital-spending pipelines in construction, energy, transport and shipbuilding.




 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA


