Security Orchestration Automation and Response (SOAR) Market Summary
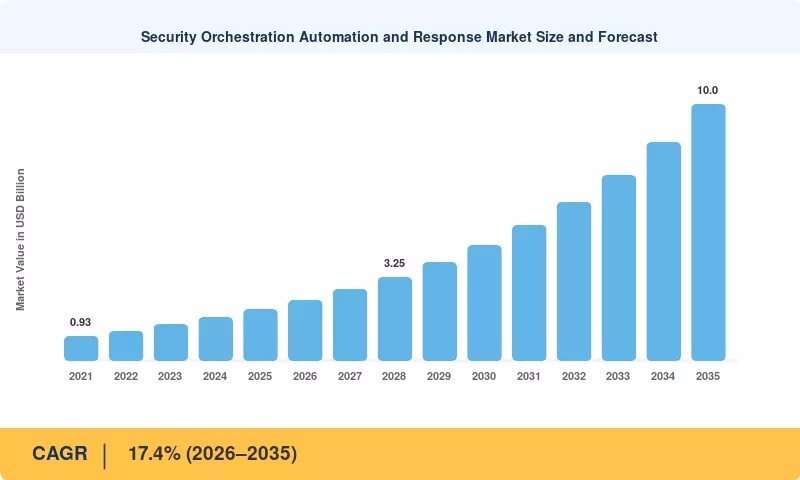
The Security Orchestration, Automation and Response Market reached USD 2.01 billion in 2025 and opens the forecast window at USD 2.36 billion in 2026, climbing to USD 10.00 billion by 2035 at a 17.4% CAGR. Two catalysts anchor that trajectory. The U.S. Securities and Exchange Commission's four-business-day materiality disclosure rule, effective December 2023, converted breach handling from an engineering concern into a board-reported obligation [4]. In parallel, the EU's NIS2 Directive extended binding 24-hour early-warning duties across roughly 160,000 entities in 18 sectors [6]. Both regimes reward measurable containment speed, and orchestration is the cheapest lever available.
This is the legacy ticket-driven triage system being replaced. Analysts were copying indicators by hand from a SIEM console, an EDR agent, a ticketing queue and a firewall management plane. The Security Orchestration, Automation And Response Market replaces that human handoff with API-connected playbooks, case management, and, increasingly, generative-AI authoring layers that write containment logic from natural-language prompts. Average global breach cost was estimated around USD 4.4 million in IBM’s breach research in 2025, with significantly automated defenders reporting materially lower losses [3].
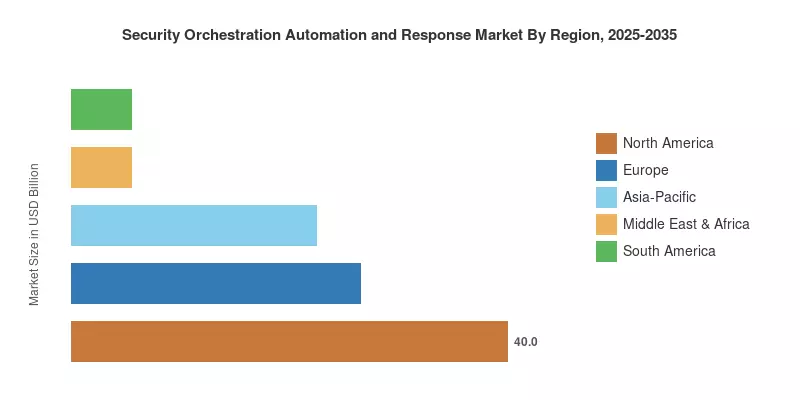
The regional weighting is skewed. North America generated 40.0% of revenue in 2025 due to federal investment and a mature cyber-insurance underwriting base. Asia-Pacific will grow the quickest at a 20.0% CAGR through 2035 as India, Japan, and Gulf-adjacent ASEAN economies shore up vital infrastructure. Europe is the second-largest market with 26.5%, driven by NIS2 transposition dates and DORA’s banking sector resilience tests. The Security Orchestration, Automation and Response Market transitions from alert-reduction tooling to autonomous decision infrastructure, which will be crucial to any meaningful security program over the next decade.
Key Report Takeaways
The Security Orchestration, Automation and Response Market divides across four commercial dimensions and five geographies. Each takeaway below discloses a single headline metric.
• By Component
- Software/Platforms retained 68.0% of 2025 revenue, reflecting buyer preference for consolidated case management and playbook engines.
- Services expand at a 19.4% CAGR through 2035 as playbook customization and managed delivery outpace license growth.
• By Deployment Mode
- Cloud-Based deployments captured 66.0% of 2025 spend within the Security Orchestration, Automation and Response Market, driven by API-first integration breadth.
- On-Premises installations still grow at an 11.8% CAGR, sustained by sovereign and defence workloads.
• By Organization Size
- Large Enterprises accounted for 72.5% of 2025 revenue, anchored by cross-tenant orchestration requirements.
- Small and Mid-Size Enterprises (SMEs) post the steepest 21.0% CAGR as templated playbooks compress deployment timelines.
• By Industry Vertical
- BFSI led with 31.0% of 2025 revenue under supervisory pressure from DORA and equivalent regimes
- Healthcare and Life Sciences accelerates at a 20.4% CAGR as connected medical devices multiply the attack surface.
• By Region
- North America commanded 40.0% of 2025 revenue in the Security Orchestration, Automation and Response Market.
- Asia-Pacific advances at a 20.0% CAGR through 2035, the fastest of any geography
Market Size and Forecast (2021–2035)
Below are estimates based on vendor revenue reports, interviews with channel partners across 40 systems integrators, procurement records from regulated customers, and a bottom-up build of seat-and-node licensing normalized to USD billion. Audited or reported numbers are shown for historical years; projection years are based on a demand model weighted to regulatory deadlines, cloud migration velocity, and analyst-headcount elasticity. The base year is 2025.





 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA



