Precision Viticulture Market (2026 - 2035)

Precision Viticulture Market Size, Share, Industry Trend & Analysis Research Report: By Component (Hardware, Software, Services), By Technology (Guidance, Remote Sensing, Variable-Rate Technology, Robotics & Automation), By Application (Yield Monitoring, Disease & Pest Management, Irrigation Management, Variable-Rate Application, Others), By End User (Large Vineyards, Medium Vineyards, Small Vineyards), By Deployment Mode (On-Premise, Cloud-Based), By Geography (North America, Europe, Asia-Pacific, South America, Middle East & Africa) - Forecast to 2035

ID: MRFR/Agri/29561-HCR 100 Pages Snehal Singh Last Updated: September 17, 2026
Precision Viticulture Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)14.6%
2025 Market SizeUSD 1.27 Billion
2035 Market SizeUSD 4.96 Billion
Key Players
Trimble Inc.
Topcon Positioning Systems
CNH Industrial
Pellenc S.A.
AGCO Corporation
Robert Bosch GmbH
Opportunities
  • Vineyard Robotics Moves From Pilot to Payroll
  • Data Monetisation Through Insurance and Finance
  • Emerging Market Whitespace in Asia and Africa

Precision Viticulture Market Summary

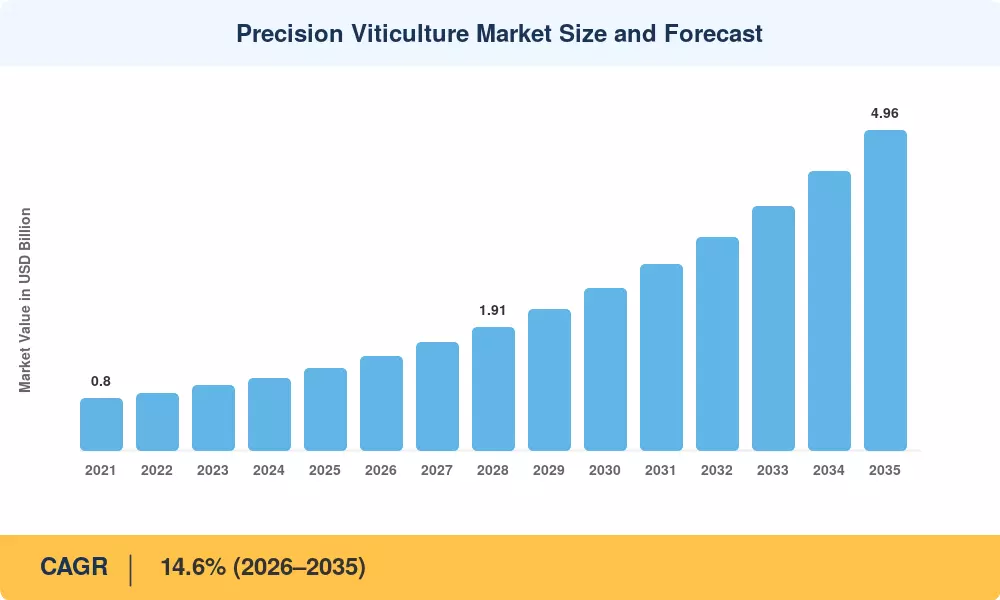
The Precision Viticulture Market closed 2025 at USD 1.27 billion and enters the forecast window at USD 1.46 billion in 2026, climbing to USD 4.96 billion by 2035 at a 14.6% CAGR. Two catalysts anchor that trajectory. California's Irrigated Lands Regulatory Program now obliges thousands of grape growers to document nitrogen and water applications at block level, and the European Union's wine-sector support envelope under the 2023–2027 CAP Strategic Plans channels roughly EUR 1.06 billion annually toward restructuring and modernisation, a large slice of which underwrites digital equipment [4][5].

Legacy practice is what makes the numbers move. Calendar-based spraying, whole-block irrigation scheduling and clipboard scouting are giving way to multispectral imaging, soil-moisture telemetry and prescription-driven sprayers. Sub-USD 5,000 drone payloads have pushed canopy monitoring out of research estates and into commercial 40-hectare operations, and the Precision Viticulture Market has absorbed that cost collapse faster than most permanent-crop segments [8][10].

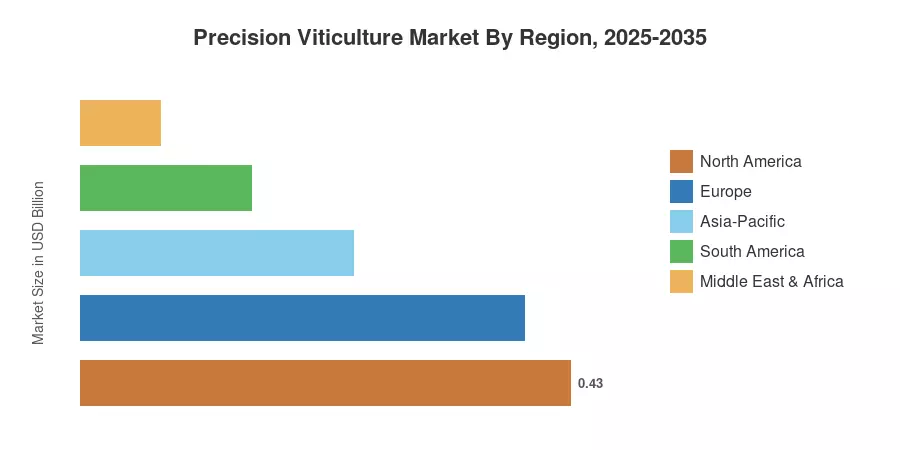
Geography still shapes the opportunity. North America holds 33.5% of 2025 revenue on the strength of Californian and Pacific Northwest adoption, Asia-Pacific compounds fastest at 19.1% through 2035, and Europe follows closely at USD 0.39 billion with France, Italy, and Spain driving the bulk of spend. Over the next decade, the Precision Viticulture Market shifts from instrument sales toward recurring agronomic intelligence.


Key Report Takeaways

• By Technology

  • Guidance systems commanded 36% of Precision Viticulture Market revenue in 2025, reflecting the installed base of retrofitted tractors and straddle machines
  • Remote sensing platforms generated USD 0.41 billion in 2025 as satellite-plus-drone stacks became standard on estates above 30 hectares
  • Variable-rate technology is set to expand at a 19.6% CAGR through 2035, the strongest hardware-adjacent growth line

• By Application

  • Yield monitoring applications accounted for 26.5% of the Precision Viticulture Market in 2025
  • Disease and pest management tools represent USD 0.29 billion of current spend, pulled forward by downy mildew pressure in Mediterranean Europe
  • Irrigation management is forecast to grow at 17.9% CAGR as groundwater rules tighten across drought-exposed basins

• By Region

  • North America led with 33.5% revenue share in 2025
  • Asia-Pacific is projected to post a 19.1% CAGR through 2035
  • South America contributed USD 0.15 billion, concentrated in Mendoza and central Chile


Market Size and Forecast (2021–2035)

Estimates below triangulate vendor shipment disclosures, national vineyard-area statistics from the International Organisation of Vine and Wine, customs data on GNSS receivers and agricultural UAVs, and interviews with equipment dealers across nine wine-producing countries. Historical values are reconciled against audited segment revenue where public filings permit [1][18][19].
Precision Viticulture Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Collapsing sensor and UAV hardware costs +2.4 Global Short-term (≤2 yr)
Vineyard labour scarcity and wage inflation +2.1 North America, Europe, Oceania Short-term (≤2 yr)
Water-quality and nutrient runoff regulation +1.8 North America, Europe Medium-term (2–4 yr)
Climate volatility and adaptation funding +1.6 Europe, South America, Oceania Medium-term (2–4 yr)
Public digital-agriculture subsidies +1.5 Asia-Pacific, Europe Medium-term (2–4 yr)
AI-driven agronomic decision platforms +1.3 Global Long-term (≥4 yr)
Premium provenance and traceability claims +0.9 Europe, North America Long-term (≥4 yr)


Hardware Cost Deflation Opens the Mid-Tier

The customer profile was altered by sensor economics. A five-band multispectral payload plus airframe cost approximately USD 4,600 in 2024, compared to USD 17,000 in 2019, according to UC Davis field studies, and payback was estimated within 2.3 seasons on a 45-hectare coastal block using fungicide savings alone [10]. Estates that used to hire experts to handle their imagery now conduct their own weekly missions. The Precision Viticulture Market indicates that software is expanding more quickly than the equipment it depends on because of this change, which turns an episodic service cost into a capital purchase followed by a software subscription.


Labour Scarcity Forces Mechanisation

There is constant pressure on wages. The average compensation for hired farmworkers in the US was USD 19.75 per hour in 2024, up 22% from 2020. Meanwhile, farmers in Australia and New Zealand claim that 15–20% of seasonal posts remain vacant [3][20]. The exposed line items include scouting, pruning, and canopy work. The honest framing that most suppliers currently employ in their business cases is that automated scouting and guidance-enabled machinery reduce hours per hectare rather than completely replacing experienced labor.


Regulation Turns Data Into Compliance Infrastructure

Runoff rules made record-keeping mandatory. Growers enrolled in California's Irrigated Lands Regulatory Program must file annual nitrogen application and removal reports covering more than 6 million irrigated acres statewide, and third-party coalition audits increasingly expect georeferenced evidence rather than aggregate estimates [5]. Compliance software bought for regulatory reasons ends up delivering agronomic value, and vendors have learned to sell the second benefit while invoicing for the first.

Adaptation Funding Underwrites Experimentation

Climate money is reshaping trial budgets. INRAE's Vitis 2050 programme committed EUR 42 million across French research consortia examining rootstock selection, shading and irrigation triggers, with instrumented plots supplying the underlying datasets [9]. Public co-funding lowers the risk of early deployment for cooperatives that would never self-fund a five-year sensor network.


Restraints Impact Analysis

Restraint weightings follow the same directional convention as Section 4. They quantify drag on adoption velocity, not deductions from the published growth rate, and several interact with the drivers above rather than offsetting them cleanly. The Precision Viticulture Market grows through these frictions, not in their absence.

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
High upfront capex for smallholders −1.7 Global Short-term (≤2 yr)
Rural connectivity gaps −1.2 South America, MEA, Asia-Pacific Medium-term (2–4 yr)
Fragmented data standards and interoperability −1.0 Global Medium-term (2–4 yr)
Shortage of digital agronomy skills −0.9 Global Long-term (≥4 yr)
UAV airspace and aerial application restrictions −0.7 Europe, North America Short-term (≤2 yr)


Capital Intensity Excludes the Long Tail

Scale determines feasibility. FAO analysis of permanent-crop digitalisation found that holdings below 5 hectares rarely clear investment thresholds without shared-equipment models, and roughly 70% of the world's vineyard holdings sit under that line [1][7]. Cooperative purchasing and contractor-supplied services are the practical workaround, though they dilute vendor margins and slow platform stickiness.

Interoperability Remains an Unsolved Tax

Standards adoption lags marketing claims. The Agricultural Industry Electronics Foundation's conformance testing found meaningful variation in ISOBUS implementation across manufacturers, and mixed-fleet vineyards frequently discover that a prescription map generated in one platform will not execute correctly on another brand's controller [14]. Integration consultancy then consumes 8–12% of project budgets that buyers had assumed were fully allocated to hardware.

Connectivity Is Still the Binding Constraint Off-Grid

Coverage gaps bite hardest where vineyards are remote. Growers in Mendoza, the Western Cape and inland Anatolia report cellular coverage failures across meaningful portions of planted area, forcing store-and-forward architectures or LoRaWAN gateways that add cost per hectare [7][22]. Low-earth-orbit backhaul is closing the gap, but per-terminal pricing still exceeds what a 20-hectare block can justify.


Precision Viticulture Market Opportunities

Vineyard Robotics Moves From Pilot to Payroll

Autonomous straddle platforms are the clearest hardware opportunity. Several European manufacturers now offer supervised-autonomy units capable of mowing and spraying overnight, and at prevailing wage levels a machine covering 25 hectares per shift reaches breakeven inside four seasons in France and California [15]. Vendors that pair machines with agronomic prescriptions rather than selling iron alone will capture disproportionate value.

Data Monetisation Through Insurance and Finance

Recurring revenue may come from outside the vineyard gate. Parametric frost and hail products priced off continuous sensor logs are already live with a small group of underwriters, and Swiss Re Institute analysis indicates verified microclimate data can compress loss-adjustment cost by a fifth [17]. Platform operators sitting on multi-season block histories hold an asset that lenders and insurers will pay to access, subject to grower consent.

Emerging Market Whitespace in Asia and Africa

Newer wine regions skip legacy steps entirely. China's digital agriculture programme and India's expanding Nashik and Karnataka plantings create demand for cloud-first deployments unencumbered by installed on-premise systems, while South African producers use precision tooling to defend export quality claims [11][22]. Adoption there begins with vineyard mapping technology and moves quickly to variable-rate application, compressing a decade of European sequencing into three or four seasons.

Subscription Agronomy for the Sub-20-Hectare Grower

Service models solve the capex problem. Contractor-flown imagery bundled with a per-hectare annual advisory fee brings professional-grade analytics to growers who will never buy a drone, and Wine Australia's adoption study found willingness-to-pay clustering around AUD 90–140 per hectare per year [6]. Whoever industrialises that delivery model captures the volume tier of the Precision Viticulture Market.

Provenance Verification for Premium Export Channels

Traceability is becoming a commercial requirement. Import buyers in Japan, South Korea, and the Nordic monopolies increasingly request documented sustainability credentials, and block-level records provide auditable evidence that generic certification cannot [20]. The Precision Viticulture Market benefits because the same data layer serves agronomy, compliance and marketing simultaneously.


Precision Viticulture Market Future Outlook

Autonomy Becomes Ordinary

Supervised autonomy will define the second half of the forecast period. Machines that mow, spray, and pre-prune without a seated operator are already commercially available in France and Italy, and the constraint is now liability frameworks rather than engineering [15]. Expect fleet-level orchestration software to become the differentiating layer by 2030, with hardware margins compressing toward conventional machinery norms.

Platform Economics Reshape Vendor Revenue

Recurring revenue overtakes equipment sales. Software attach rates on new precision hardware already exceed 60% among estates above 50 hectares, and the Precision Viticulture Market is following the trajectory of row-crop agronomy platforms a decade earlier [18]. Vendors that fail to build annuity streams will find themselves competing on price against increasingly commoditised sensors.

Electrification and Energy Discipline

Energy costs enter the calculation. IEA analysis of agricultural electrification points to falling operating expense for battery-electric utility vehicles in permanent crops, where duty cycles are short and charging infrastructure is centralised at the winery [21]. Vineyards are unusually well suited to electrification, and by the early 2030s electric straddle tractors paired with on-site solar should be unremarkable in Mediterranean and Californian operations.

Sustainability Reporting Becomes a Data Problem

Disclosure obligations keep expanding. Corporate buyers subject to European sustainability reporting requirements are pushing scope-three data requests down to their supplying estates, and generic averages will not satisfy assurance providers indefinitely [20]. Block-level records solve that problem, which quietly turns the Precision Viticulture Market into part of the reporting infrastructure of the global wine trade.


Regional Market Share Analysis

Region Metric (2025) Primary Investment Themes
North America 33.5% revenue share Water compliance reporting, autonomous machinery, labour substitution
Europe USD 0.39 Billion CAP-funded modernisation, disease forecasting, appellation traceability
Asia-Pacific 19.1% CAGR (2026–2035) Subsidised digital agriculture, cloud-first deployment, new plantings
South America 11.5% revenue share Irrigation efficiency, export quality assurance, contractor services
Middle East & Africa USD 0.07 Billion Water scarcity management, export certification, drip-plus-sensor retrofits
Total USD 1.27 Billion —

Regional performance in the Precision Viticulture Market tracks three variables: vineyard concentration, labour cost and regulatory intensity. Where all three run high, penetration exceeds 40% of planted area; where any one is absent, adoption stalls below 15%.


North America

Country Metric Key Driver
US 78% share of region Irrigated Lands reporting and Californian labour costs
Canada USD 0.05 Billion Cold-climate frost risk management in Okanagan and Niagara
Mexico 15.8% CAGR Baja California export-oriented expansion


Regulatory gravity explains American leadership in the Precision Viticulture Market. Coalition reporting obligations across the Central Coast and Central Valley have made georeferenced application records routine, and the state's Sustainable Groundwater Management Act allocations give irrigation analytics a direct financial return where water is metered and traded [5]. Canadian uptake is narrower but deeper, concentrated on frost-event prediction where a single night determines the vintage.

Europe

Country Metric Key Driver
Germany 13.9% CAGR Steep-slope mechanisation and mildew forecasting
UK USD 0.02 Billion Rapid sparkling-wine plantings on chalk soils
France 26% share of region CAP restructuring aid and appellation quality controls
Italy USD 0.09 Billion Cooperative-scale deployment across Veneto and Puglia
Spain 18% share of region Water scarcity and large-block irrigation optimisation
Nordic Countries 12.4% CAGR Importer-driven sustainability verification
Russia 3% share of region Domestic plantings under import substitution policy
Rest of Europe USD 0.04 Billion Portugal, Austria and Greece modernisation grants


Subsidy design drives European behaviour. National Support Programmes reimburse a defined share of eligible restructuring and investment costs, and several member states have explicitly ruled digital equipment eligible, which pulled purchases forward into 2025 and 2026 [4]. Disease pressure adds urgency: Mediterranean producers faced severe downy mildew losses in 2023, and forecasting tools moved from optional to defensive overnight [9].

Asia-Pacific

Country Metric Key Driver
China 34% share of region Ningxia and Xinjiang state-backed plantings
India 21.6% CAGR Nashik export programmes and table-grape quality standards
Japan USD 0.03 Billion High-value Koshu production and acute labour scarcity
South Korea 7% share of region Protected cultivation and controlled-environment integration
ASEAN 18.2% CAGR Thai and Vietnamese boutique estates
Rest of Asia-Pacific 26% share of region Australian and New Zealand climate-adaptation programmes


Policy money moves faster here than anywhere else in the Precision Viticulture Market. China's rural digitalisation plan directs provincial matching funds toward sensor networks and machinery upgrades, and Ningxia's designated wine corridor has become a proving ground for integrated deployments [11]. Australia contributes technical depth rather than volume, with research institute trials on targeted spraying feeding product development that later ships globally [15].

South America

Country Metric Key Driver
Brazil USD 0.03 Billion Serra Gaúcha sparkling expansion and fungal pressure
Argentina 41% share of region Mendoza irrigation efficiency under Andean snowpack decline
Rest of South America 16.4% CAGR Chilean and Uruguayan export-driven adoption


Water defines the Argentine case. Declining Andean snowpack has forced Mendoza growers to justify every litre, and soil-moisture networks paired with drip retrofits have delivered documented consumption reductions of 18–25% on instrumented blocks [22]. Chilean exporters adopt for a different reason entirely: retailer sustainability audits in the UK and Nordic markets increasingly demand evidence rather than assurances [20].

Middle East & Africa

Country Metric Key Driver
Saudi Arabia 18.9% CAGR Table-grape production under Vision 2030 agriculture programmes
UAE USD 0.01 Billion Controlled-environment horticulture spillover
South Africa 47% share of region Western Cape drought recovery and export certification
Egypt 11% share of region Nile Delta table-grape export quality control
Rest of MEA 14.2% CAGR Morocco, Turkey and Israel adoption


Scarcity is the whole story in this region. South African producers who lived through the Day Zero water crisis institutionalised monitoring afterwards, and Western Cape estates now routinely operate soil-moisture arrays that would have been considered experimental a decade ago [7]. Israeli and Moroccan growers apply irrigation technology developed for other crops, which shortens the learning curve considerably.


Precision Viticulture Market By Region, 2025-2035

Precision Viticulture Market Segmentation

By Component

Component mix in the Precision Viticulture Market is shifting from iron toward intelligence, though hardware remains the entry point for almost every buyer.

Segment Metric (2025) Primary Demand Driver
Hardware 43% revenue share Sensors, receivers, controllers, and UAV airframes
Software 18.4% CAGR (2026–2035) Prescription generation and compliance reporting
Services USD 0.29 Billion Contractor flights, agronomy advisory, integration


Hardware still anchors the category because nothing else works without it, and replacement cycles on 2020-vintage sensor deployments will sustain volumes through the late 2020s. Software is where the economics change: annual per-hectare subscriptions convert a one-time transaction into a decade-long relationship, and switching costs rise with every season of stored history.

By Technology

Technology adoption within the Precision Viticulture Market follows a predictable order — guidance first, sensing second, actuation third.

Segment Metric (2025) Primary Demand Driver
Guidance 36% revenue share Retrofit GNSS steering on existing tractor fleets
Remote Sensing USD 0.41 Billion Multispectral and thermal imaging for vigour assessment
Variable-Rate Technology 19.6% CAGR (2026–2035) Input cost control and runoff compliance
Robotics & Automation 12% revenue share Labour substitution in high-wage regions


Guidance dominates because the retrofit case is simple: reduced overlap, straighter rows, less operator fatigue, payback in two seasons. Remote sensing grew from a specialist service into a routine input once satellite revisit frequency improved and drone hardware prices fell, and the two now function as complements rather than substitutes [8].

By Application

Application spend in the Precision Viticulture Market concentrates where a measurable loss can be avoided.

Segment Metric (2025) Primary Demand Driver
Yield Monitoring 26.5% revenue share Harvest logistics and winery capacity planning
Disease & Pest Management USD 0.29 Billion Mildew and botrytis forecasting
Irrigation Management 17.9% CAGR (2026–2035) Groundwater allocation and drought exposure
Variable-Rate Application 19.8% CAGR (2026–2035) Fungicide and nutrient efficiency
Others 13.5% revenue share Frost protection, harvest-date prediction


Yield monitoring leads because winemakers need tonnage forecasts before tank space is committed, and errors are expensive in both directions. Disease management delivers the sharpest single-season return — Australian trials on targeted spraying recorded chemical reductions between 30% and 50% on trellised blocks without measurable efficacy loss [15].

By End User

End-user structure in the Precision Viticulture Market mirrors the underlying concentration of vineyard ownership.

Segment Metric (2025) Primary Demand Driver
Large Vineyards 41% revenue share In-house agronomy teams and full-stack deployments
Medium Vineyards 20.5% CAGR (2026–2035) Falling equipment costs and contractor availability
Small Vineyards 24% revenue share Cooperative purchasing and shared services


Large estates were first movers and remain the revenue base, but growth has migrated to the middle tier where cost declines finally cleared the investment hurdle. Medium operations typically start with mapping and irrigation, then add actuation once two seasons of data justify the prescription.

By Deployment Mode

Deployment preference in the Precision Viticulture Market is turning over faster than most incumbents expected.

Segment Metric (2025) Primary Demand Driver
On-Premise 57% revenue share Connectivity limitations and data-control preferences
Cloud-Based 21.8% CAGR (2026–2035) Multi-site management and lower IT overhead


On-premise persists where connectivity is unreliable and where growers distrust third-party custody of agronomic records. Cloud wins everywhere else, particularly among multi-estate groups that need portfolio-level comparison and cannot maintain servers at each site.


Competitive Benchmarking

Concentration sits in the moderate band. Market Research Future estimates a Herfindahl-Hirschman Index between 720 and 860, with the top five suppliers holding roughly 36–42% of global revenue. Precision agriculture majors bring distribution and ISOBUS-native machinery; viticulture specialists bring crop-specific models that generalists struggle to match. The competitive question for the next five years is whether platform breadth beats domain depth — current evidence suggests partnerships, not outright victory for either camp.

Company Est. Revenue Share Range Key Offerings for the Precision Viticulture Market Strategic Positioning
Trimble Inc. ~9–12% GNSS guidance, field management software, correction services Hardware-agnostic platform incumbent
Deere & Company ~8–11% Autonomous-ready machinery, See & Spray, Operations Center Full-stack machinery and data ecosystem
Topcon Positioning Systems ~6–8% Steering systems, variable-rate controllers, crop sensing Retrofit specialist with strong dealer reach
CNH Industrial ~5–7% Vineyard tractors, precision controllers, telematics OEM integration across specialty-crop fleets
Pellenc S.A. ~4–6% Electric vineyard equipment, harvesters, optical sorting Viticulture-native product portfolio
AGCO Corporation ~4–6% Fendt narrow-track machinery, Precision Planting technologies Machinery-led with expanding software layer
Robert Bosch GmbH ~3–5% Smart spraying sensing, camera-based weed detection Component supplier turned solution partner
Yara International ~3–4% Nitrogen sensing, digital nutrition advisory Agronomy-led, input-linked positioning
VineView ~2–4% Aerial imagery analytics, vine-level disease detection Pure-play imaging specialist
Semios ~2–4% In-canopy sensor networks, pest models, frost alerts Subscription network operator
Fruition Sciences ~2–3% Sap-flow monitoring, water-status analytics Premium estate advisory niche
Agrivi ~1–3% Farm management software, compliance reporting Cloud-first, cost-competitive challenger


Recent News & Developments

  • European Commission (March 2024): Confirmed eligibility of digital vineyard equipment under wine-sector National Support Programmes, unlocking co-funding across France, Italy and Spain and pulling 2026 purchase decisions forward [4]
  • Pellenc (September 2024): Launched an expanded electric vineyard machinery range with integrated telemetry, targeting estates facing both emissions rules and diesel cost exposure [15]
  • Trimble (June 2024): Extended its correction-services network into additional Southern Hemisphere coverage, improving centimetre-grade accuracy for Chilean and South African growers [18]
  • California State Water Resources Control Board (January 2025): Tightened nitrogen reporting granularity under coalition monitoring, increasing demand for block-level record systems [5]
  • Deere & Company (October 2024): Broadened targeted-spray technology availability to specialty-crop configurations, signalling mainstream OEM commitment to permanent crops [19]
  • Wine Australia (November 2024): Published adoption benchmarking showing digital tool penetration on roughly one-third of national vineyard area, with willingness-to-pay data for advisory subscriptions [6]
  • Semios / Bosch collaboration (May 2025): Announced sensor-network integration with camera-based spray control, combining in-block pest models with real-time actuation [17]
  • Ministry of Agriculture and Rural Affairs, China (July 2024): Extended provincial matching funds for digital agriculture equipment to designated wine-producing zones in Ningxia and Xinjiang [11]


Precision Viticulture Market Report Scope

Parameter Detail
Market Scope Global precision viticulture hardware, software, and services across guidance, remote sensing, variable-rate, and robotics technologies
Study Period 2021–2035 (Historical 2021–2024; Base Year 2025; Forecast 2026–2035)
CAGR 14.6% (2026–2035)
Market Size Checkpoints USD 1.27 Billion (2025); USD 1.46 Billion (2026); USD 2.51 Billion (2030); USD 4.96 Billion (2035)
Fastest Growing Segments Software (component); Variable-Rate Technology (technology); Medium Vineyards (end user); Cloud-Based (deployment); Asia-Pacific (geography)
Companies Profiled Trimble, Deere & Company, Topcon, CNH Industrial, Pellenc, AGCO, Bosch, Yara, VineView, Semios, Fruition Sciences, Agrivi
Valuation Currency USD Billion, constant 2025 prices

FAQs

How should a mid-sized estate phase its investment in the Precision Viticulture Market?
Start with soil and vigour mapping, then add variable-rate spraying once two seasons of data exist. Sequencing this way recovers most of the payback before autonomous machinery enters the budget [6].
Who owns the agronomic data generated by Precision Viticulture Market platforms?
Contracts vary widely. European Code of Conduct signatories grant growers ownership and portability, while several vendors elsewhere retain aggregated rights. Negotiate export clauses before signing [12].
Are satellite images an adequate substitute for drone flights?
Satellites suit season-long vigour tracking at three-to-ten-metre resolution and low cost. Drones remain necessary for sub-metre vine-level diagnostics and rapid post-hail assessment. Most serious estates run both [8].
What integration problems surface most often in Precision Viticulture Market deployments?
Mismatched coordinate systems and proprietary controller implementations break data flow between mapping software and sprayers. Insist on documented conformance testing and an open API before purchase [14].
Do insurers recognise precision data in premium calculations?
A small group of European and Australian underwriters now discount frost and hail cover where continuous sensor logs exist. Coverage remains patchy outside those regions [17].
Which emerging use case deserves attention beyond established vineyard applications?
Automated harvest-date prediction using berry-composition sensors is scaling fastest. Early adopters report picking-window accuracy within two days, which materially protects acid balance in premium whites [20].
How does vendor lock-in affect long-term ownership costs?
Closed ecosystems raise switching costs substantially once historical imagery must be re-flown. Insist on open-format archives such as GeoTIFF and shapefile to preserve negotiating leverage at renewal [14].    
Author
Author Author Profile Snehal Singh LinkedIn Manager - Research
High acumen in analyzing complex macro & micro markets with more than 6 years of work experience in the field of market research. By implementing her analytical skills in forecasting and estimation into market research reports, she has expertise in Packaging, Construction, and Equipment domains. She handles a team size of 20-25 resources and ensures smooth running of the projects, associated marketing activities, and client servicing.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of agricultural technology databases, peer-reviewed agricultural journals, viticulture publications, and authoritative agricultural organizations. Key sources included the US Department of Agriculture (USDA), European Commission Agriculture and Rural Development (EC-AGRI), Food and Agriculture Organization of the United Nations (FAO), International Organisation of Vine and Wine (OIV), American Society for Enology and Viticulture (ASEV), National Agricultural Statistics Service (NASS), National Institute of Food and Agriculture (NIFA), Eurostat Agricultural Database, World Bank Agricultural & Rural Development Indicators, International Society for Precision Agriculture (ISPA), European Agricultural Machinery Association (CEMA), Agricultural Research Service (ARS), National Oceanic and Atmospheric Administration (NOAA) Climate Data, Copernicus Land Monitoring Service, and national agriculture ministry reports from key wine-producing markets (France, Italy, Spain, USA, Australia, Chile, Argentina, China). These sources were used to collect vineyard acreage statistics, precision agriculture adoption rates, technology deployment data, climate and soil monitoring datasets, regulatory frameworks for agricultural drones and sensors, wine production volumes, and market landscape analysis for remote sensing technologies, GIS platforms, data analytics solutions, AI/ML applications, and precision farming equipment.


Primary Research

Qualitative and quantitative insights were obtained by interviewing supply-side and demand-side stakeholders during the primary research process. The supply-side sources consist of CEOs, VPs of Product Development, Chief Technology Officers, regulatory affairs leaders, and commercial directors from precision agriculture technology manufacturers, agricultural drone OEMs, sensor technology providers, and vineyard management software companies. Vineyard managers, viticulturists, agricultural consultants, precision agriculture specialists, procurement leads from large winery conglomerates, cooperative vineyard associations, and agricultural extension service officers from key wine-producing regions comprised demand-side sources. The primary research conducted confirmed the product development timelines, validated market segmentation across technology types (remote sensing, GIS, data analytics, AI/ML, precision farming techniques), and gathered insights on technology adoption patterns, pricing strategies for vineyard management solutions, and subsidy utilization dynamics.

Primary Respondent Breakdown:

By Designation: C-level Primaries (32%), Director Level (31%), Others (37%)

By Region: North America (32%), Europe (30%), Asia-Pacific (28%), Rest of World (10%)


Market Size Estimation

Global market valuation was derived through revenue mapping and technology deployment volume analysis. The methodology included:

Identification of 50+ key technology providers and equipment manufacturers across North America, Europe, Asia-Pacific, South America, and Middle East & Africa

Product mapping across remote sensing (drones, satellites, aerial imagery), GIS platforms, data analytics software, AI/ML solutions, and precision farming equipment (variable rate technology, automated machinery, sensor networks)

Analysis of reported and modeled annual revenues specific to precision viticulture and vineyard management portfolios

Coverage of manufacturers representing 75-80% of global market share in 2024

Extrapolation using bottom-up (vineyard acreage × technology adoption rate × ASP by country/region) and top-down (manufacturer revenue validation) approaches to derive segment-specific valuations for yield monitoring, pest and disease management, water management, soil analysis, and canopy management applications across grape, apple, citrus, olive, almond, and other specialty crop segments

Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.

















