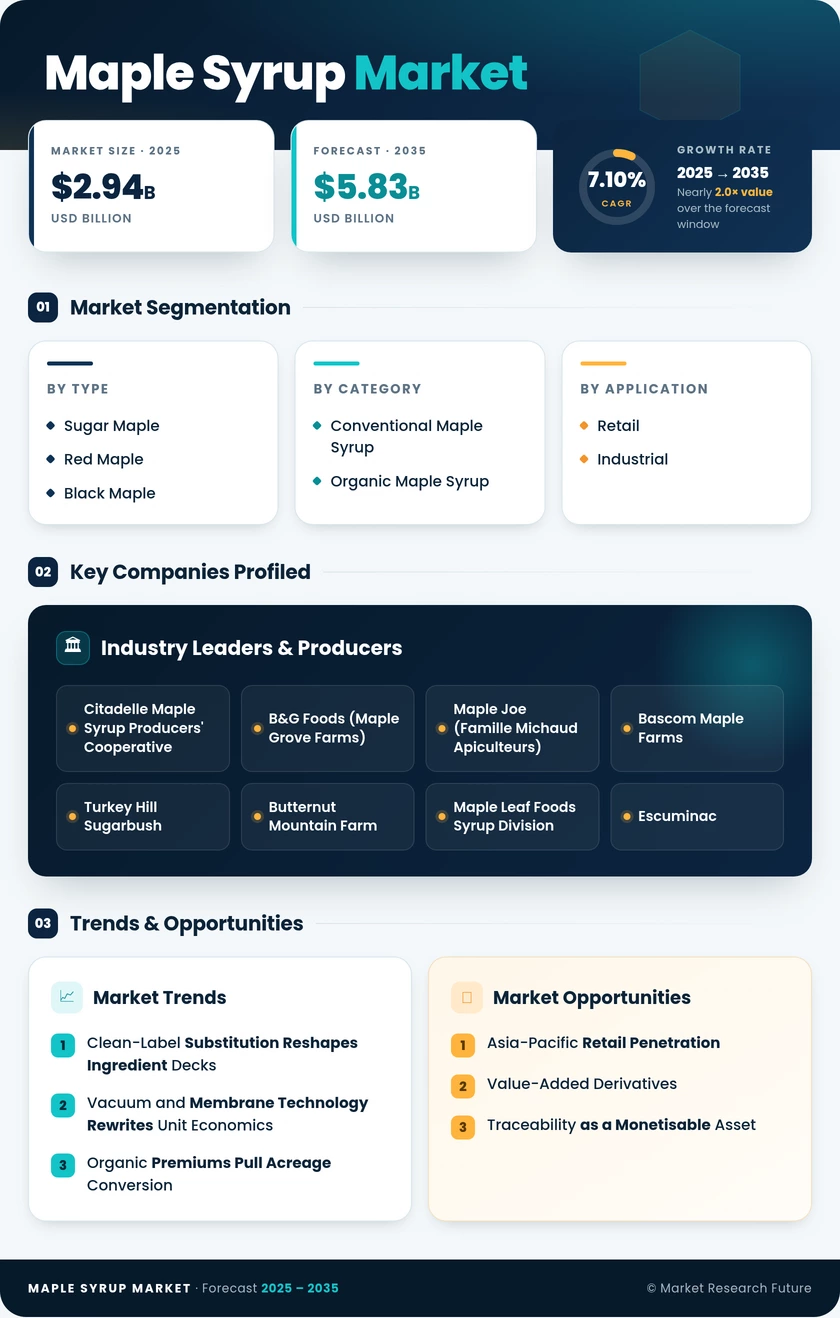
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| By Type | Black Maple, Red Maple, Sugar Maple | Sugar Maple | Black Maple |
| By Category | Conventional Maple Syrup, Organic Maple Syrup | Conventional Maple Syrup | Organic Maple Syrup |
| By End User | Retail, Industrial | Retail | Industrial |
| By Geography | North America, Europe, Asia-Pacific, South America, Middle East & Africa | North America | Asia-Pacific |
Market Segmentation Overview
By Type
| Sub-Segment | Key Trend |
| Black Maple | Drought and heat tolerance drive new planting interest; specialty flavour positioning. |
| Red Maple | Broader geographic range and earlier tapping window extend the harvest calendar. |
| Sugar Maple | Superior sap sugar concentration keeps processing cost per litre lowest. |
Type mix is being reshaped by climate rather than by consumer preference. Sugar maple retains commercial primacy on economics, but producers hedging against warmer seasons are deliberately preserving black and red maple stands that once counted as secondary inventory.
By Category
| Sub-Segment | Key Trend |
| Conventional Maple Syrup | Anchors industrial contracts where cost per Brix governs purchasing decisions |
| Organic Maple Syrup | Certification premiums of 22–28% drive rapid conversion among mid-sized operators |
Category migration is the clearest structural shift in the segmentation set. Low agronomic barriers to conversion mean the constraint is inspection capacity and paperwork throughput, not farming practice, which is why conversion rates continue to outpace most other agricultural categories.
By End User
| Sub-Segment | Key Trend |
| Retail | Premiumisation, gifting formats, and single-origin storytelling sustain margin. |
| Industrial | Beverage, bakery, and sports-nutrition reformulation drives contracted volume growth. |
End-user evolution matters more than its share numbers suggest. Contracted industrial offtake converts an unpredictable seasonal harvest into bankable cash flow, and that financing shift is quietly funding the technology retrofits described throughout this report.
By Geography
| Sub-Segment | Key Trend |
| North America | Supply-side concentration; capacity expansion and reserve rebuild dominate strategy |
| Europe | Organic-led retail growth through German, French, and Nordic premium channels |
| Asia-Pacific | Fastest regional expansion on bakery, café, and premium grocery adoption |
| South America | Hotel and specialty grocery demand concentrated in Brazil. |
| Middle East & Africa | Gulf hospitality procurement and UAE re-export distribution hubs |
Geographic strategy splits into two distinct playbooks: defend and expand capacity in North America, and build distribution density everywhere else. The regions that grow fastest are precisely those with the least entrenched shelf presence today.

 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA