Homocysteine Testing Market

Homocysteine Testing Market Research Report By Test Type (Quantitative Tests, Qualitative Tests, Genetic Testing), By Sample Type (Blood Samples, Urine Samples, Plasma Samples), By End User (Hospitals, Diagnostic Laboratories, Research Institutes), By Technology (Enzymatic Assays, Mass Spectrometry, Immunoassays) and By Regional (North America, Europe, South America, Asia Pacific, Middle East and Africa) - Growth & Industry Forecast 2025 To 2035
ID: MRFR/HC/35106-HCR 128 Pages Satyendra Maurya, Rahul Gotadki Last Updated: September 17, 2026
Homocysteine Testing Market
Market Size
Forecast Period2025 - 2035
CAGR (2025 - 2035)10.12%
2024 Market Size$ 1.79 Billion
2025 Market Size$ 1.97 Billion
2035 Market Size$ 5.17 Billion
Key Players
Abbott Laboratories
Roche Diagnostics
Thermo Fisher Scientific
Siemens Healthineers
Danaher Corporation
Bio-Rad Laboratories
Opportunities
  • Advancements in Laboratory Technology
  • Rising Focus on Preventive Healthcare
  • Growing Demand for Personalized Medicine

Homocysteine Testing Market Summary

As per Market Research Future analysis, the Homocysteine Testing Market Size was estimated at 1.789 USD Billion in 2024. The Homocysteine Testing industry is projected to grow from 1.971 USD Billion in 2025 to 5.168 USD Billion by 2035, exhibiting a compound annual growth rate (CAGR) of 10.12% during the forecast period 2025 - 2035

Key Market Trends & Highlights

The Homocysteine Testing Market is experiencing robust growth driven by increasing health awareness and technological advancements.

  • Rising awareness of cardiovascular health is propelling the demand for homocysteine testing, particularly in North America.
  • Technological advancements in testing methodologies are enhancing the accuracy and efficiency of homocysteine assessments.
  • Integration into preventive healthcare strategies is becoming more prevalent, especially in the Asia-Pacific region.
  • The increasing prevalence of cardiovascular diseases and the growing demand for personalized medicine are key drivers of market expansion.

Market Size & Forecast

2024 Market Size 1.789 (USD Billion)
2035 Market Size 5.168 (USD Billion)
CAGR (2025 - 2035) 10.12%

Major Players

Abbott Laboratories (US), Roche Diagnostics (CH), Thermo Fisher Scientific (US), Siemens Healthineers (DE), Danaher Corporation (US), Bio-Rad Laboratories (US), PerkinElmer (US), Ortho Clinical Diagnostics (US), Quidel Corporation (US)
Homocysteine Testing Market Drivers

Advancements in Laboratory Technology

Technological innovations in laboratory testing are transforming the Homocysteine Testing Market. The introduction of more sophisticated and efficient testing methods, such as high-performance liquid chromatography and mass spectrometry, has improved the accuracy and speed of homocysteine level assessments. These advancements not only enhance diagnostic capabilities but also reduce the turnaround time for results, which is crucial for timely clinical decision-making. The market for laboratory testing technologies is expected to grow significantly, with projections indicating a compound annual growth rate of over 7% in the coming years. This growth is likely to further stimulate the demand for homocysteine testing as healthcare facilities seek to adopt cutting-edge technologies.

Rising Focus on Preventive Healthcare

The increasing emphasis on preventive healthcare is a notable driver for the Homocysteine Testing Market. As healthcare systems worldwide shift from reactive to proactive approaches, there is a growing recognition of the importance of early detection and risk assessment. Homocysteine testing plays a critical role in identifying individuals at risk for cardiovascular diseases before symptoms manifest. This proactive approach aligns with public health initiatives aimed at reducing the burden of chronic diseases. The preventive healthcare market is projected to witness substantial growth, potentially reaching USD 4 trillion by 2025. This trend suggests a favorable environment for the expansion of homocysteine testing services.

Growing Demand for Personalized Medicine

The shift towards personalized medicine is influencing the Homocysteine Testing Market significantly. As healthcare evolves, there is a growing emphasis on tailoring treatments to individual patient profiles, which includes genetic predispositions and biomarker levels. Homocysteine testing serves as a valuable tool in this context, allowing healthcare providers to assess cardiovascular risk more accurately. The market for personalized medicine is projected to reach substantial figures, with estimates suggesting it could exceed USD 2 trillion by 2025. This trend indicates a robust potential for homocysteine testing to become an integral part of personalized healthcare strategies, enhancing patient care and outcomes.

Regulatory Support for Diagnostic Testing

Regulatory bodies are increasingly supporting the development and implementation of diagnostic testing, including homocysteine testing, which is positively impacting the Homocysteine Testing Market. Initiatives aimed at improving healthcare quality and patient safety are leading to the establishment of guidelines that encourage routine screening for cardiovascular risk factors. This regulatory support not only enhances the credibility of homocysteine testing but also promotes its integration into standard clinical practice. As healthcare policies evolve to prioritize preventive measures, the market for diagnostic tests is expected to expand, with homocysteine testing likely benefiting from these favorable regulatory changes.

Increasing Prevalence of Cardiovascular Diseases

The rising incidence of cardiovascular diseases is a primary driver for the Homocysteine Testing Market. As cardiovascular conditions continue to affect a significant portion of the population, healthcare providers are increasingly focusing on preventive measures. Elevated homocysteine levels have been linked to a higher risk of heart disease, prompting clinicians to incorporate homocysteine testing into routine assessments. According to recent data, cardiovascular diseases account for approximately 31% of all global deaths, underscoring the urgent need for effective screening methods. This trend is likely to propel the demand for homocysteine testing, as early detection can lead to timely interventions and improved patient outcomes.

Market Segment Insights

By Test Type: Quantitative Tests (Largest) vs. Qualitative Tests (Fastest-Growing)

In the Homocysteine Testing Market, Quantitative Tests hold the largest market share, illustrating their dominance due to proven efficacy and reliability in providing accurate results for clinical assessments. On the other hand, Qualitative Tests, while currently smaller in market share, are emerging rapidly as healthcare providers seek to enhance diagnostic capabilities and patient outcomes with innovative testing methods. As healthcare options become diverser, the demand for various test types is on the rise.

Testing Method: Quantitative Tests (Dominant) vs. Genetic Testing (Emerging)

Quantitative Tests are established as the dominant method in the Homocysteine Testing Market due to their ability to deliver precise measurements that are integral in clinical settings. These tests utilize advanced technologies to quantify homocysteine levels reliably. In contrast, Genetic Testing is an emerging option that provides insights into hereditary factors influencing homocysteine levels. While it currently captures a smaller market share, rising focus on personalized medicine and genetic insights in healthcare contributes to its growth potential. Both testing methods cater to specific needs in the patient management spectrum, yet Quantitative Tests maintain a firm lead driven by routine clinical applications.

By Sample Type: Blood Samples (Largest) vs. Plasma Samples (Fastest-Growing)

In the Homocysteine Testing Market, the distribution of market share among sample types reveals that blood samples hold the largest share due to their widespread acceptance and reliability in clinical testing. Blood samples are preferred for homocysteine measurement as they provide accurate and immediate results, making them the go-to choice for healthcare providers. In contrast, plasma samples are gaining significant traction in the market as a versatile alternative, particularly for specific clinical scenarios and research purposes, thus gradually increasing their share.

Sample Type: Blood (Dominant) vs. Plasma (Emerging)

Blood samples are the dominant segment in the Homocysteine Testing Market, characterized by their extensive use in various healthcare settings for accurate diagnostic results. Their longstanding tradition in medical diagnostics contributes to their preference among healthcare professionals, driving a consistent demand. Conversely, plasma samples have emerged as a noteworthy competitor, particularly in specialized testing and research applications. Their rising popularity can be attributed to advancements in processing and storage techniques that enhance result reliability. As healthcare focuses on precision and personalized medicine, plasma samples are positioning themselves as an innovative alternative, appealing to researchers and clinicians alike.

By End User: Hospitals (Largest) vs. Diagnostic Laboratories (Fastest-Growing)

In the Homocysteine Testing Market, hospitals hold the largest market share among end users due to their high patient intake and the integration of advanced diagnostic technologies. They serve as primary healthcare providers where routine testing for homocysteine levels is essential for managing cardiovascular diseases. On the other hand, diagnostic laboratories are also significant, focusing on specialized testing services that cater to various healthcare providers and patients, thus contributing to their substantial presence in the market.

Hospitals (Dominant) vs. Diagnostic Laboratories (Emerging)

Hospitals are positioned as the dominant end user in the Homocysteine Testing Market, largely owing to their comprehensive healthcare services and the increasing prevalence of cardiovascular diseases that necessitate regular homocysteine level assessments. These establishments are well-equipped with modern diagnostic tools and skilled personnel, enabling them to conduct a higher volume of tests. Conversely, diagnostic laboratories, while still emerging, are rapidly expanding their operations and capabilities. Their focus on precise and timely testing has made them essential partners in the healthcare ecosystem. The rise of point-of-care testing solutions and a growing emphasis on preventive healthcare are propelling the growth of diagnostic laboratories, making them an increasingly vital player in homocysteine testing.

By Technology: Enzymatic Assays (Largest) vs. Mass Spectrometry (Fastest-Growing)

In the Homocysteine Testing Market, the technology segment is primarily dominated by Enzymatic Assays, which have established themselves as the most widely used method due to their simplicity and cost-effectiveness. This segment has garnered significant market share owing to its reliability and ease of integration into various laboratory settings. On the other hand, Mass Spectrometry, while currently a smaller segment, is rapidly gaining traction due to its high accuracy and ability to provide comprehensive results in a single test. The growth outlook for this technology segment is promising, driven by advancements in laboratory technologies and a rise in the prevalence of health conditions linked to elevated homocysteine levels. The increasing focus on personalized medicine and tailored healthcare solutions is pushing laboratories to adopt more sophisticated testing methods like Mass Spectrometry. This shift indicates a transition towards more detailed and exact diagnostics, suggesting that while Enzymatic Assays remain the dominant technology, Mass Spectrometry is emerging as the future of homocysteine testing.

Enzymatic Assays (Dominant) vs. Mass Spectrometry (Emerging)

Enzymatic Assays are currently the dominant force in the Homocysteine Testing Market, primarily due to their user-friendly nature and cost-efficiency, making them accessible to a broader range of laboratories. Their straightforward protocols and rapid results satisfy the high throughput needs of clinical laboratories. On the other hand, Mass Spectrometry is recognized as the emerging technology, offering advanced capabilities such as higher sensitivity and specificity than traditional methods. Its potential for comprehensive profiling and simultaneous analysis of multiple biomarkers sets it apart. Despite its higher operational costs and complexity, the increasing demand for precise diagnostics positions Mass Spectrometry as a key player in the future of homocysteine testing.

Get more detailed insights about Homocysteine Testing Market

Regional Insights

North America : Leading Innovation and Demand

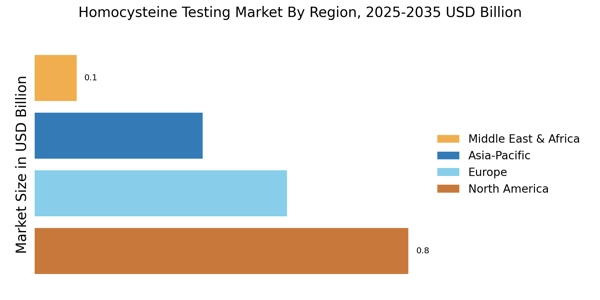
North America is the largest market for homocysteine testing, accounting for approximately 45% of the global share. The region's growth is driven by increasing awareness of cardiovascular diseases and the rising prevalence of vitamin B deficiencies. Regulatory support from agencies like the FDA further catalyzes market expansion, ensuring the availability of advanced testing solutions. The demand for early diagnosis and preventive healthcare is also on the rise, contributing to market growth. The United States dominates the North American market, with significant contributions from Canada. Key players such as Abbott Laboratories, Thermo Fisher Scientific, and Roche Diagnostics are actively involved in product development and innovation. The competitive landscape is characterized by strategic partnerships and collaborations aimed at enhancing testing accuracy and efficiency. This focus on innovation positions North America as a leader in the homocysteine testing market.

Europe : Regulatory Support and Growth

Europe is the second-largest market for homocysteine testing, holding approximately 30% of the global market share. The region benefits from stringent regulatory frameworks that promote high-quality testing standards. Increased government initiatives aimed at improving healthcare infrastructure and rising awareness about the importance of early disease detection are key growth drivers. Countries like Germany and the UK are leading the market, supported by favorable reimbursement policies and healthcare investments. Germany is the largest market in Europe, followed closely by the UK and France. The competitive landscape features major players such as Siemens Healthineers and Roche Diagnostics, which are investing in research and development to enhance testing technologies. The presence of established healthcare systems and a growing focus on preventive healthcare further bolster the market. The European Medicines Agency emphasizes the importance of accurate testing in disease management, ensuring a robust regulatory environment.

Asia-Pacific : Rapidly Growing Healthcare Sector

Asia-Pacific is witnessing rapid growth in the homocysteine testing market, driven by increasing healthcare expenditure and rising awareness of chronic diseases. The region is projected to hold around 20% of the global market share by 2025. Countries like China and India are experiencing significant demand due to their large populations and growing middle class. Government initiatives aimed at improving healthcare access and quality are also contributing to market expansion. China is the largest market in the region, followed by India and Japan. The competitive landscape is evolving, with both local and international players like Danaher Corporation and Bio-Rad Laboratories expanding their presence. The focus on innovative testing solutions and partnerships with healthcare providers is enhancing market dynamics. As the region continues to invest in healthcare infrastructure, the demand for homocysteine testing is expected to rise significantly.

Middle East and Africa : Emerging Market Potential

The Middle East and Africa region is gradually emerging in the homocysteine testing market, currently holding about 5% of the global share. The growth is primarily driven by increasing awareness of health issues and the rising prevalence of lifestyle-related diseases. Government initiatives aimed at improving healthcare access and quality are also contributing to market development. Countries like South Africa and the UAE are leading the market, supported by investments in healthcare infrastructure. South Africa is the largest market in the region, with the UAE following closely. The competitive landscape is characterized by a mix of local and international players, including Ortho Clinical Diagnostics and Quidel Corporation. The focus on enhancing testing capabilities and increasing public awareness about the importance of early diagnosis is expected to drive market growth. As healthcare systems evolve, the demand for homocysteine testing is anticipated to increase significantly.

Homocysteine Testing Market Regional Image

Key Players and Competitive Insights

The Homocysteine Testing Market is currently characterized by a dynamic competitive landscape, driven by increasing awareness of cardiovascular diseases and the role of homocysteine as a biomarker. Key players such as Abbott Laboratories (US), Roche Diagnostics (CH), and Thermo Fisher Scientific (US) are strategically positioned to leverage innovation and technological advancements. Abbott Laboratories (US) focuses on enhancing its diagnostic capabilities through continuous product development, while Roche Diagnostics (CH) emphasizes partnerships to expand its market reach. Thermo Fisher Scientific (US) is investing in digital transformation to streamline operations and improve customer engagement, collectively shaping a competitive environment that prioritizes innovation and strategic collaborations.In terms of business tactics, companies are increasingly localizing manufacturing to reduce costs and enhance supply chain efficiency. The market structure appears moderately fragmented, with several players vying for market share. However, the collective influence of major companies like Siemens Healthineers (DE) and Danaher Corporation (US) is notable, as they implement strategies that enhance their competitive positioning and operational effectiveness.

In August Siemens Healthineers (DE) announced the launch of a new homocysteine testing platform that integrates advanced AI algorithms for improved accuracy and speed. This strategic move is significant as it not only enhances the company's product portfolio but also positions Siemens as a leader in the integration of AI in diagnostic testing, potentially attracting a broader customer base.

In September Danaher Corporation (US) completed the acquisition of a biotechnology firm specializing in biomarker discovery, which includes homocysteine testing technologies. This acquisition is pivotal as it allows Danaher to expand its capabilities in the diagnostics sector, thereby enhancing its competitive edge and fostering innovation in homocysteine testing methodologies.

In July Roche Diagnostics (CH) entered into a strategic partnership with a leading telehealthprovider to offer remote homocysteine testing services. This collaboration is indicative of the growing trend towards digital health solutions, allowing Roche to tap into new markets and improve accessibility for patients, which is increasingly important in today's healthcare landscape.

As of October the competitive trends in the Homocysteine Testing Market are heavily influenced by digitalization, sustainability, and the integration of artificial intelligence. Strategic alliances are becoming more prevalent, enabling companies to enhance their technological capabilities and market presence. Looking ahead, competitive differentiation is likely to evolve from traditional price-based competition to a focus on innovation, technological advancements, and supply chain reliability, as companies strive to meet the growing demands of healthcare providers and patients.

Key Companies in the Homocysteine Testing Market include

Recent Industry Developments

The Homocysteine Testing Market has been experiencing notable developments recently, characterized by innovations and strategic movements among key players. Companies like Danaher Corporation and Siemens Healthineers are enhancing their product offerings with advanced technologies aimed at improving the accuracy and efficiency of homocysteine testing. Quest Diagnostics and Abbott Laboratories have also been actively involved in expanding their testing capabilities, focusing on personalized medicine approaches. A significant trend is the increasing collaborations and partnerships; for example, Thermo Fisher Scientific has been engaged in enhancing its diagnostic services through mergers that enhance its research capabilities. 

Additionally, BioRad Laboratories and Roche Diagnostics are reported to be investing in research and development to leverage biomarker testing. The growth in market valuation for these companies is attributed to the rising prevalence of cardiovascular diseases, which drives demand for effective homocysteine testing. Furthermore, the emphasis on preventative healthcare and early diagnosis is attracting more investments, positioning organizations like Luminex Corporation and PerkinElmer to potentially expand their market share in response to the evolving healthcare landscape. Overall, current activities in the market suggest a dynamic environment with a sustained focus on innovation and growth.

Future Outlook

Homocysteine Testing Market Future Outlook

The Homocysteine Testing Market is projected to grow at a 10.12% CAGR from 2025 to 2035, driven by increasing awareness of cardiovascular health and advancements in testing technologies.

New opportunities lie in:

  • Development of point-of-care testing devices for rapid results
  • Integration of telehealth services for remote monitoring
  • Expansion of partnerships with healthcare providers for comprehensive testing solutions

By 2035, the market is expected to be robust, reflecting significant advancements and increased adoption.

Market Segmentation

Homocysteine Testing Market End User Outlook

  • Hospitals
  • Diagnostic Laboratories
  • Research Institutes

Homocysteine Testing Market Test Type Outlook

  • Quantitative Tests
  • Qualitative Tests
  • Genetic Testing

Homocysteine Testing Market Technology Outlook

  • Enzymatic Assays
  • Mass Spectrometry
  • Immunoassays

Homocysteine Testing Market Sample Type Outlook

  • Blood Samples
  • Urine Samples
  • Plasma Samples

Report Scope

MARKET SIZE 2024 1.789(USD Billion)
MARKET SIZE 2025 1.971(USD Billion)
MARKET SIZE 2035 5.168(USD Billion)
COMPOUND ANNUAL GROWTH RATE (CAGR) 10.12% (2025 - 2035)
REPORT COVERAGE Revenue Forecast, Competitive Landscape, Growth Factors, and Trends
BASE YEAR 2024
Market Forecast Period 2025 - 2035
Historical Data 2019 - 2024
Market Forecast Units USD Billion
Key Companies Profiled Abbott Laboratories (US), Roche Diagnostics (CH), Thermo Fisher Scientific (US), Siemens Healthineers (DE), Danaher Corporation (US), Bio-Rad Laboratories (US), PerkinElmer (US), Ortho Clinical Diagnostics (US), Quidel Corporation (US)
Segments Covered Test Type, Sample Type, End User, Technology, Regional
Key Market Opportunities Integration of advanced biomarkers and point-of-care testing enhances accessibility in the Homocysteine Testing Market.
Key Market Dynamics Rising demand for early cardiovascular disease detection drives innovation in homocysteine testing technologies and methodologies.
Countries Covered North America, Europe, APAC, South America, MEA

Frequently Asked Questions

What is the projected market valuation of the Homocysteine Testing Market by 2035?

The Homocysteine Testing Market is projected to reach a valuation of 5.168 USD Billion by 2035.

What was the market valuation of the Homocysteine Testing Market in 2024?

In 2024, the market valuation of the Homocysteine Testing Market was 1.789 USD Billion.

What is the expected CAGR for the Homocysteine Testing Market during the forecast period 2025 - 2035?

The expected CAGR for the Homocysteine Testing Market during the forecast period 2025 - 2035 is 10.12%.

Which companies are considered key players in the Homocysteine Testing Market?

Key players in the Homocysteine Testing Market include Abbott Laboratories, Roche Diagnostics, and Thermo Fisher Scientific.

What are the main test types in the Homocysteine Testing Market and their projected valuations?

The main test types include Quantitative Tests projected to reach 2.584 USD Billion, Qualitative Tests at 1.536 USD Billion, and Genetic Testing at 1.048 USD Billion by 2035.

How do blood, urine, and plasma samples compare in the Homocysteine Testing Market?

Blood samples are projected to reach 1.872 USD Billion, while urine and plasma samples are expected to reach 0.979 USD Billion and 1.317 USD Billion, respectively, by 2035.

What is the projected market size for hospitals as end users in the Homocysteine Testing Market?

Hospitals are projected to account for 2.584 USD Billion in the Homocysteine Testing Market by 2035.

What technologies are utilized in the Homocysteine Testing Market and their future valuations?

Technologies such as Immunoassays are projected to reach 2.154 USD Billion, alongside Enzymatic Assays and Mass Spectrometry both at 1.507 USD Billion by 2035.

What role do diagnostic laboratories play in the Homocysteine Testing Market?

Diagnostic laboratories are expected to reach a market size of 1.516 USD Billion by 2035, indicating their significant role in the sector.

How does the growth of the Homocysteine Testing Market reflect on public health initiatives?

The growth of the Homocysteine Testing Market may reflect increasing public health initiatives aimed at managing cardiovascular health and related conditions.

Author
Author Author Profile Satyendra Maurya LinkedIn Research Analyst
An accomplished research analyst with high proficiency in market forecasting, data visualization, competitive benchmarking, and others. He holds a pronounced track record in research and consulting projects for sectors such as life sciences, medical devices, and healthcare IT. His capabilities in qualitative and quantitative analysis have resulted in positive client outcomes. Working on niche market trends, opportunities, sales, and forecasted value is part of his skill set.
Co-Author Co-Author Profile Rahul Gotadki LinkedIn Research Manager
He holds an experience of about 9+ years in Market Research and Business Consulting, working under the spectrum of Life Sciences and Healthcare domains. Rahul conceptualizes and implements a scalable business strategy and provides strategic leadership to the clients. His expertise lies in market estimation, competitive intelligence, pipeline analysis, customer assessment, etc.

Research Approach

Secondary Research

The secondary research process involved comprehensive analysis of regulatory databases, peer-reviewed medical journals, clinical publications, and authoritative health organizations. Key sources included the US Food & Drug Administration (FDA), Centers for Medicare & Medicaid Services (CMS), Centers for Disease Control and Prevention (CDC), National Institutes of Health (NIH), National Center for Biotechnology Information (NCBI/PubMed), National Heart, Lung, and Blood Institute (NHLBI), European Medicines Agency (EMA), European Centre for Disease Prevention and Control (ECDC), World Health Organization (WHO) Global Health Observatory, Clinical and Laboratory Standards Institute (CLSI), International Federation of Clinical Chemistry and Laboratory Medicine (IFCC), American Heart Association (AHA), American Association for Clinical Chemistry (AACC), College of American Pathologists (CAP), EU Eurostat Health Database, OECD Health Statistics, National Health Service (NHS) England, Japan Ministry of Health, Labour and Welfare (MHLW), China National Health Commission, India Ministry of Health and Family Welfare, and national health ministry reports from key markets.

Cardiovascular disease prevalence statistics, clinical validation studies for enzymatic assays and mass spectrometry techniques, regulatory approval data for diagnostic devices, reimbursement policies, laboratory testing volume trends, and competitive landscape analysis for quantitative, qualitative, and genetic testing technologies were all gathered from these sources.

Primary Research

In order to gather both qualitative and quantitative insights, supply-side and demand-side stakeholders were interviewed during the primary research process. CEOs, VPs of Product Development, heads of regulatory affairs, R&D directors, and commercial directors from clinical chemistry analyzer OEMs, reagent suppliers, and in-vitro diagnostic (IVD) manufacturers were examples of supply-side sources. Chief pathologists, laboratory directors, clinical biochemists, procurement managers from hospitals and diagnostic labs, cardiologists, and research scientists from academic medical centers and contract research organizations were examples of demand-side sources. Primary research verified product pipeline timelines for point-of-care testing devices, obtained information on clinical adoption patterns, pricing strategies for reagent contracts, and reimbursement dynamics for cardiovascular risk assessment panels, and validated market segmentation across test types (quantitative, qualitative, genetic), sample types (blood, urine, plasma), technologies (enzymatic assays, mass spectrometry, immunoassays), and end users (hospitals, diagnostic labs, and research institutes.

Primary Respondent Breakdown:

By Designation: C-level Executives (28%), Director Level (32%), Managers & Others (40%)

By Region: North America (32%), Europe (30%), Asia-Pacific (28%), Rest of World (10%)

Market Size Estimation

Global market valuation was derived through revenue mapping and testing volume analysis. The methodology included:

Identification of 35+ key diagnostic manufacturers and reagent suppliers across North America, Europe, Asia-Pacific, and Latin America

Product mapping across enzymatic assay kits, mass spectrometry systems, immunoassay platforms, and point-of-care testing devices

Analysis of reported and modeled annual revenues specific to homocysteine testing portfolios and cardiovascular biomarker panels

Coverage of manufacturers representing 75-80% of global market share in 2024

Extrapolation using bottom-up (test volume × ASP by country/region) and top-down (manufacturer revenue validation) approaches to derive segment-specific valuations for quantitative tests, qualitative tests, genetic testing, and technology-specific revenue breakdowns

Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.