Geo Satellite Market (2026 - 2035)

Geo Satellite Market Size, Share, Industry Trend & Analysis Research Report: By Satellite Type (Communication Satellites, Earth Observation Satellites, Weather Satellites, Surveillance and Intelligence Satellites, Others), By Satellite Mass (Small, Medium, Large), By Propulsion (Electric Propulsion, Chemical Propulsion, Hybrid Propulsion), By End User (Commercial, Government and Civil, Military), By Region (North America, Europe, Asia-Pacific, South America, Middle East & Africa) - Forecast to 2035
ID: MRFR/AD/21232-HCR 128 Pages Shubham Munde, Sejal Akre Last Updated: November 12, 2026
Geo Satellite Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)14.5%
2025 Market SizeUSD 4.32 Billion
2035 Market SizeUSD 15.66 Billion
Key Players
Airbus Defence and Space
Thales Alenia Space
Boeing
Maxar Space Systems
Lockheed Martin
Northrop Grumman
Opportunities
  • Sovereign Satellites for Emerging Markets
  • Capacity-as-a-Service and Leasing Models
  • Refueling and Life Extension

Geo Satellite Market Summary

The GEO satellite market was valued at USD 4.32 billion in 2025 and is forecast to reach USD 4.63 billion in 2026 before climbing to USD 15.66 billion by 2035, a CAGR of 14.5% over 2026–2035. Two catalysts anchor the near-term order book: the US Space Force's Protected Tactical SATCOM-Global (PTS-G) prototype program, which is pulling maneuverable military platforms into geostationary orbit [3], and EUMETSAT's Meteosat Third Generation constellation, which secures European weather observation from GEO into the 2040s [1].

Platform design across the GEO satellite market is changing faster than at any point in two decades. Fixed, analog transponder payloads built to a single coverage plan are giving way to digital, reconfigurable payloads that let operators move beams and bandwidth after launch. Chemical apogee engines are being replaced by Hall-effect and gridded-ion thrusters that release 400–700 kg of mass for revenue-generating payload. Capital is following the shift: ReOrbit and SLI signed a USD 0.17 billion agreement in March 2026 for two next-generation GEO communication satellites delivered on lease terms [24].

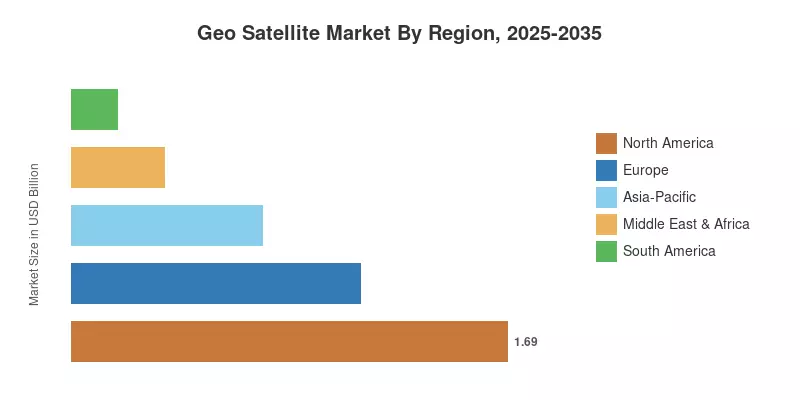
North America holds the leading position with a 39.2% share in 2025, supported by defense procurement and the largest concentration of fleet operators and prime integrators. Asia-Pacific is the fastest-growing region at a 17.1% CAGR as China, India, and Southeast Asian governments commission sovereign communication and meteorological satellites. Europe ranks second at USD 1.12 billion, driven by institutional programs and a dense manufacturing base in France, Germany, and Italy. Over the forecast window, buyers will reward suppliers that shorten build cycles without giving up the persistent coverage that only GEO delivers.

Key Report Takeaways

• By Satellite Type

  • Communication Satellites held 57.6% of the GEO satellite market in 2025 on the strength of long-term transponder leases and direct-to-home broadcasting.
  • Earth Observation Satellites are set to expand at a 16.5% CAGR through 2035 as continuous regional monitoring replaces periodic revisits.
  • Weather Satellites generated USD 0.47 billion in 2025 under long-cycle national meteorological programs.

• By Satellite Mass

  • Large platforms captured 49.2% of 2025 revenue because bigger buses carry more transponders per launch.
  • Medium satellites are the fastest-growing mass class at an 18.5% CAGR, helped by leasing and shorter procurement cycles.

• By Propulsion

  • Electric Propulsion accounted for 63.9% of the GEO satellite market in 2025 and also leads in growth.
  • Chemical Propulsion generated USD 1.04 billion, retained for missions where orbit-raising speed matters.

• By End User

  • Commercial operators represented 55.4% of GEO satellite market demand in 2025, led by broadcast, enterprise backhaul, and maritime connectivity
  • Military buyers are forecast to grow at a 16.2% CAGR as protected tactical communications move to maneuverable platforms

• By Region

  • North America led the GEO satellite market with a 39.2% share in 2025
  • Asia-Pacific is expected to post a 17.1% CAGR, the highest of any region
  • Europe generated USD 1.12 billion, anchored by EUMETSAT and ESA-funded programs

Market Size and Forecast (2021–2035)

Market Research Future sized the GEO satellite market from a bottom-up count of satellite contracts by platform class, payload type, and customer, priced at award value and allocated across build schedules. Operator filings, agency procurement notices, and manufacturer order books were then used to validate totals top-down, with the series triangulated against launch manifests and public budget lines [5][7][12].
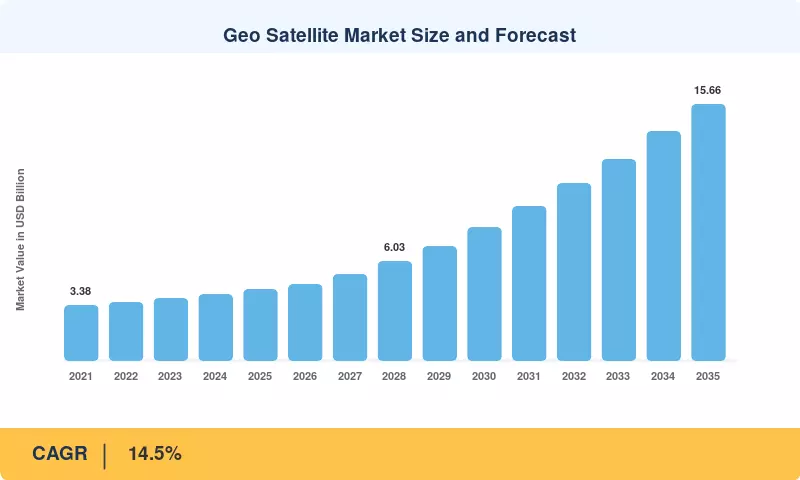
Geo Satellite Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Reconfigurable digital payloads +2.8% Global Medium-term (2–4 yr)
Electric propulsion mass savings +2.5% Global Short-term (≤2 yr)
Protected military and sovereign SATCOM +2.4% North America, Europe Medium-term (2–4 yr)
Persistent weather and Earth observation +1.9% Europe, North America, Asia-Pacific Long-term (≥4 yr)
Medium and small platforms with leasing +1.7% Global Medium-term (2–4 yr)
In-orbit servicing and life extension +1.2% North America, Europe Long-term (≥4 yr)

Reconfigurable Digital Payloads

A GEO spacecraft is designed for a 15-year life, yet traffic patterns now shift in months. Airbus's OneSat and Thales Alenia Space's Inspire platforms answer that mismatch with payloads that can be re-pointed and re-channelized in orbit [12][13]. Operators gain the ability to move capacity from a saturated maritime corridor to an airline route without a new satellite. We assign this driver the largest weight, at +2.8% of CAGR.

Electric Propulsion Mass Savings

Electric systems free 400–700 kg of structural mass that can be converted into transponders or a lighter, cheaper launch. Suppliers such as OHB SE, which agreed to supply six electric propulsion systems for SWISSto12's HummingSat platform, are widening the vendor base [19][20]. With 63.9% of 2025 revenue already on electric platforms, the remaining chemical-only holdouts are mostly defense missions. The effect is near-term because most bus designs now in production already assume all-electric stationkeeping.

Protected Military and Sovereign SATCOM

Defense ministries want communications that survive jamming and can be moved when threats change. The US Space Force's PTS-G program awarded prototype contracts to several manufacturers in 2025 for smaller, maneuverable GEO satellites carrying the Protected Tactical Waveform [3]. Viasat's August 2026 selection of Rocket Lab to build a bus for PTS-G Swarm 1 shows new entrants winning work traditionally held by primes [23]. European sovereign programs follow the same logic and support a +2.4% contribution.

Persistent Weather and Earth Observation

GEO sensors watch the same area continuously, which periodic low-orbit revisits cannot match for storm tracking or air-quality monitoring. ESA's Sentinel-4 instrument flies on MTG-S1, commissioned in 2026 for hourly atmospheric observation over Europe and northern Africa [1][2]. NOAA's GeoXO program extends the same model to the Americas into the 2050s [17]. Earth Observation Satellites carry a 16.5% CAGR, but long procurement cycles push most of the revenue impact past 2029.

Medium and Small Platforms with Leasing

Smaller operators often cannot fund a USD 0.3–0.4 billion large-class satellite. Medium platforms trade some transponder capacity for faster delivery and lower capital commitment, and leasing structures remove the upfront burden altogether [24]. The ReOrbit–SLI agreement, valued at USD 0.17 billion for two satellites, illustrates the model. This driver brings regional telecom operators and governments into the buyer pool and supports the 18.5% CAGR forecast for Medium satellites.

In-Orbit Servicing and Life Extension

A servicer may dock with an operational GEO satellite and maintain its functionality for years, as demonstrated by Northrop Grumman's SpaceLogistics Mission Extension Vehicles [11]. Hydrazine refueling has been discovered by Astroscale as a way to enhance fleet economics, and in November 2025, Infinite Orbits and SES inked a commercial life-extension mission [22][25]. Over time, servicing generates a new revenue stream and delays some replacement orders, resulting in a +1.2% contribution.

Restraints Impact Analysis

Restraint impacts are directional estimates of downward pressure on the forecast CAGR. They interact with one another and with the drivers above, so they should not be summed or subtracted from the headline rate.

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
Competition from LEO broadband constellations −2.6% Global Short-term (≤2 yr)
Launch and insurance cost volatility −1.4% Global Short-term (≤2 yr)
Long build cycles and component bottlenecks −1.1% Global Medium-term (2–4 yr)
Spectrum and orbital slot coordination −0.8% Global Long-term (≥4 yr)
RF power and aperture limits on small platforms −0.7% Global Medium-term (2–4 yr)

Competition from LEO Broadband Constellations

Low-orbit networks now offer consumer and enterprise broadband with latency GEO cannot match. That pressure is clearest in the broadband portion of the GEO satellite market, where wholesale prices have fallen, and some operators have deferred replacement orders [10]. Eutelsat's combination with OneWeb shows GEO incumbents buying their way into multi-orbit service rather than competing head-on. We estimate a −2.6% drag, concentrated in the next two years.

Launch and Insurance Cost Volatility

Insurance prices in the industry can be affected by a single launch failure or in-orbit anomaly. After a number of years of losses, underwriters have pulled out of the space industry, leaving operators with either increased premiums or partial self-insurance [7]. This affects newcomers the most, accounting for an estimated −1.4% drag.

Long Build Cycles and Component Bottlenecks

Large GEO satellites typically take three years or more from contract to launch. Shortages in radiation-hardened electronics, traveling-wave tube amplifiers, and qualified test capacity have extended some schedules further [12]. Each slip delays revenue recognition, weighing roughly −1.1% on the forecast.

Spectrum and Orbital Slot Coordination

Every GEO position and frequency assignment must be filed and coordinated through the ITU Radio Regulations, a process that can take years when neighboring administrations object. Crowded arcs over Asia and the Middle East raise the cost of securing usable slots for new national programs. The effect is modest, at −0.8%, but persistent across the forecast.

RF Power and Aperture Limits on Small Platforms

At 36,000 kilometers, small buses are unable to match the radio-frequency power or antenna size of large satellites. This restricts small GEO satellites to specialized federal or regional tasks and reduces throughput [20]. This gap is closing because deployable reflector work is supported by ESA, but the constraint still prevents about −0.7% of possible increase.

Geo Satellite Market Opportunities

Sovereign Satellites for Emerging Markets

Governments across Africa, Southeast Asia, and Latin America want national communication capacity without depending on foreign operators. Medium platforms and lease-to-own financing bring a first national GEO satellite within reach of mid-sized budgets. Egypt, Saudi Arabia, and the Philippines are typical buyers of this kind, and the opportunity is strongest where terrestrial backhaul is thin.

Capacity-as-a-Service and Leasing Models

Instead of owning satellites, operators are purchasing capacity under long-term service agreements. As in the ReOrbit–SLI arrangement, manufacturers who lease the asset while retaining ownership are able to monetize capacity data across numerous clients and generate recurring revenue [24]. The fastest-growing mass class, medium satellites, are a good fit for this paradigm.

Refueling and Life Extension

Hundreds of operating GEO satellites approach end of fuel rather than end of hardware life. Refueling, mission-extension pods, and relocation services can add years of revenue to these assets [11][22]. Servicing providers that standardize docking interfaces with new satellite designs stand to lock in long-term contracts.

Hosted Payloads for Climate and Air-Quality Monitoring

Commercial GEO communication satellites have spare mass and power that can host government sensors. Climate monitoring mandates and the success of Sentinel-4 strengthen the case for hosted atmospheric instruments [2].

Multi-Orbit Network Integration

Enterprise and government customers increasingly want one service that blends GEO coverage with low-orbit latency. GEO operators that integrate terminals and network management across orbits can defend their customer base instead of losing it to low-orbit entrants [8][10]. SES's acquisition of Intelsat created a fleet large enough to anchor such offerings.

Geo Satellite Market Future Outlook

Autonomous Payload and Fleet Operations

On-board processors will let satellites re-allocate beams automatically as traffic changes, cutting the need for ground-directed reconfiguration. Operators running dozens of satellites will use machine-learning tools to schedule capacity, predict anomalies, and plan stationkeeping. Industry estimates value the global space economy at well over USD 0.5 trillion, and automation will decide which fleets stay cost-competitive in the GEO satellite market [5].

Platform Economics and Smaller Buses

The decade will split the GEO satellite market between very large high-capacity platforms for anchor operators and medium or small buses for regional and government users. Shorter build times will let buyers order closer to demand, lowering the risk that a satellite arrives mismatched to its market.

Propulsion and Servicing Supercycle

All-electric designs will become the default for commercial GEO buses, while refueling and life-extension services mature into a recurring market. Satellites will increasingly carry docking fixtures and refueling ports at launch, building servicing into the business case from day one [11][22].

Orbital Sustainability and Debris Governance

Operators must reserve propellant to move retired satellites into graveyard orbits above GEO, and international guidelines on long-term sustainability are tightening expectations [6][18]. ESA's annual environmental reporting tracks compliance with disposal rules in the GEO protected region. Fleets that can demonstrate reliable end-of-life disposal will find insurance and spectrum approvals easier to secure [6].

Regional Market Share Analysis

Region Key Metric (2025) Primary Investment Themes
North America 39.2% share Protected military SATCOM, servicing, fleet replacement
Europe USD 1.12 Billion Meteorological programs, digital payloads, consolidation
Asia-Pacific 17.1% CAGR (2026–2035) Sovereign communications, national weather satellites
South America 4.1% share Rural connectivity, broadcast replacement
Middle East & Africa USD 0.36 Billion Sovereign SATCOM, mobile satellite services
Total USD 4.32 Billion —

Regional demand in the GEO satellite market follows defense budgets, institutional space spending, and the location of fleet operators. North America leads on share, Europe on institutional programs, and Asia-Pacific on growth.

North America

Country Key Metric (2025) Key Driver
US 86.5% of regional share PTS-G, GeoXO, commercial fleet replacement
Canada USD 0.15 Billion Arctic and northern connectivity
Mexico CAGR 13.8% (2026–2035) Government communications satellite renewal

The United States dominates because it combines the largest military space budget with the most active satellite servicing industry. Space Systems Command's PTS-G awards and NOAA's GeoXO weather program give manufacturers a multi-year government pipeline, while commercial operators continue to replace aging broadcast fleets [3][17]. Canada's demand centers on Arctic coverage.

Europe

Country Key Metric (2025) Key Driver
Germany USD 0.19 Billion Bus manufacturing and electric propulsion supply
UK 15.2% of regional share Mobile satellite services and operator headquarters
France 23.8% of regional share Large-platform manufacturing and digital payloads
Italy CAGR 13.9% (2026–2035) Defense SATCOM and payload electronics
Spain USD 0.07 Billion Government and military communications
Nordic Countries 4.1% of regional share Arctic coverage and ground infrastructure
Russia USD 0.11 Billion Domestic broadcast and government fleets
Rest of Europe 13.4% of regional share Small-GEO entrants and component suppliers

France and Germany host most of Europe's GEO manufacturing capacity, and the October 2025 agreement by Airbus, Thales, and Leonardo to combine their space businesses could reshape how institutional contracts are awarded [21]. EUMETSAT's MTG program and ESA's telecom funding keep a steady flow of weather and communications work across member states [1][2]. Switzerland's SWISSto12 and Luxembourg-based SES add commercial depth beyond the largest manufacturing countries.

Asia-Pacific

Country Key Metric (2025) Key Driver
China 41.5% of regional share State communication and meteorological constellations
India CAGR 19.6% (2026–2035) GSAT series and private space reforms
Japan USD 0.17 Billion Digital payloads and quasi-zenith augmentation
South Korea 7.9% of regional share Military communications and GEO-KOMPSAT
ASEAN USD 0.08 Billion National connectivity programs
Rest of Asia-Pacific CAGR 15.2% (2026–2035) Australian sovereign SATCOM and Pacific coverage

China builds most of its GEO satellites domestically, which keeps its share high and insulates it from export restrictions. India is the fastest grower in the region after NSIL's demand-driven GSAT-N2 mission demonstrated about 48 Gbps of Ka-band capacity [14]. Japan's Mitsubishi Electric is developing digital payload platforms for both domestic and export customers.

South America

Country Key Metric (2025) Key Driver
Brazil 61.0% of regional share Defense and strategic communications, rural broadband
Argentina CAGR 12.6% (2026–2035) ARSAT fleet renewal
Rest of South America USD 0.04 Billion Broadcast and government connectivity

Brazil accounts for most regional demand because its defense ministry and telecom operators both depend on GEO coverage across the Amazon basin. Argentina's state operator has a domestic manufacturing partner, which supports steady replacement orders. Smaller countries tend to lease capacity rather than buy satellites.

Middle East & Africa

Country Key Metric (2025) Key Driver
Saudi Arabia USD 0.09 Billion Arabsat fleet renewal and space strategy
UAE 27.5% of regional share Mobile satellite services and sovereign SATCOM
South Africa CAGR 12.9% (2026–2035) Earth observation and regional broadcast
Egypt USD 0.03 Billion National communication satellites
Rest of MEA 23.0% of regional share First national satellites in sub-Saharan Africa

The UAE leads regional activity through Space42, whose Thuraya 4 satellite launched in January 2025 to renew mobile satellite services across Europe, the Middle East, Africa, and Asia [15]. Across sub-Saharan Africa, governments are evaluating first national GEO satellites, often on financed or leased terms.

Geo Satellite Market By Region, 2025-2035

Geo Satellite Market Segmentation

By Satellite Type

Segment Key Metric (2025) Primary Demand Driver
Communication Satellites 57.6% share Transponder leases, broadcasting, cellular backhaul
Earth Observation Satellites 16.5% CAGR (2026–2035) Continuous regional monitoring for defense and climate
Weather Satellites USD 0.47 Billion National meteorological programs
Surveillance and Intelligence Satellites 9.8% share Persistent military monitoring
Others 5.3% share Navigation augmentation and experimental payloads

Within the GEO satellite market, Communication Satellites remain the revenue anchor because long-term leases and direct-to-home contracts keep demand steady even as low-orbit networks expand. Earth Observation Satellites are growing fastest, since a fixed GEO vantage point delivers continuous coverage for storm tracking, crop monitoring, and defense surveillance. Weather Satellites, Surveillance and Intelligence Satellites, and Others serve narrower but durable government needs.

By Satellite Mass

Segment Key Metric (2025) Primary Demand Driver
Small USD 0.61 Billion Rapid-deployment government missions
Medium 18.5% CAGR (2026–2035) Faster procurement and leasing structures
Large 49.2% share High-capacity commercial services

Large platforms lead the GEO satellite market by mass class because they spread launch and insurance costs across more transponders. Medium satellites are growing fastest as operators accept less capacity in exchange for quicker delivery and financing flexibility, a trend the ReOrbit–SLI agreement reflects [24]. Small platforms serve maneuverable government missions but are held back by RF power and aperture limits at GEO altitude.

By Propulsion

Segment Key Metric (2025) Primary Demand Driver
Electric Propulsion 63.9% share Mass savings and higher payload capacity
Chemical Propulsion USD 1.04 Billion Fast orbit raising for military missions
Hybrid Propulsion 12.0% share Balance of speed and efficiency

Electric Propulsion leads the GEO satellite market on both share and growth, as Hall-effect and gridded-ion thrusters have become standard for commercial stationkeeping. Chemical Propulsion persists where a 4–6 month electric orbit-raising period is unacceptable, mainly for defense satellites. Hybrid Propulsion offers a middle path for time-sensitive government programs and for satellites that must reserve propellant for graveyard-orbit disposal.

By End User

Segment Key Metric (2025) Primary Demand Driver
Commercial 55.4% share Broadcast, enterprise backhaul, mobility services
Government and Civil USD 1.09 Billion Meteorology, science, and public connectivity
Military 16.2% CAGR (2026–2035) Protected and anti-jam communications

Commercial operators form the largest end-user group in the GEO satellite market, buying capacity for broadcast, maritime, aviation, and enterprise networks. Military demand is growing fastest as programs such as PTS-G move protected communications onto smaller, maneuverable satellites [3]. Government and Civil buyers provide stable baseline demand through weather, science, and public-service connectivity programs.

Competitive Benchmarking

The GEO satellite market is moderately consolidated, with an estimated Herfindahl-Hirschman Index near 1,250 and the top five manufacturers holding roughly 60–65% of revenue. Large aerospace primes dominate large-class buses, while specialists such as OHB SE, SWISSto12, and ReOrbit compete on medium and small platforms with shorter build cycles. Competition is moving from bus design alone toward integrated offerings that combine platforms, digital payloads, and servicing.

Company Est. Revenue Share Range Key Offerings for GEO Satellite Market Strategic Positioning
Airbus Defence and Space ~14–17% OneSat reconfigurable platform, Eurostar Neo Digital payload leader for commercial operators
Thales Alenia Space ~12–15% Space Inspire, Spacebus Neo Software-defined payloads and institutional programs
Boeing ~10–13% 702 platform family Large-platform and US government missions
Maxar Space Systems ~9–12% 1300-class bus Commercial communication platforms
Lockheed Martin ~8–11% LM 2100 and LM 400 buses Missile warning and military GEO
Northrop Grumman ~7–10% GEOStar buses, Mission Extension Vehicles Servicing pioneer and defense programs
Mitsubishi Electric ~4–6% DS2000 bus, digital payloads Japanese government and export platforms
OHB SE ~2–4% SmallGEO bus, electric propulsion systems Mid-size European platforms
Rocket Lab ~1–3% GEO-capable spacecraft buses New entrant in PTS-G programs
SWISSto12 ~1–2% HummingSat small GEO platform Compact GEO for niche operators
ReOrbit <1% Software-defined medium GEO satellites Leasing-based delivery model
Astroscale <1% LEXI life-extension vehicle, refueling In-orbit servicing specialist

Recent News & Developments

  • Viasat (May 2023): Completed its roughly USD 7.3 billion acquisition of Inmarsat, combining two of the largest GEO fleets and strengthening its position in mobility and government services [9]
  • ISRO/NSIL (November 2024): Launched GSAT-N2 (GSAT-20), a Ka-band high-capacity satellite with about 48 Gbps of throughput, expanding India's demand-driven commercial capacity [14]
  • Astranis (December 2024): Launched four MicroGEO satellites on a single mission, demonstrating that small dedicated GEO satellites can be deployed in batches [16]
  • Space42 (January 2025): Launched Thuraya 4, renewing UAE-based mobile satellite services across Europe, the Middle East, Africa, and Asia [15]
  • EUMETSAT/ESA (July 2025): Launched MTG-S1 carrying the Sentinel-4 instrument, extending persistent atmospheric monitoring over Europe [1][2]
  • SES (July 2025): Completed its roughly USD 3.1 billion acquisition of Intelsat, creating a larger multi-orbit fleet operator [8]
  • Airbus, Thales, and Leonardo (October 2025): Signed a memorandum to combine their space businesses, a move that could reshape European GEO manufacturing [21]
  • SES and Infinite Orbits (November 2025): Agreed on a commercial life-extension mission for a GEO satellite, supporting the case for servicing [25]

Geo Satellite Market Report Scope

Parameter Details
Market Scope Geostationary satellites by type, mass, and propulsion, sold to commercial, government and civil, and military end users
Study Period 2021–2035
Base Year 2025
Historical Data 2021–2024
Forecast Period 2026–2035
Market Size in 2025 USD 4.32 Billion
Market Size in 2035 USD 15.66 Billion
CAGR (2026–2035) 14.5%
Fastest Growing Segments Medium (18.5% CAGR); Earth Observation Satellites (16.5% CAGR); Military (16.2% CAGR)
Regions Covered North America, Europe, South America, Asia Pacific, Middle East and Africa and ROW
Companies Profiled Airbus Defence and Space, Thales Alenia Space, Boeing, Maxar Space Systems, Lockheed Martin, Northrop Grumman, Mitsubishi Electric, OHB SE, Rocket Lab, SWISSto12, ReOrbit, Astroscale
Valuation Currency USD Billion
Methodology 350+ primary expert interviews; bottom-up market sizing; top-down validation; data triangulation; scenario-based forecasting; real-time project tracking

FAQs

How should investors weigh GEO against LEO exposure in the GEO satellite market?
GEO assets generate long, contracted lease revenue with fewer satellites to maintain. LEO offers growth but requires continuous constellation replenishment. Many investors in the GEO satellite market now favor operators with multi-orbit portfolios [8].
What should buyers check before signing a GEO satellite procurement contract?
Buyers should confirm the payload can be reconfigured in orbit and that the bus carries a standard servicing interface. Late-delivery penalties and insurance terms deserve equal scrutiny [11].
Is leasing a satellite cheaper than owning one in the GEO satellite market?
Leasing lowers upfront capital and transfers technical risk to the manufacturer, which is why it is spreading across the GEO satellite market. Over a full 15-year life, ownership is usually cheaper for operators with strong balance sheets [24].
Who owns an orbital slot once a satellite retires?
The slot belongs to the filing national administration under ITU rules, not to the operator. Operators keep access only while they maintain service and coordination .
Can GEO satellites support direct-to-device connectivity?
Yes, the GEO satellite market already supports narrowband messaging and IoT through large deployable antennas. Voice and broadband to unmodified phones remain technically difficult at GEO distances [15].
What does cybersecurity mean for satellites in the GEO satellite market?
Software-defined payloads expand the attack surface because commands can change coverage and power. Encrypted command links and zero-trust ground segments are becoming standard contract requirements [3].
How long does a typical GEO servicing mission take to arrange?
Planning, licensing, and launch usually take two to four years from contract signature. Docking takes weeks once the servicer arrives, so the GEO satellite market treats servicing as a planned, not emergency, option [11].
Author
Author Author Profile Shubham Munde LinkedIn Team Lead - Research
Shubham brings over 7 years of expertise in Market Intelligence and Strategic Consulting, with a strong focus on the Automotive, Aerospace, and Defense sectors. Backed by a solid foundation in semiconductors, electronics, and software, he has successfully delivered high-impact syndicated and custom research on a global scale. His core strengths include market sizing, forecasting, competitive intelligence, consumer insights, and supply chain mapping. Widely recognized for developing scalable growth strategies, Shubham empowers clients to navigate complex markets and achieve a lasting competitive edge. Trusted by start-ups and Fortune 500 companies alike, he consistently converts challenges into strategic opportunities that drive sustainable growth.
Co-Author Co-Author Profile Sejal Akre LinkedIn Senior Research Analyst
She has over 5 years of rich experience, in market research and consulting providing valuable market insights to client. Hands on expertise in management consulting, and extensive knowledge in domain including ICT, Automotive & Transportation and Aerospace & Defense. She is skilled in Go-to market strategy, industry analysis, market sizing, in depth company profiling, competitive intelligence & benchmarking and value chain amongst others.
Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Aircraft MRO Market
Case Study
Aerospace & Defense
Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.

















