Gas Turbine MRO Market (2026 - 2035)

Gas Turbine MRO Market Research Report By Capacity (Below 30 MW, 31 to 120 MW, Above 120 MW), By Turbine Cycle (Combined Cycle, Open/Simple Cycle), By Service Type (Maintenance, Repair, Overhaul), By End-User Industry (Power Generation, Oil and Gas, Industrial and Other) - Forecast to 2035
ID: MRFR/EnP/33240-HCR 100 Pages Chitranshi Jaiswal Last Updated: September 17, 2026
Gas Turbine MRO Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)5.22%
2025 Market SizeUSD 17.79 Billion
2035 Market SizeUSD 29.50 Billion
Key Players
GE Vernova
Siemens Energy
Mitsubishi Power
Baker Hughes
Ansaldo Energia
Sulzer
Opportunities
  • Hydrogen Co-Firing Conversion Packages
  • Emerging-Market Service Footprint
  • Outcome-Based Digital Contracts

Gas Turbine MRO Market Summary

The Gas Turbine MRO Market reached USD 17.79 billion in 2025 and opens the forecast window at USD 18.66 billion in 2026, climbing to USD 29.50 billion by 2035 at a 5.22% CAGR. Two catalysts anchor that trajectory. The first is a global fleet whose average unit age now exceeds 18 years, pushing thousands of frames past their second major inspection interval [1]. The second is the U.S. Inflation Reduction Act's 45V hydrogen production credit, worth up to USD 3.00/kg, which has made hydrogen-ready retrofit packages commercially defensible rather than aspirational [2].

Calendar-based service logic is being phased out by operators in favor of condition-based regimens that are based on vibration analytics, borescope image recognition, and thermodynamic drift modeling. Dry low-emission architectures are replacing legacy diffusion combustors, and conventional thermal barrier coatings are being replaced by rare-earth-doped ceramic systems. A base that feeds aftermarket demand for a decade, the International Energy Agency monitored approximately USD 135 billion of gas-fired capacity investment in 2024 [3].

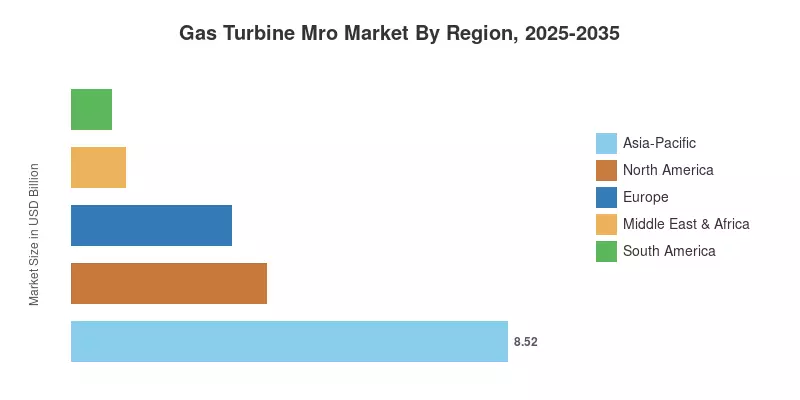
The combined-cycle build-out across China, India, and ASEAN is driving the highest growth rate of 5.48% through 2035, while Asia-Pacific continues to dominate with 47.9% of 2025 revenue. The second-largest region is North America, where the cycling duty from renewable balancing reduces the outage intervals. In the Gas Turbine MRO Market, providers who combine diagnostics with guaranteed availability are currently reaping the benefits of momentum.


Key Report Takeaways

• By Capacity

  • Turbines rated above 120 MW held 53.6% of the Gas Turbine MRO Market share in 2025, reflecting utility-scale frame concentration.
  • The 31–120 MW class is forecast to post a 6.90% CAGR through 2035 as industrial cogeneration expands.
  • Units below 30 MW generated USD 2.42 billion in 2025 revenue across distributed and offshore duty.

• By End user

  • Power generation accounted for 64.3% of 2025 demand within the Gas Turbine MRO Market.
  • Oil and gas contributed USD 4.43 billion, concentrated in LNG liquefaction trains and pipeline compression.
  • Industrial and other end users are tracking a 9.74% CAGR, the fastest of any end-user class.

• By Region

  • Asia-Pacific commanded 47.9% of 2025 revenue
  • North America is valued at USD 3.81 billion, driven by cycling-induced wear.
  • Middle East & Africa is advancing at a 5.95% CAGR on desalination and grid expansion.


Market Size and Forecast (2021–2035)

Estimates blend OEM aftermarket disclosures, utility outage filings, customs data on hot-gas-path components, and interviews with 42 service providers. Historical values are reconciled against installed-base fleet models; forecast values apply a capacity-weighted outage frequency method. The Gas Turbine MRO Market baseline is denominated in constant 2025 U.S. dollars.
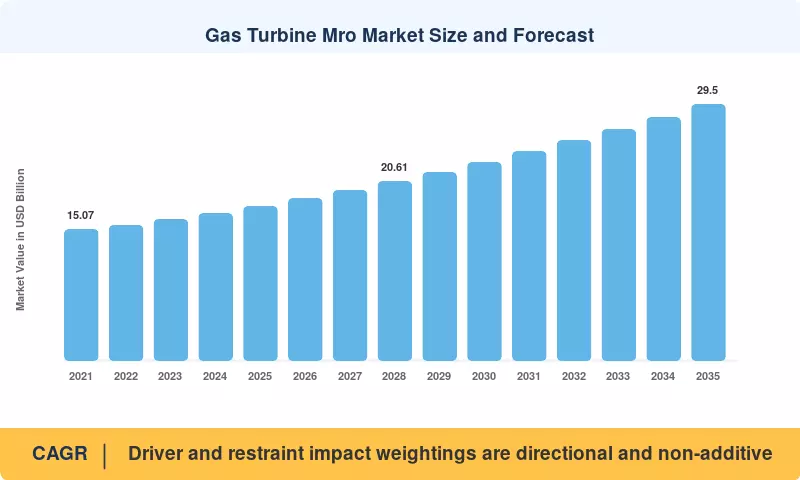
Gas Turbine Mro Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Impact percentages below are directional indicators of relative contribution weight. They are not additive and should not be summed to reconstruct the headline CAGR of the Gas Turbine MRO Market.

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Aging installed base crossing inspection thresholds ~1.35% Global Long-term (≥4 yr)
Cycling duty from renewable balancing ~1.05% North America, Europe Medium-term (2–4 yr)
Asia-Pacific combined-cycle build-out ~0.95% Asia-Pacific Long-term (≥4 yr)
Hydrogen co-firing retrofit mandates ~0.70% Europe, North America Medium-term (2–4 yr)
Digital diagnostics and remote monitoring adoption ~0.60% Global Short-term (≤2 yr)
Long-term service agreement penetration ~0.45% Global Short-term (≤2 yr)
LNG capacity expansion driving mechanical drive demand ~0.35% MEA, North America Medium-term (2–4 yr)


Aging Fleet Economics

Roughly 62% of the operating global fleet was commissioned before 2008, placing a large cohort at the equivalent-operating-hour boundary where full rotor replacement decisions arise [1]. The Electric Power Research Institute estimates that a life-extension pathway costs 35–45% of a comparable greenfield unit, which keeps owners inside the aftermarket rather than the new-build queue [11].


Cycling Duty and Thermal Fatigue

Renewable penetration has reshaped duty profiles. Federal Energy Regulatory Commission filings show U.S. combined-cycle units averaging 4.2 starts per week against 1.6 in 2016, and each start-stop event consumes equivalent operating hours at a multiplier of roughly 20:1 [8]. Thermal fatigue cracking in transition pieces and first-stage nozzles now dictates outage scheduling more than fired hours do.


Hydrogen Readiness and Decarbonization Rules

Europe's Net-Zero Industry Act and the EU Emissions Trading System reform have pushed carbon costs above EUR 70/tonne, sharpening the payback case for combustion-system conversion [12]. The U.S. Department of Energy's Hydrogen Hub program allocated USD 7 billion across seven regional clusters, several of which name turbine conversion as an anchor offtake [13].

Digital Diagnostics Penetration

Remote monitoring centres now cover an estimated 41% of the utility-scale fleet, and operators report 12–18% reductions in unplanned downtime after deployment [9]. Predictive analytics also shifts revenue mix toward higher-margin advisory contracts within the Gas Turbine MRO Market.


Restraints Impact Analysis

Restraint ~% Drag on CAGR Geographic Relevance Impact Timeline
Super-alloy and single-crystal casting supply constraints ~-0.75% Global Medium-term (2–4 yr)
Coal-to-renewables displacement of gas dispatch ~-0.55% Europe Long-term (≥4 yr)
Skilled field-service technician shortage ~-0.45% North America, Europe Short-term (≤2 yr)
OEM parts warranty restrictions on third-party repair ~-0.35% Global Medium-term (2–4 yr)
Capex deferral during interest-rate volatility ~-0.25% South America, MEA Short-term (≤2 yr)


Hot-Gas-Path Material Bottlenecks

Directionally solidified and single-crystal blade castings depend on a handful of qualified foundries, and lead times for first-stage buckets stretched to 58 weeks in 2024 against 32 weeks pre-2020 [5]. Rhenium pricing volatility compounds the problem, with spot values swinging above USD 1,400/kg. Providers holding rotable pools capture a pricing premium that independent shops without inventory cannot match.

Workforce Scarcity

Field service depends on certified outage crews, and the Bureau of Labor Statistics projects power-plant operator and maintenance roles growing more slowly than retirements through 2032, implying a shortfall of roughly 18,000 skilled positions in the U.S. alone [14]. Outage windows lengthen when crews are thin, and lengthened outages depress annual throughput per shop.

Aftermarket Access Friction

Original equipment manufacturers increasingly tie parts warranties and controls-software access to bundled service agreements, narrowing the addressable pool for independents. European competition authorities opened preliminary reviews of aftermarket bundling practices in the power equipment sector during 2024, an outcome that could reshape share distribution [15].


Gas Turbine MRO Market Opportunities

Hydrogen Co-Firing Conversion Packages

Conversion kits enabling 30–50% hydrogen blends represent a service line barely present five years ago. With announced hydrogen-ready projects across Europe and North America, conversion revenue is projected to scale significantly alongside global decarbonization mandates. Industry evaluations value the overarching hydrogen turbine sector at over USD 1.6 billion, expanding rapidly toward 2032.


Emerging-Market Service Footprint

India, Vietnam, and Indonesia are adding combined-cycle capacity faster than domestic repair capability. Localized shops offering gas turbine hot section overhaul capability near the installed base can capture 15–20 percentage points of margin otherwise lost to freight and duties [7].

Outcome-Based Digital Contracts

Availability-guaranteed agreements priced per megawatt-hour convert episodic outage revenue into recurring cash flow. Data collected during those contracts becomes a monetizable asset, licensable back to insurers and grid operators for reliability underwriting [9].

Additive Manufacturing for Legacy Parts

Additive repair of obsolete components sidesteps foundry bottlenecks entirely. Qualification cycles are shortening, and printed fuel nozzles already show 20–30% lead-time reductions versus cast equivalents [5].

Mechanical Drive in LNG Expansion

Global LNG liquefaction capacity under construction exceeds 180 million tonnes per annum, most of it turbine-driven and located in regions with limited local service depth [10].


Gas Turbine MRO Market Future Outlook

Autonomous Outage Planning

Machine-learning models trained on borescope imagery and vibration signatures now recommend outage scope with accuracy approaching experienced inspectors. International Energy Agency tracking indicates that global digital electricity infrastructure investments scale rapidly to handle complex grids, with overall annual power system digitalization and smart software deployments expanding multi-fold to secure network resilience and minimize unexpected downtime across thermal facilities.


Service Platform Economics

Bundling shifts value from parts margin to contracted availability. Providers who own the data layer set renewal terms, and the Gas Turbine MRO Market is consolidating around perhaps six platforms with genuine fleet-wide telemetry reach [9].

Firming the Electrification Supercycle

Data-centre load growth is rewriting dispatch assumptions. U.S. electricity demand is projected to rise 15–20% by 2030 after two flat decades, and gas turbines remain the default firming resource where transmission is constrained [18].

Emissions Reporting and Asset Disclosure

CSRD and ISSB reporting obligations require asset-level emissions intensity, which turns heat-rate recovery from an operational preference into a disclosed metric. Turbine blade coating repair MRO work that restores efficiency now carries reporting value alongside fuel savings [12].


Regional Market Share Analysis

Region Metric Primary Investment Themes
North America USD 3.81 Billion (2025) Cycling duty, hydrogen hubs, LTSA renewals
Europe 17.6% share (2025) Decarbonization retrofits, ETS compliance
Asia-Pacific 47.9% share (2025) Combined-cycle build-out, localization
South America 4.40% share (2025) Hydro backup capacity, grid firming
Middle East & Africa 5.95% CAGR (2026–2035) Desalination, LNG, industrial parks
Total USD 17.79 Billion (2025) —

Regional distribution in the Gas Turbine MRO Market mirrors installed capacity rather than GDP, which is why Asia-Pacific outweighs North America by more than two to one.


North America

Country Metric Key Driver
US 82.5% of region Renewable balancing and cycling wear
Canada USD 0.41 Billion Oil sands cogeneration
Mexico 6.20% CAGR CFE combined-cycle expansion


Regional demand within the North American Gas Turbine MRO Market is shaped less by capacity additions than by duty profile change. PJM and ERCOT dispatch data show combined-cycle fleets absorbing ramp obligations once handled by coal, which accelerates combustion-section wear. The DOE Hydrogen Hub awards create a second demand layer around fuel-system conversion in Appalachia and the Gulf Coast [13].

Europe

Country Metric Key Driver
Germany 21.8% of region Kraftwerkssicherheitsgesetz capacity tenders
UK USD 0.52 Billion Capacity Market obligations
France 9.40% of region Industrial cogeneration renewal
Italy 5.85% CAGR Terna grid-firming contracts
Spain 7.10% of region Solar backup dispatch
Nordic Countries USD 0.16 Billion District heating CHP
Russia 6.80% of region Domestic OEM substitution
Rest of Europe 4.15% CAGR Central European gas conversion


Policy drives European aftermarket economics. Germany's power plant security legislation targets roughly 12.5 GW of new hydrogen-ready capacity through competitive tenders, and every tendered unit carries a multi-decade service tail [12]. Carbon pricing above EUR 70/tonne simultaneously rewards efficiency-recovery outages that restore 1.5–2.5 percentage points of heat rate.

Asia-Pacific

Country Metric Key Driver
China 33.4% of region Provincial combined-cycle programs
India 7.85% CAGR Peaking capacity and gas allocation reform
Japan USD 1.24 Billion Fleet modernization and ammonia co-firing
South Korea 11.2% of region Ninth Basic Plan LNG buildout
ASEAN 6.90% CAGR Vietnam and Indonesia capacity additions
Rest of Asia-Pacific USD 0.38 Billion Distributed industrial duty


Scale explains Asia-Pacific's dominance of the Gas Turbine MRO Market. China alone commissioned more than 14 GW of gas-fired capacity in 2024, and Japan's Green Transformation program earmarks JPY 20 trillion of transition funding, part of which underwrites combustion upgrades on existing frames [7]. Localization of repair capacity remains the region's structural bottleneck and its clearest commercial opening.

South America

Country Metric Key Driver
Brazil 58.5% of region Hydrological risk backup dispatch
Argentina USD 0.17 Billion Vaca Muerta associated gas
Rest of South America 5.40% CAGR Mining sector captive power


Hydrology governs Brazilian dispatch. Drought years push thermal utilization above 55%, compressing maintenance intervals and pulling forward overhaul spend; wet years do the reverse. ANEEL capacity auctions have contracted several gigawatts of thermal reserve, giving service providers a firmer revenue floor than utilization data alone would suggest [16].

Middle East & Africa

Country Metric Key Driver
Saudi Arabia 34.2% of region Vision 2030 industrial cities
UAE USD 0.28 Billion Cogeneration and desalination
South Africa 6.40% CAGR Eskom peaking fleet reliability
Egypt 12.8% of region Siemens megaproject fleet support
Rest of MEA USD 0.19 Billion Nigerian and Algerian gas processing


Egypt's 14.4 GW megaproject fleet, commissioned between 2017 and 2019, entered its first major inspection cycle in 2024, creating a concentrated outage wave [17]. Saudi Aramco's mechanical-drive population adds a second demand pool tied to gas processing rather than power export.


Gas Turbine Mro Market By Region, 2025-2035

Gas Turbine MRO Market Segmentation

Segmentation of the Gas Turbine MRO Market follows capacity class, turbine cycle, service type, and end-user industry.

By Capacity

Segment Metric Primary Demand Driver
Below 30 MW USD 2.42 Billion (2025) Distributed and offshore duty
31 to 120 MW 6.90% CAGR (2026–2035) Industrial cogeneration growth
Above 120 MW 53.6% share (2025) Utility-scale frame concentration


Heavy-duty frames above 120 MW dominate because parts value scales non-linearly with firing temperature. A single first-stage bucket set on an advanced-class machine can exceed USD 4 million, so one major inspection generates more revenue than a decade of small-frame servicing. Mid-range units grow faster, however, as industrial users adopt on-site generation to hedge grid volatility, and this class within the Gas Turbine MRO Market benefits from shorter, more frequent service events.

By Turbine Cycle

Segment Metric Primary Demand Driver
Combined Cycle 79.2% share (2025) Baseload and mid-merit utilization
Open/Simple Cycle 6.05% CAGR (2026–2035) Peaking and grid-firming duty


Combined-cycle plants carry more equipment per site and run more hours, which is why they anchor revenue. Simple-cycle growth outpaces them because peaking duty is expanding fastest, and start-heavy profiles consume component life disproportionately.

By Service Type

Segment Metric Primary Demand Driver
Maintenance 50.2% share (2025) Scheduled inspection cadence
Repair USD 4.89 Billion (2025) Component life extension


Overhaul 6.37% CAGR (2026–2035) Fleet aging past major intervals


Maintenance holds the largest share of the Gas Turbine MRO Market because every unit requires it regardless of age, while overhaul grows fastest as the pre-2008 cohort reaches replacement thresholds. Power generation's dominance is structural, though industrial demand compounds quickest as manufacturers install captive capacity to escape unreliable grids.

End User

Segment Metric Primary Demand Driver
Power Generation 64.3% share (2025) Utility fleet scale
Oil and Gas USD 4.43 Billion (2025) LNG and pipeline compression
Industrial and Other 9.74% CAGR (2026–2035) Captive power adoption


The Gas Turbine MRO Market is dominated by the Power Generation segment, which commands a 64.3% share in 2025 driven by large-scale utility fleets. Meanwhile, the Industrial and Other category emerges as the fastest-growing segment, projected to expand at a 9.74% CAGR (2026–2035) fueled by captive power adoption. The Oil and Gas segment holds USD 4.43 billion (2025), driven by LNG and pipeline compression. This landscape is shaped by decarbonization regulations such as the European Union's Net-Zero Industry Act and the EU Emissions Trading System, which mandate stricter efficiency and emissions standards across these operational end-user sectors.

Competitive Benchmarking

Concentration sits in the medium band, with an estimated HHI near 1,180 and a top-five share around 52%. Original equipment manufacturers retain advantage through parts control and controls-software access, yet independent service providers hold defensible positions in repair engineering and legacy-frame support. Fragmentation is greatest in the sub-30 MW segment.

Company Est. Revenue Share Range Key Offerings for Gas Turbine MRO Market Strategic Positioning
GE Vernova ~17–21% Full-scope LTSA, HA-class parts, Digital Twin diagnostics Largest installed base; data-led renewals
Siemens Energy ~14–18% Omnivise monitoring, hydrogen conversion kits, field service Decarbonization retrofit leader
Mitsubishi Power ~9–12% TOMONI analytics, JAC-class overhauls, ammonia co-firing Strong Asia-Pacific depth
Baker Hughes ~6–9% Aeroderivative MRO, mechanical drive support LNG and oil & gas specialist
Ansaldo Energia ~4–6% Multi-OEM service, combustion upgrades European independent-OEM hybrid
Sulzer ~3–5% Rotor repair, coatings, machining Non-OEM component specialist
MTU Aero Engines ~2–4% Aeroderivative overhaul, LM-series support Aviation-derived process rigor
EthosEnergy ~2–4% Independent field service, rotable exchange Cost-competitive independent
Wood Group ~2–3% Asset management, outage execution Services-integrator model
Chromalloy ~2–3% FAA/PMA parts, coatings, blade repair Aftermarket parts alternative
PSM (Hanwha) ~1–3% DLE combustion retrofits, flex operation Emissions-upgrade niche


Recent News & Developments

  • GE Vernova (March 2025): Commissioned an expanded advanced-class repair facility in Greenville, adding rotor throughput capacity for the Gas Turbine MRO Market's fastest-aging cohort [19].


  • Mitsubishi Power (July 2024): Extended its TOMONI remote monitoring network across additional Southeast Asian combined-cycle sites [7].
  • U.S. Department of Energy (October 2023): Finalized USD 7 billion in Hydrogen Hub awards naming turbine offtake among anchor uses [13].
  • Baker Hughes (May 2025): Announced a long-term service agreement supporting LNG mechanical-drive trains in Qatar [10].
  • Chromalloy (February 2024): Received additional PMA approvals for hot-section components, widening independent parts supply [15].
  • European Commission (April 2024): Opened consultation on aftermarket access practices in power equipment servicing [15].


Gas Turbine MRO Market Report Scope

Parameter Detail
Market Scope Maintenance, repair, and overhaul services for industrial and utility gas turbines
Study Period 2021–2035 (Base Year 2025; Forecast 2026–2035)
CAGR 5.22% (2026–2035)
Market Size Checkpoints USD 17.79 Billion (2025); USD 18.66 Billion (2026); USD 29.50 Billion (2035)
Fastest Growing Segments Industrial and Other end use; 31–120 MW capacity; Overhaul services
Companies Profiled 11 leading providers across OEM and independent channels
Valuation Currency USD Billion (constant 2025 dollars)
CAGR Driver Disclaimer Driver and restraint impact weightings are directional and non-additive

FAQs

How should buyers evaluate a long-term service agreement versus transactional servicing in the Gas Turbine MRO Market?
Compare total cost per equivalent operating hour, not annual fee. Agreements make sense above roughly 5,000 annual fired hours; below that, transactional buying usually wins on cost [6].
What contractual protections matter most when parts lead times are volatile?
Insist on rotable pool access commitments and liquidated damages tied to outage duration. Guaranteed parts availability clauses have become the primary differentiator in renewal negotiations [5].
Does insurance treatment differ between OEM and independent servicing in the Gas Turbine MRO Market?
Some underwriters apply higher deductibles when non-OEM parts are installed on advanced-class frames. Confirm policy language before switching providers, since premium differentials can offset parts savings [15].
How does ammonia co-firing compare with hydrogen blending as a retrofit path?
Ammonia suits regions with existing import infrastructure, particularly Japan and South Korea. Hydrogen offers cleaner combustion chemistry but demands larger fuel-system redesign and on-site storage investment [7].
What integration challenges arise when layering third-party analytics onto OEM controls in the Gas Turbine MRO Market?
Controls-system data rights are frequently restricted by license terms. Negotiate export permissions at procurement rather than retrofit, when leverage is highest [9].
Which certifications should procurement teams verify in a repair vendor?
Check ISO 9001, AS9100 where aeroderivative work applies, and OEM-equivalent coating process approvals. Coating qualification is the most common gap among lower-cost shops [24].
How do carbon disclosure rules affect maintenance budgeting?
Efficiency-recovery outages now carry reportable emissions benefits under CSRD and ISSB frameworks. Finance teams increasingly fund heat-rate restoration from sustainability budgets rather than maintenance lines [12].    
Author
Author Author Profile Chitranshi Jaiswal LinkedIn Team Lead - Research
Chitranshi is a Team Leader in the Chemicals & Materials (CnM) and Energy & Power (EnP) domains, with 6+ years of experience in market research. She leads and mentors teams to deliver cross-domain projects that equip clients with actionable insights and growth strategies. She is skilled in market estimation, forecasting, competitive benchmarking, and both primary & secondary research, enabling her to turn complex data into decision-ready insights. An engineer and MBA professional, she combines technical expertise with strategic acumen to solve dynamic market challenges. Chitranshi has successfully managed projects that support market entry, investment planning, and competitive positioning, while building strong client relationships. Certified in Advanced Excel & Power BI she leverages data-driven approaches to ensure accuracy, clarity, and impactful outcomes.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of regulatory databases, industry publications, technical standards documentation, and authoritative energy and aviation organizations. Key sources included the US Federal Aviation Administration (FAA), European Union Aviation Safety Agency (EASA), US Energy Information Administration (EIA), International Energy Agency (IEA), International Air Transport Association (IATA), International Civil Aviation Organization (ICAO), International Gas Turbine Institute (IGTI), US Department of Energy (DOE), National Institute of Standards and Technology (NIST), Environmental Protection Agency (EPA), European Environment Agency (EEA), International Organization for Standardization (ISO), American Society of Mechanical Engineers (ASME), Turbomachinery Laboratory at Texas A&M, Gas Turbine Association (GTA), Power Engineering International databases, and national energy ministry reports from key markets.

Fleet statistics, regulatory compliance data, maintenance interval standards, capacity utilization trends, and market landscape analysis for maintenance, repair, overhaul, and modification services across power generation, aerospace, marine, and oil and gas applications were gathered from these sources.


Primary Research

In order to gather both qualitative and quantitative insights, supply-side and demand-side stakeholders were interviewed during the primary research process. CEOs, VPs of Engineering, MRO operations heads, and service directors from independent MRO providers, component manufacturers, and gas turbine OEMs were examples of supply-side sources. Fleet managers, chief engineers, procurement directors from power utilities, airline engineering departments, maritime operators, and managers of oil and gas facilities were examples of demand-side sources. In addition to gathering information on maintenance outsourcing trends, digital adoption tactics, and long-term service agreement dynamics, primary research verified service agreement timelines and validated market segmentation.

Primary Respondent Breakdown:

By Designation: C-level Primaries (30%), Director Level (32%), Others (38%)

By Region: North America (38%), Europe (25%), Asia-Pacific (28%), Rest of World (9%)


Market Size Estimation

Global market valuation was derived through revenue mapping and service volume analysis. The methodology included:

Identification of 50+ key MRO service providers across North America, Europe, Asia-Pacific, Latin America, and Middle East & Africa

Service mapping across maintenance, repair, overhaul, and modification categories

Component-level analysis across compressor, combustor, turbine, and fuel system segments

Analysis of reported and modeled annual revenues specific to gas turbine MRO portfolios

Coverage of service providers representing 75-80% of global market share in 2024

Extrapolation using bottom-up (fleet size × maintenance cost by region) and top-down (service provider revenue validation) approaches to derive segment-specific valuations

Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.


















