Gas Turbine Services Market (2026 - 2035)

Gas Turbine Services Market Research Report By Service Type (Maintenance & Repair, Overhaul, Spare Parts Supply, Upgrades & Retrofits, Remote Monitoring & Diagnostics), By Turbine Type (Heavy-Duty Gas Turbines, Aeroderivative Gas Turbines, Industrial / Light-Duty Gas Turbines), By Capacity (≤50 MW, 51–150 MW, 151–300 MW, >300 MW), By Provider Type (Original Equipment Manufacturers, Independent Service Providers, In-House / Utility Self-Perform), By End User (Power Generation (Utilities & IPPs), Oil & Gas, Industrial & Process, Marine & Others) - Forecast to 2035
ID: MRFR/EnP/5804-CR 128 Pages Priya Nagrale Last Updated: September 15, 2026
Gas Turbine Services Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)5.1%
2025 Market SizeUSD 27.4 Billion
2035 Market SizeUSD 45.1 Billion
Key Players
GE Vernova
Siemens Energy
Mitsubishi Power
Baker Hughes
Solar Turbines
Ansaldo Energia
Opportunities
  • Hydrogen Co-Firing Conversions
  • Emerging Market Fleet Expansion
  • Outcome-Based Contracting and Fleet Data Monetization

Gas Turbine Services Market Summary

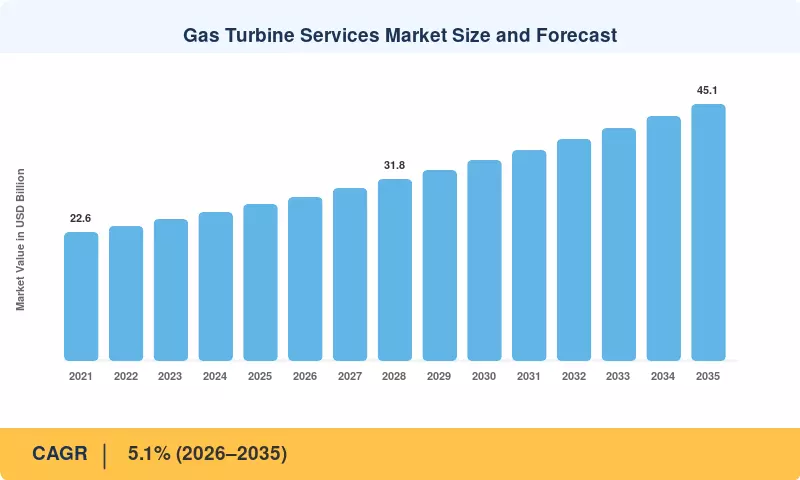
The Gas Turbine Services Market was valued at USD 27.4 billion in 2025 and is projected to open the forecast period at USD 28.8 billion in 2026, reaching USD 45.1 billion by 2035 at a CAGR of 5.1% between 2026 and 2035. Two catalysts anchor that trajectory. First, roughly 1,900 GW of gas-fired capacity is installed worldwide, and a large share of it has passed the 100,000-fired-hour threshold that triggers major inspection scopes [1]. Second, the U.S. Inflation Reduction Act and the EU's Net-Zero Industry Act have pushed operators toward efficiency retrofits rather than early retirement, converting what were once replacement decisions into service decisions [2][3].

The delivery of that expenditure is being transformed by technology. Condition-based programs, which are driven by sensor telemetry, borescope imaging analytics, and physics-informed fleet models, are replacing calendar-based overhaul cycles that are constructed around fixed inspection intervals. GE Vernova, Siemens Energy, and Mitsubishi Power each report that over half of their monitored fleets are currently operating on remote-diagnostic contracts. The IEA anticipates that global digital investment across power operations will surpass USD 21 billion in 2024 [1][4]. In numerous cases, the lifespan of parts has been extended by 15–25% as a result of additive-manufactured hot section components and technological advancements in coating [5].

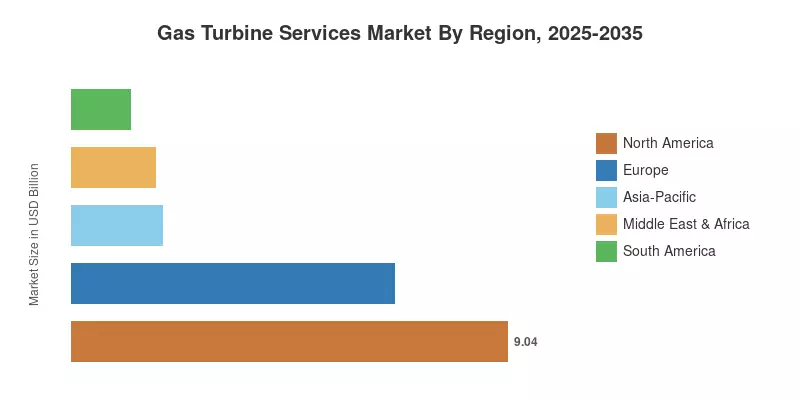
North America is responsible for 33.0% of 2025 revenue, which is bolstered by a substantial heavy-duty fleet and rapid load growth from data centers. Driven by the combined-cycle buildout in China and India, the Asia-Pacific region is the fastest-expanding region, with a compound annual growth rate (CAGR) of 6.9% through 2035. Europe follows with USD 6.7 billion in 2025 expenditures, with hydrogen-readiness enhancements and emissions compliance being the primary focus. Providers who are capable of pricing outcomes rather than components will be rewarded in the forthcoming decade.


Key Report Takeaways

• By Service Type

  • Maintenance and repair accounts for 38.0% of Gas Turbine Services Market revenue in 2025, the single largest scope category
  • Remote monitoring and diagnostics grows fastest at a 9.1% CAGR through 2035 as operators shift to condition-based intervals.

• By Turbine Type

  • Heavy-duty frames represent 61.0% of global service revenue, reflecting their concentration in utility-scale combined-cycle plants.
  • Industrial and light-duty units generate USD 4.5 billion in 2025 service spend across process and distributed applications.

• By Capacity

  • Units above 300 MW hold 39.5% of service revenue, concentrated in F-, H-, and J-class installations.
  • The 51–150 MW band expands at a 6.6% CAGR, the quickest of any capacity class.

• By Provider Type

  • Original equipment manufacturers control 57.5% of billed service revenue through long-duration contractual agreements.
  • Independent service providers grow at a 6.5% CAGR as operators unbundle parts and labor scopes.

• By End User

  • Power generation utilities and independent power producers account for 55.0% of demand within the Gas Turbine Services Market
  • Oil and gas mechanical drive applications advance at a 5.8% CAGR on LNG train expansions

• By Region

  • North America commands 33.0% of 2025 global revenue
  • Asia-Pacific posts a 6.9% CAGR, the fastest regional growth rate through 2035

Market Size and Forecast (2021–2035)

Historical values were reconstructed from OEM service backlog disclosures, utility maintenance budget filings, EIA and IEA generation databases, and interviews with 40 plant operators and independent repair shops across five regions. Forecast values apply fired-hour accumulation modelling to the installed base, adjusted for retirement schedules, capacity factor trends, and announced retrofit programs. The Gas Turbine Services Market is measured on a billed-revenue basis covering parts, field labor, overhaul, upgrades, and digital service contracts.
Gas Turbine Services Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Aging installed base and fired-hour accumulation 1.1 Global Medium-term (2–4 yr)
Gas-fired capacity additions for grid firming 0.9 North America, MEA, Asia-Pacific Long-term (≥4 yr)
Data center load growth lifting capacity factors 0.8 North America, Europe Short-term (≤2 yr)
Efficiency uprates and emissions retrofits. 0.7 Europe, North America Medium-term (2–4 yr)
Predictive diagnostics and condition-based servicing 0.6 Global Short-term (≤2 yr)
LNG and upstream mechanical drive expansion 0.5 MEA, Asia-Pacific, North America Long-term (≥4 yr)
Competitive unbundling by independent providers 0.4 Europe, North America Medium-term (2–4 yr)


Aging Installed Base and Fired-Hour Accumulation

More than 55% of the global heavy-duty fleet was commissioned before 2010, and the IEA places worldwide gas-fired capacity near 1,900 GW [1]. Every 24,000 to 32,000 fired hours triggers a hot section scope; every 48,000 to 64,000 triggers a major inspection. Because inspection intervals are contractually fixed in most service agreements, this demand is largely non-discretionary. Operators running 4,000-plus hours annually now face major inspections costing USD 8–14 million per unit.

Gas-Fired Capacity Additions for Grid Firming

The EIA recorded 4.4 GW of new U.S. gas capacity in 2024 with a further 9 GW announced for 2026–2028, largely combustion turbines sized for fast-start duty [7]. Saudi Arabia's Ministry of Energy has tendered over 8 GW of combined-cycle capacity under Vision 2030 program allocations [13]. New units carry factory-backed service agreements from commissioning, adding contracted revenue to the base before any inspection occurs.

Data Center Load Growth Lifting Capacity Factors

U.S. data center electricity consumption reached roughly 176 TWh in 2023 and is tracking toward 325–580 TWh by 2028 under Lawrence Berkeley National Laboratory scenarios [8]. Higher baseload demand pushes combined-cycle capacity factors above 60% in PJM and ERCOT, compressing inspection intervals. A unit running 6,500 hours per year reaches its major inspection roughly 40% sooner than one at 4,000 hours, pulling forward service revenue.

Efficiency Uprates and Emissions Retrofits

The EPA's 2024 greenhouse gas standards for existing combustion turbines require capacity-factor-dependent emissions limits from 2032, prompting early evaluation of combustor upgrades and heat rate improvements [9]. In Europe, the Industrial Emissions Directive tightened NOx thresholds to 50 mg/Nm³ for units above 50 MW. Advanced combustion systems and turbine section upgrades typically deliver 1.5–3.0 points of efficiency gain, with paybacks under four years at prevailing fuel prices.

Predictive Diagnostics and Condition-Based Servicing

EPRI field studies indicate condition-based maintenance programs reduce unplanned outage frequency by 20–35% versus calendar-based schedules [14]. Rather than shrinking spend, this shifts it toward higher-margin monitoring subscriptions and targeted component replacement. Siemens Energy reported more than 85 GW under remote diagnostic coverage in its 2024 annual disclosures [15]. Monitoring contracts also generate the fleet data that underpins outcome-linked commercial models discussed in.

LNG and Upstream Mechanical Drive Expansion

Global LNG liquefaction capacity is set to expand by roughly 250 mtpa through 2030, with Qatar's North Field and U.S. Gulf Coast trains leading [11]. Aeroderivative and industrial frames drive refrigeration compressors on these projects, and their duty cycles are continuous. Service intensity per installed megawatt in liquefaction is 30–45% higher than in power generation, making this a disproportionate contributor to revenue relative to installed capacity.

Competitive Unbundling by Independent Providers

Independent repair specialists and licensed parts manufacturers now supply validated hot section components for several mature frames, with catalogue pricing typically 20–35% below OEM list [12]. Rather than shrinking the addressable pool, this has expanded scopes previously deferred on economic grounds. Utilities in Germany, the U.K., and Texas have moved multi-unit fleets to hybrid arrangements combining independent parts sourcing with OEM engineering support.

Restraints Impact Analysis

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
Renewables and storage displacing thermal running hours -0.7 Europe, North America Long-term (≥4 yr)
Long-lead component supply constraints -0.5 Global Short-term (≤2 yr)
Skilled field service labor shortage -0.4 North America, Europe Medium-term (2–4 yr)
Carbon pricing and policy uncertainty -0.4 Europe Medium-term (2–4 yr)
Contractual lock-in limiting addressable spend -0.3 Global Long-term (≥4 yr)


Renewables and Storage Displacing Thermal Running Hours

IRENA reports 585 GW of renewable capacity added globally in 2024, the largest annual increase on record [10]. In California and Germany, combined-cycle capacity factors have fallen below 30% in shoulder seasons. Fewer fired hours stretch inspection intervals, though frequent start-stop cycling partially offsets the effect by accelerating thermal fatigue on combustion hardware.

Long-Lead Component Supply Constraints

Single-crystal blade and vane castings carry lead times of 40–60 weeks, and directionally solidified airfoil capacity remains concentrated among fewer than a dozen qualified foundries [5]. Outage schedules slip when parts arrive late, deferring revenue recognition across quarters. Several operators now hold 12–18 months of critical spares, tying up working capital that would otherwise fund discretionary upgrade scopes.

Skilled Field Service Labor Shortage

The U.S. Bureau of Labor Statistics projects power plant operator employment to decline 4% through 2033 even as service demand rises, and the average field service engineer in the sector is over 47 years old [16]. Certified controls and rotor technicians are scarcer still. Peak outage seasons in spring and autumn now see labor rates rise 15–25% above baseline.

Carbon Pricing and Policy Uncertainty

EU Emissions Trading System allowances traded between EUR 60 and EUR 90 through 2024–2025, and the extension of the Carbon Border Adjustment Mechanism has complicated long-horizon asset planning [3]. Operators uncertain whether a unit will run past 2035 defer life-extension investment. This hesitancy shows up most clearly in Germany and the Netherlands, where discretionary upgrade approvals slowed measurably.

Contractual Lock-In Limiting Addressable Spend

Multi-year service agreements covering 10 to 25 years fix pricing and scope for a substantial share of the installed fleet, insulating roughly 45% of global service revenue from competitive re-bidding in any given year [12]. Buyers gain budget certainty, but the arrangement suppresses price discovery and slows adoption of newer repair technologies until contract renewal windows open.

Gas Turbine Services Market Opportunities

Hydrogen Co-Firing Conversions

Most F-class and later frames can accept 30–50% hydrogen by volume with combustor modification, and OEMs have demonstrated pathways toward 100% capability by the early 2030s. The EU Hydrogen Bank has allocated over EUR 3 billion across auction rounds, while the U.S. DOE committed USD 7 billion to regional hydrogen hubs [17]. Conversion scopes carry engineering content and margins well above routine overhaul work, and they extend asset lives that would otherwise face retirement pressure.

Emerging Market Fleet Expansion

Southeast Asia, Sub-Saharan Africa, and South Asia are adding gas capacity faster than they are adding local service capability. Vietnam's PDP8 targets 37 GW of gas-fired capacity by 2030, and Nigeria's power roadmap prioritizes gas-to-power conversion of stranded flares [18]. Providers that establish regional repair depots and train local technicians capture both first-fill parts revenue and decades of recurring work, at gross margins typically 400–600 basis points above mature-market averages.

Outcome-Based Contracting and Fleet Data Monetization

Availability-guaranteed and output-guaranteed contracts shift risk to the provider in exchange for premium pricing, and they are only underwritable with dense fleet telemetry. Providers monitoring hundreds of units can price reliability risk more accurately than any single operator, creating a structural advantage. Secondary revenue is emerging from benchmarking subscriptions, insurance-linked warranty products, and fuel-flexibility advisory services sold to asset owners and lenders.

Additive Manufacturing and Advanced Repair Technology

Laser powder bed fusion now produces combustor liners, fuel nozzles, and seal segments at 25–40% lower cost than conventional casting for low-volume parts, with lead times measured in weeks rather than quarters [5]. Repair shops adopting these methods can address obsolete frames that OEMs no longer support commercially. The obsolescence segment covers thousands of units worldwide and remains substantially underserved.

Fast-Start and Flexibility Retrofits for Peaking Fleets

Grid operators increasingly value ramp rate over baseload efficiency. Retrofit packages delivering 10-minute starts, lower turndown limits, and cycling-tolerant hot section hardware command premium pricing in ERCOT, PJM, and the U.K. capacity market. Fast-start conversions typically cost USD 4–9 million per unit but unlock ancillary service revenue streams that pay back within three years at current scarcity pricing.

Gas Turbine Services Market Future Outlook

Autonomous Diagnostics and Machine-Led Outage Planning

By 2030, most major-frame outages will be scoped by algorithm rather than by calendar. Fleet-wide anomaly detection trained on hundreds of thousands of operating hours already identifies combustion instability and blade-tip clearance drift weeks before conventional thresholds trigger. The IEA estimates digitalization could reduce unplanned power sector outages by up to 30% [4]. The commercial consequence is a shift from labor-hour billing toward subscription and performance fees.

Platform Economics and Service Aggregation

Scale in monitoring converts directly into pricing power. Providers covering large fleets can pool reliability risk across geographies and underwrite availability guarantees that a single-asset owner cannot self-insure. Expect consolidation among mid-tier repair shops as data scale becomes the differentiator rather than machining capability. Insurance underwriters are already pricing turbine coverage using provider telemetry, which creates a second revenue channel from the same data asset.

Grid Flexibility as the Primary Value Driver

Thermal assets increasingly earn from availability and ramp rate rather than energy volume. IRENA projects renewables will supply over 60% of global generation by 2035, which raises the value of dispatchable backup even as its running hours decline [10]. Retrofit demand will therefore concentrate on cycling durability, low-load turndown, and start reliability. Service contracts will re-price around starts and trips instead of fired hours.

Fuel Transition and Sustainability Disclosure

Hydrogen and ammonia blending will move from demonstration to selective commercial deployment during the early 2030s, concentrated in Europe, Japan, and the U.S. Gulf. Meanwhile, CSRD reporting in Europe and equivalent frameworks elsewhere require asset-level emissions data that service providers are best positioned to generate. Compliance reporting is becoming a billable adjacency, bundled into monitoring agreements at incremental cost but meaningful margin.

Regional Market Share Analysis

Region Metric (2025) Primary Investment Themes
North America 33.0% share Data center load growth, fast-start retrofits, emissions compliance
Europe USD 6.7 Billion Hydrogen readiness, NOx compliance, life extension
Asia-Pacific 6.9% CAGR New-build combined cycle, local depot capability
Middle East & Africa 6.4% CAGR LNG mechanical drive, desalination cogeneration
South America 4.5% share Hydro backup firming, distributed industrial power
Total USD 27.4 Billion

Regional demand within the Gas Turbine Services Market tracks three variables: installed fleet age, capacity factor, and regulatory intensity. North America leads on fleet scale, Asia-Pacific on growth, and the Middle East on service intensity per megawatt.


North America

Country Metric Key Driver
United States 82.0% of region Data center demand and record dispatch hours
Canada USD 1.1 Billion Oil sands cogeneration and Alberta grid firming
Mexico 5.2% CAGR CFE combined-cycle expansion program


The North American Gas Turbine Services Market benefits from the world's largest and most heavily dispatched combined-cycle fleet. PJM's 2025/2026 capacity auction cleared at USD 269.92 per MW-day, a record that materially improved thermal asset economics and unlocked deferred upgrade budgets [7]. EPA's 2024 rule for existing units has pushed utilities to evaluate combustor upgrades early rather than face compressed compliance windows. Canada's contribution concentrates in Alberta, where cogeneration serves oil sands steam demand under continuous duty.

Europe

Country Metric Key Driver
Germany 24.0% of region Coal phase-out replacement capacity
United Kingdom USD 1.4 Billion Capacity market contracts and cycling duty
Italy 15.5% of region Terna grid stability services
France 4.6% CAGR Nuclear outage backup requirements
Rest of Europe 20.0% of region Iberian and Nordic peaking fleets


Europe's service demand is shaped more by regulation than by volume growth. Germany's Power Plant Safety Act framework earmarks support for up to 12.5 GW of hydrogen-ready gas capacity, requiring conversion-capable specifications from procurement onward [19]. The U.K. capacity market has awarded 15-year agreements to refurbished plants, effectively financing life-extension scopes. Italian operators run high cycling duty in support of a renewables-heavy grid, which accelerates combustion hardware wear well beyond fired-hour projections.

Asia-Pacific

Country Metric Key Driver
China 28.5% of region Combined-cycle buildout in coastal provinces
India 7.6% CAGR Gas-based capacity revival and LNG terminal growth
Japan USD 1.5 Billion Ammonia and hydrogen co-firing trials
South Korea 12.0% of region Ninth Basic Plan LNG capacity targets
Australia 4.9% CAGR Gas peaking to firm renewable penetration
Rest of Asia-Pacific 14.0% of region Southeast Asian LNG-to-power projects


Asia-Pacific delivers the fastest expansion in the Gas Turbine Services Market because its installed base is simultaneously growing and aging. China's 14th and 15th Five-Year Plans target gas-fired capacity above 150 GW to support grid flexibility. At the same time, India's Central Electricity Authority has pushed to restore utilization at stranded gas plants as LNG import costs moderated [20]. Japan's Green Innovation Fund is underwriting ammonia co-firing demonstrations that require significant combustion system engineering. Regional depot capacity remains thin, creating openings for independent providers.

Middle East & Africa

Country Metric Key Driver
Saudi Arabia 31.0% of region Vision 2030 combined-cycle and desalination cogeneration
United Arab Emirates USD 0.6 Billion Liquefaction and industrial mechanical drive
Egypt 6.8% CAGR Large installed heavy-duty fleet reaching major inspections
South Africa 9.5% of region Eskom peaking fleet reliability programs
Rest of MEA 22.0% of region Qatari LNG trains and West African gas-to-power


Service intensity in this region exceeds the global average because ambient conditions are punishing. Sustained temperatures above 45°C and airborne particulates accelerate compressor fouling and hot section degradation, shortening effective inspection intervals by 15–20% versus temperate benchmarks. Qatar's North Field expansion alone adds substantial continuous-duty mechanical drive capacity through 2030 [11]. Egypt's fleet, much of it commissioned in a concentrated 2015–2018 wave, is now entering synchronized major inspection windows.

South America

Country Metric Key Driver
Brazil 58.0% of region Thermal dispatch during hydrological shortfalls
Argentina USD 0.24 Billion Vaca Muerta associated gas power projects
Rest of South America 22.0% of region Industrial cogeneration and mining loads


Brazilian demand is hydrology-linked and therefore volatile. When reservoir levels fall below operating targets, the national system operator dispatches thermal capacity aggressively, and fired hours can double within a single season. This unpredictability favors flexible service arrangements over fixed-interval agreements. Argentina's growth stems from Vaca Muerta associated gas, which has made distributed gas-fired generation economic at wellhead pricing well below imported alternatives [21].

Gas Turbine Services Market By Region, 2025-2035

Gas Turbine Services Market Segmentation

By Service Type

Service type segmentation within the Gas Turbine Services Market reflects the distinction between mandatory interval-driven work and discretionary performance investment.

Segment Metric (2025) Primary Demand Driver
Maintenance & Repair 38.0% share Contractual inspection intervals
Overhaul USD 6.2 Billion Major inspection cycles on aging frames
Spare Parts Supply 21.5% share Hot section component replacement
Upgrades & Retrofits 6.7% CAGR Emissions compliance and efficiency gains
Remote Monitoring & Diagnostics 9.1% CAGR Condition-based maintenance adoption


Maintenance and repair leads at 38.0% because inspection intervals are contractually fixed and largely immune to commodity cycles. Remote monitoring and diagnostics grow fastest at 9.1% from a small base, as operators discover that telemetry subscriptions cost a fraction of a single unplanned trip. Overhaul revenue remains lumpy, clustering around fleet cohort windows rather than distributing evenly, which is why 2030 shows an anomalous step in the forecast series.

By Turbine Type

Turbine architecture determines both service intensity and who is qualified to perform the work across the Gas Turbine Services Market.

Segment Metric (2025) Primary Demand Driver
Heavy-Duty Gas Turbines 61.0% share Utility-scale combined-cycle installations
Aeroderivative Gas Turbines 6.2% CAGR Fast-start peaking and offshore mechanical drive
Industrial / Light-Duty Gas Turbines USD 4.5 Billion Process cogeneration and distributed power


Heavy-duty frames dominate at 61.0% because they carry the largest hot section parts values and the most demanding inspection scopes. Aeroderivatives expand fastest at 6.2%, benefiting from grid flexibility requirements and offshore platform duty where weight and start speed matter more than absolute efficiency. Aeroderivative servicing follows an exchange-engine model borrowed from aviation, which shortens site outages to days rather than weeks and appeals to operators with tight dispatch obligations.

By Capacity

Capacity class segmentation in the Gas Turbine Services Market maps closely to plant configuration and contracting sophistication.

Segment Metric (2025) Primary Demand Driver
≤50 MW USD 3.8 Billion Industrial cogeneration and remote power
51–150 MW 6.6% CAGR Peaking and mid-merit flexibility duty
151–300 MW 24.6% share Legacy E- and F-class combined cycle
>300 MW 39.5% share H- and J-class large frame installations


Units above 300 MW hold 39.5% of revenue, reflecting both parts value and the concentration of newest technology in this band. The 51–150 MW class grows fastest at 6.6% as grids add mid-sized flexible capacity to firm renewable output. Smaller units below 50 MW generate steady but fragmented demand, typically served by regional shops rather than by manufacturer field service organizations, which keeps pricing competitive.

By Provider Type

Provider segmentation is the most commercially contested dimension of the Gas Turbine Services Market.

Segment Metric (2025) Primary Demand Driver
Original Equipment Manufacturers 57.5% share Long-duration contractual service agreements
Independent Service Providers 6.5% CAGR Cost pressure and parts unbundling
In-House / Utility Self-Perform USD 3.6 Billion Large fleet operators with internal capability


Manufacturers retain 57.5% of billed revenue, anchored by agreements signed at equipment purchase that bundle parts, labor, and performance guarantees. Independent providers grow fastest at 6.5% as validated alternative parts reach more frames and as operators gain confidence in third-party engineering. Self-perform capability persists among the largest utilities, though the skilled labor shortage described in is gradually pushing even these operators toward external contracting.

By End User

End-user segmentation within the Gas Turbine Services Market separates duty cycles that differ by an order of magnitude in service intensity.

Segment Metric (2025) Primary Demand Driver
Power Generation (Utilities & IPPs) 55.0% share Grid dispatch and capacity obligations
Oil & Gas 5.8% CAGR LNG liquefaction and pipeline compression
Industrial & Process USD 4.0 Billion Cogeneration in chemicals, refining, and paper
Marine & Others 4.5% share Naval propulsion and specialty applications


Power generation dominates at 55.0%, though its running hours are increasingly volatile as renewable penetration rises. Oil and gas grows fastest at 5.8%, driven by continuous-duty mechanical drive on liquefaction trains where downtime costs exceed USD 1 million per day. Industrial cogeneration provides the steadiest baseline of the four, since process steam demand does not fluctuate with electricity prices or weather.

Competitive Benchmarking

Concentration is high at the top and fragmented beneath it. The estimated Herfindahl-Hirschman Index sits near 1,450, placing the sector in moderately concentrated territory. The top five providers control an estimated 62–68% of billed revenue, but several hundred regional repair shops, coating specialists, and rotor service firms compete for the remainder. Barriers to entry are technical rather than capital-intensive: metallurgical qualification, engineering liability coverage, and proven repair validation matter more than machining capacity.

Company Est. Revenue Share Range Key Offerings for Gas Turbine Services Market Strategic Positioning
GE Vernova ~19–23% Full-scope agreements, parts, uprates, hydrogen conversion Largest installed base; digital fleet platform
Siemens Energy ~16–20% Overhaul, remote diagnostics, flexibility retrofits Strong European and cycling-duty franchise
Mitsubishi Power ~9–12% J-series support, ammonia co-firing, long-term agreements Leading in Asia-Pacific large frame
Baker Hughes ~6–9% Aeroderivative and mechanical drive support Oil, gas, and LNG specialization
Solar Turbines (Caterpillar) ~5–7% Industrial frame overhaul, exchange packages Distributed and midstream focus
Ansaldo Energia ~3–5% Multi-OEM frame servicing, uprates Independent alternative on legacy frames
EthosEnergy ~3–4% Rotor repair, field services, generator work Largest pure-play independent provider
MTU Aero Engines ~2–4% Aeroderivative MRO and exchange engines Aviation-derived repair discipline
Sulzer ~2–3% Component repair, coatings, machining Deep metallurgical and coating capability
Chromalloy ~2–3% FAA- and PMA-style validated parts, hot section repair Cost-competitive parts alternative


Recent News & Developments

The following developments shaped competitive positioning in the Gas Turbine Services Market during the 2023–2025 window.

  • GE Vernova (March 2024): Announced a multi-year agreement covering more than 20 GW of installed capacity across Southeast Asia, bundling parts, outage execution, and remote monitoring under a single availability guarantee [15].
  • Siemens Energy (September 2024): Expanded its Berlin and Charlotte service capacity to address a service backlog that exceeded EUR 120 billion company-wide, citing gas turbine demand as the primary driver [15].


  • Mitsubishi Power (June 2024): Completed a 30% ammonia co-firing demonstration on a large-frame unit in Japan, supported by Green Innovation Fund allocation, validating a retrofit pathway for the regional fleet [22].
  • Baker Hughes (November 2023): Secured mechanical drive equipment and long-term service scope for Qatari North Field expansion trains, extending continuous-duty aeroderivative service commitments into the 2040s [11].
  • EthosEnergy (February 2025): Completed the acquisition of a European rotor repair facility, expanding independent capacity for legacy heavy-duty frames no longer prioritized by original manufacturers [12].
  • Germany Federal Ministry for Economic Affairs (February 2024): Confirmed the power plant strategy framework supporting up to 12.5 GW of hydrogen-ready gas capacity, requiring conversion-capable specifications at procurement [19].
  • Ansaldo Energia (August 2025): Launched a multi-OEM upgrade package targeting E- and F-class frames, offering heat rate improvement of up to 2.5 points on units outside manufacturer support programs [23].

Gas Turbine Services Market Report Scope

Parameter Detail
Market Scope Parts, field labor, overhaul, upgrades, retrofits, and digital service contracts for the global Gas Turbine Services Market
Study Period 2021–2035 (Historical 2021–2024; Base Year 2025; Forecast 2026–2035)
CAGR 5.1% (2026–2035)
Market Size Checkpoints USD 27.4 Billion (2025); USD 28.8 Billion (2026); USD 45.1 Billion (2035)
Fastest Growing Segments Remote Monitoring & Diagnostics (9.1% CAGR); 51–150 MW capacity class (6.6% CAGR); Asia-Pacific (6.9% CAGR)
Companies Profiled GE Vernova, Siemens Energy, Mitsubishi Power, Baker Hughes, Solar Turbines, Ansaldo Energia, EthosEnergy, MTU Aero Engines, Sulzer, Chromalloy
Valuation Currency USD, constant 2025 prices

FAQs

How should buyers structure warranty terms when entering the Gas Turbine Services Market as a first-time asset owner?
Negotiate parts warranties on a per-component basis rather than accepting a blanket outage warranty. Insist on liquidated damages tied to availability, not merely to workmanship defects [12].
What insurance implications follow from switching to an independent service provider?
Most underwriters accept validated third-party parts but require documented engineering qualification. Notify insurers before the first non-manufacturer outage, since undisclosed scope changes have voided machinery breakdown coverage in past claims [24].
Is an exchange-engine model or on-site overhaul better for aeroderivative units?
Exchange engines cut site outage duration from weeks to roughly five days, which suits operators with dispatch obligations. On-site overhaul costs less per event but risks extended revenue loss during peak pricing windows.
How do procurement teams evaluate bids in the Gas Turbine Services Market when scopes differ?
Normalize bids to cost per equivalent operating hour rather than per outage. This exposes hidden differences in parts lives and repair interval assumptions that headline pricing conceals [12].
What integration challenges arise when adding third-party monitoring to an existing control system?
Legacy control platforms often restrict data export under license terms. Budget for protocol gateways and confirm data-ownership clauses before installation, since retrofitting access after contract signature costs considerably more.
Which certifications matter most when qualifying a repair vendor?
Look for ISO 9001 alongside documented metallurgical laboratory capability and demonstrated coating qualification for the specific alloy family. Frame-specific repair validation matters more than any general quality certification [14].
Do capacity market revenues justify flexibility retrofits in the Gas Turbine Services Market?
In PJM and the U.K., yes at current clearing prices, with typical paybacks near three years [7]. In markets without capacity payments, retrofit economics depend entirely on ancillary service revenue and remain marginal.
Author
Author Author Profile Priya Nagrale LinkedIn Senior Research Analyst
With an experience of over five years in market research industry (Chemicals & Materials domain), I gather and analyze market data from diverse sources to produce results, which are then presented back to a client. Also, provide recommendations based on the findings. As a Senior Research Analyst, I perform quality checks (QC) for market estimations, QC for reports, and handle queries and work extensively on client customizations. Also, handle the responsibilities of client proposals, report planning, report finalization, and execution

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of regulatory databases, technical standards repositories, peer-reviewed engineering journals, and authoritative energy industry sources. Key sources included the US Energy Information Administration (EIA), International Energy Agency (IEA), Federal Energy Regulatory Commission (FERC), North American Electric Reliability Corporation (NERC), US Department of Energy (DOE) Gas Turbine Program databases, European Union Aviation Safety Agency (EASA) certification records, International Air Transport Association (IATA) engine maintenance statistics, VGBE PowerTech (European technical association for power and heat generation), American Society of Mechanical Engineers (ASME) technical journals and turbine standards, Gas Turbine World installation databases, World Energy Council power plant asset registers, International Renewable Energy Agency (IRENA) flexibility and grid integration reports, International Energy Forum (IEF) global gas demand datasets, BP Statistical Review of World Energy, International Gas Union (IGU) wholesale gas market reports, Power Engineering International plant databases, European Gas Turbine Association (EGTA) fleet statistics, National Association of Regulatory Utility Commissioners (NARUC) maintenance expenditure filings, US Environmental Protection Agency (EPA) emissions compliance databases for gas-fired assets, Flight Global aviation MRO fleet data, and national energy ministry reports from key markets (India Ministry of Power, China National Energy Administration, Saudi Arabia Ministry of Energy). These sources were used to collect installed capacity data, fleet aging statistics, Long-Term Service Agreement (LTSA) filings, emissions retrofit requirements, outage duration benchmarks, and maintenance expenditure trends for heavy-duty gas turbines, aeroderivatives, and industrial turbines.


Primary Research

To gather both qualitative and quantitative insights, supply-side and demand-side stakeholders were interviewed during the primary research phase. Supply-side sources included independent service providers (ISPs) like Wood Group, EthosEnergy, and Sulzer; component suppliers (blade, combustor, and hot gas path specialists); aftermarket parts distributors; and CEOs, VPs of Service Operations, Chief Technology Officers, regulatory compliance heads, and commercial directors from original equipment manufacturers (OEMs) like GE Vernova, Siemens Energy, and Mitsubishi Power. Demand-side sources included asset management heads from district energy and industrial cogeneration facilities, fleet managers from aviation lessors, procurement leads from combined cycle power plant operators, chief operating officers and plant managers from independent power producers (IPPs) and electric utilities, and maintenance directors from oil & gas supermajors and pipeline operators. Primary research confirmed Long-Term Service Agreement (LTSA) renewal timelines, validated market segmentation by service type (maintenance vs. overhaul cycles), and collected data on fleet modernization decisions, digital MRO adoption rates, and the transition from OEM dependence to independent service providers.

Primary Respondent Breakdown:

By Designation: C-level Primaries (30%), Director Level (32%), Others (38%)

By Region: North America (32%), Europe (25%), Asia-Pacific (33%), Rest of World (10%)


Market Size Estimation

Global market valuation was derived through service contract value mapping and installed base analysis. The methodology included:

Identification of 50+ key service providers and OEMs across North America, Europe, Asia-Pacific, Middle East & Africa, and Latin America

Service mapping across maintenance (routine/periodic), repair (minor/major), overhaul (minor/major), and spare parts supply categories

Turbine type classification across heavy-duty (>100 MW), aeroderivative (aviation-derived), and industrial (mechanical drive/cogeneration) segments

Analysis of reported and modeled annual service revenues specific to gas turbine maintenance portfolios, including Long-Term Service Agreements (LTSAs) and ad-hoc repair contracts

Coverage of service providers and OEMs representing 75-80% of global market share in 2024

Extrapolation using bottom-up (installed base × maintenance cost per fired hour × annual operating hours by country) and top-down (service provider revenue validation) approaches to derive segment-specific valuations for OEM vs. independent service provider channels, heavy-duty vs. aeroderivative fleets, and power generation vs. oil & gas end-use applications

Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.
















