Commercial P2P CDN Market (2026 – 2035)

Commercial P2P CDN Market Size, Share and Research Report By Component (Solutions, and Services), By Content Type (Video, and Non-Video), By Vertical (Media and Entertainment, Gaming, E-Commerce, BFSI, Education, and Other Verticals), By Revenue Model (Subscription-Based, Pay-Per-Use, and Ad-supported/Freemium), By End-User (SMEs, and Large Enterprises) And By Region (North America, Europe, Asia-Pacific, And Rest Of The World) – Industry Forecast Till 2035
ID: MRFR/ICT/26996-HCR 128 Pages Ankit Gupta Last Updated: October 01, 2026
Commercial P2P CDN Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)12.1%
2025 Market SizeUSD 2.49 Billion
2035 Market SizeUSD 7.80 Billion
Key Players
Akamai Technologies
Cloudflare
Microsoft
Tencent Cloud
Alibaba Cloud
Lumen Technologies
Opportunities
  • Mobile-First Video in Emerging Economies
  • Monetizing Peer Telemetry and Quality Analytics
  • Launch-Day Game Distribution Partnerships

Commercial P2P CDN Market Summary

The Commercial P2P Cdn Market was valued at USD 2.49 billion in 2025 and is projected to reach USD 2.79 billion in 2026, rising to USD 7.80 billion by 2035 at a CAGR of 12.1% over 2026–2035. Two catalysts anchor this outlook. Video now accounts for roughly two-thirds of global downstream internet traffic [1], and public broadband programs such as the USD 42.45 billion Broadband Equity, Access, and Deployment (BEAD) program in the United States [11] are enlarging the pool of connected viewers whose spare upload capacity can be pooled into delivery swarms.

Technology is changing underneath the market. Operators are moving away from origin-heavy, single-vendor edge networks toward hybrid CDN solutions that blend conventional points of presence with browser-based peer meshes built on WebRTC [4]. Akamai reported 24% year-over-year growth in its cloud-computing business [5], a signal that delivery vendors are folding peer modules into broader compute platforms rather than selling them as standalone add-ons.

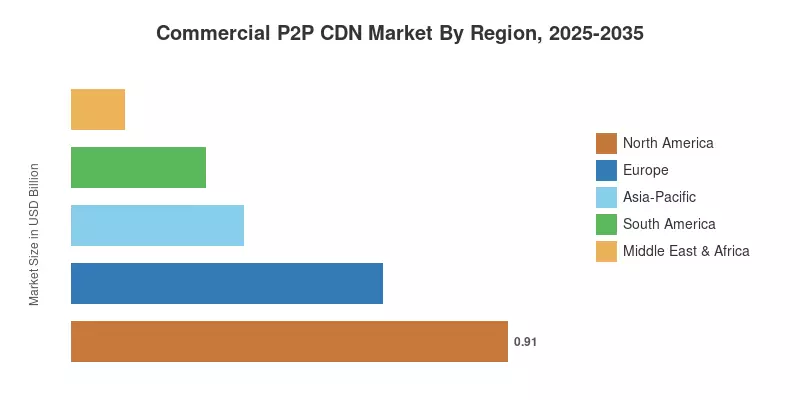
North America holds the largest position with a 36.5% share in 2025, led by OTT operators, studios and cloud-gaming hosts. Asia-Pacific is the fastest-growing region at a 14.3% CAGR, supported by mobile-first viewing in India, Indonesia and China. Europe ranks second with a 26.0% share, where gigabit targets under the EU Digital Decade program [10] improve residential upload conditions. Over the next decade, the Commercial P2P Cdn Market will reward vendors that pair peer efficiency with carrier-grade reliability.

Key Report Takeaways

• By Component

  • Solutions accounted for 57.9% of the Commercial P2P Cdn Market in 2025, anchored by platforms that bundle peer coordination, multi-CDN failover and analytics
  • Services are projected to expand at a 13.3% CAGR as buyers outsource onboarding, swarm tuning and round-the-clock security operations

• By Content Type

  • Video held a 71.5% share in 2025, supported by rising 4K and HDR bitrates
  • Non-Video delivery generated USD 0.71 billion in 2025 from software patches, static web assets and device firmware

• By Vertical

  • Media and Entertainment captured 43.9% of the Commercial P2P Cdn Market in 2025
  • Gaming is forecast to grow at a 16.6% CAGR, the fastest among all verticals

• By Revenue Model

  • Subscription-Based contracts represented a 57.5% share in 2025
  • Pay-Per-Use pricing is expected to rise at a 14.2% CAGR as buyers align spend with traffic peaks

• By End-User

  • Large Enterprises held a 72.4% share in 2025
  • SMEs are set to grow at a 13.7% CAGR through 2035

• By Region

  • North America led with a 36.5% share in 2025
  • Asia-Pacific is the fastest-growing region at a 14.3% CAGR
  • Europe ranked second with a 26.0% share

Market Size and Forecast (2021–2035)

Estimates for the Commercial P2P Cdn Market combine a bottom-up review of vendor revenues, disclosed contract values and traffic offload data with a top-down reconciliation against global CDN spending and video traffic volumes [1][5][6]. Historical figures for 2021–2024 draw on company filings and industry traffic studies, 2025 serves as the base year, and 2026–2035 values reflect a scenario-weighted forecast validated through interviews with streaming, gaming and enterprise IT buyers.
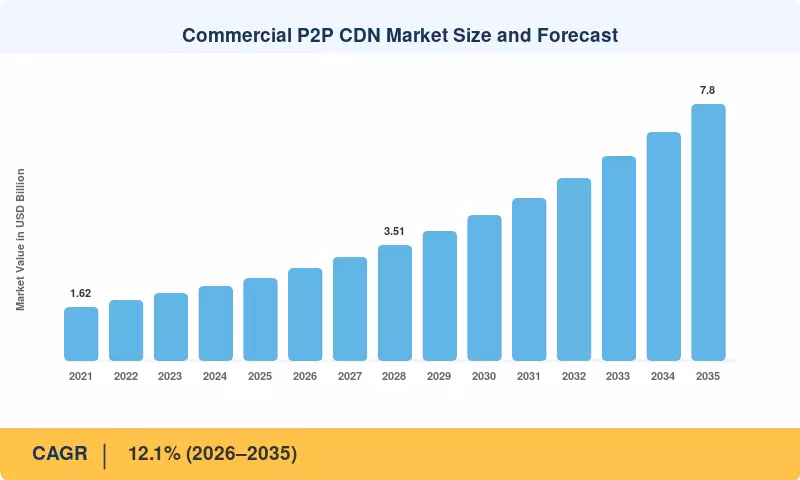
Commercial P2P CDN Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Surging 4K, HDR and live video traffic ~+2.4% Global; strongest in North America and Asia-Pacific Medium term (2–4 yr)
Rising edge egress costs pushing peer offload ~+2.0% North America, Europe Short term (≤2 yr)
Large game-update payloads and e-sports broadcasts ~+1.8% Global Medium term (2–4 yr)
Enterprise live video on corporate networks ~+1.5% North America, Europe Short term (≤2 yr)
Broadband and 5G expansion raising upload capacity ~+1.2% Asia-Pacific, Middle East & Africa, South America Long term (≥4 yr)
Browser-native WebRTC and open caching standards ~+0.9% Global Long term (≥4 yr)


Surging 4K, HDR and Live Video Traffic

According to sources, video accounts for around two-thirds of downstream internet traffic, and Ericsson projects that video will account for approximately three-quarters of mobile data traffic [2]. Segment requests during premieres and live sports are multiplied by 4K broadcasts faster than 12 Mbps. As audiences increase, peer swarms become more effective because each new viewer increases upload bandwidth. Because of this scaling characteristic, platforms have a cost curve that flattens at the exact moment that traditional edge costs increase.


Rising Edge Egress Costs

One of the most important infrastructure line items for streaming and SaaS companies is delivery. Cloudflare reported USD 479.1 million in sales for the first quarter of 2025 [6]. A rising portion of its portfolio consists of usage-metered edge services, which exposes customers to peak pricing. Operators are able to cap committed edge capacity due to vendor-reported peer offload of 50–70% for popular live events. Instead of viewing peer-assisted delivery as an engineering experiment, finance teams now assess it as a direct margin lever.


Game-Update Payloads and E-Sports Broadcasts

Newzoo estimated global games revenue at USD 187.7 billion for 2024 [8], and AAA titles routinely ship patches above 50 GB. Simultaneous worldwide release windows concentrate demand on single origins within hours. Peer sharding spreads those payloads across players already downloading the same build, improving regional parity. E-sports broadcasters add another demand layer, since synchronized feeds prevent spoiler gaps between regions, a priority reflected in Akamai's delivery work with Riot Games [20].

Enterprise Live Video on Corporate Networks

Hybrid work has turned company-wide town halls into routine video workloads, and branch WAN links were never sized for thousands of simultaneous streams. Microsoft's eCDN service uses in-office peering to reduce WAN load for Teams events [7], and vendor case studies commonly cite bandwidth reductions above 90% on internal broadcasts. This creates a procurement path through IT departments rather than media teams, broadening the buyer base considerably.

Broadband and 5G Expansion

Peer delivery depends on upload headroom, and that headroom is expanding. The NTIA's USD 42.45 billion BEAD program [11], India's revised BharatNet outlay of INR 1.39 lakh crore [12] and more than 2 billion global 5G connections tracked by GSMA [13] all add capable peers. Emerging regions gain the most because edge POP density there remains thin, leaving peers to fill coverage gaps that traditional CDNs have not economically served.

WebRTC and Open Caching Standards

The W3C WebRTC 1.0 Recommendation [4] removed the need for plugins, letting peer logic run inside standard browsers and smart-TV runtimes. ITU counts 5.5 billion internet users, about 68% of the world population [3], nearly all reachable through WebRTC-capable browsers. The Streaming Video Technology Alliance's Open Caching specification [16] adds a standard interface to ISP caches. Adoption compounds slowly, so the impact concentrates in later forecast years.

Restraints Impact Analysis

Negative impact values reflect the directional drag each restraint places on growth in the Commercial P2P Cdn Market. Like drivers, they overlap and should not be summed against the headline CAGR.

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
Security reviews and content-protection concerns ~−1.4% Global Medium term (2–4 yr)
Privacy rules treating IP addresses as personal data ~−1.1% Europe, India Short term (≤2 yr)
Asymmetric upload links and ISP traffic management ~−0.9% South America, Middle East & Africa, parts of Asia-Pacific Long term (≥4 yr)
Mobile data caps and battery concerns ~−0.7% Asia-Pacific, South America Medium term (2–4 yr)
Price competition from commoditized edge delivery ~−0.5% North America, Europe Short term (≤2 yr)


Security Reviews and Content Protection

Any design that converts viewer devices into distribution nodes is closely examined by security teams. Tampered portions, viewer IP disclosure, and DRM circumvention are among the issues. Operators are reluctant to sacrifice minor reliability risks for savings because Conviva's research indicates that viewers quickly quit sessions when quality deteriorates [17]. The majority of vulnerabilities are reduced by segment hashing and signed manifests, but security checks nevertheless lengthen business procurement cycles by three to six months.


Privacy Rules on Peer Discovery

Peer discovery naturally shares IP addresses with viewers, and the GDPR [14] regards them as personal data in many situations. The Digital Personal Data Protection Act 2023 [15] in India increases compliance exposure for platforms that serve Indian audiences by permitting penalties of up to INR 250 crore per violation category. Regional peer isolation and relay-only modes are now available from vendors; however, these features lower offload efficiency.


Asymmetric Upload Links

Residential broadband remains asymmetric across much of the world, with cable and DSL upload speeds often a tenth of download speeds. ITU data places fixed broadband below 2 subscriptions per 100 inhabitants in least-developed countries [3], and World Bank analysis confirms deep connectivity gaps [21]. Some ISPs also deprioritize peer traffic during congestion, limiting peer density exactly where edge coverage is weakest.

Mobile Data Caps and Battery Concerns

Mobile viewers resist apps that upload data on metered plans or drain batteries. Smartphones drive the bulk of mobile traffic growth [2], and in price-sensitive markets many users still buy daily or weekly data packs. Most SDKs therefore disable uploads on cellular connections by default, which cuts peer availability by an estimated 30–40% on mobile-heavy audiences.

Commoditized Edge Delivery Pricing

Conventional delivery pricing keeps falling as hyperscalers bundle it with storage and compute. Akamai's 2024 annual report shows delivery revenue under pressure even as security and compute lines expand [5]. Where per-GB rates on high-volume contracts drop below USD 0.005, the savings case for peer offload narrows, particularly for mid-sized publishers without heavy live traffic.

Commercial P2P CDN Market Opportunities

Mobile-First Video in Emerging Economies

South and Southeast Asia and Sub-Saharan Africa combine fast-growing mobile audiences with sparse edge infrastructure. As BharatNet extends fiber to rural India [12] and 5G fixed wireless access spreads, peers can serve cricket, regional-language OTT and education content where POP buildouts remain uneconomic. Vendors that localize SDKs for low-end Android devices and partner with regional telcos stand to capture an outsized share of the Commercial P2P Cdn Market.

Monetizing Peer Telemetry and Quality Analytics

Every peer session generates granular data on throughput, device mix and network conditions. Packaging this telemetry into quality-of-experience dashboards, ISP performance benchmarks, and audience heatmaps creates a recurring analytics revenue line independent of delivered gigabytes. Privacy-safe aggregation, aligned with GDPR requirements [14], makes these data products saleable to advertisers and rights holders.

Launch-Day Game Distribution Partnerships

Game launchers and console storefronts face predictable but extreme demand on release days. Revenue-sharing agreements that embed peer delivery directly into launchers could turn a cost center into a shared-savings model. With game revenue above USD 187 billion [8], even modest penetration of patch distribution represents a meaningful new contract pool.

ISP-Integrated Caching and Peering

Telecom operators increasingly want peer traffic kept inside their networks to avoid transit costs. Combining peer meshes with Open Caching nodes [16] enables revenue-sharing between content providers and ISPs, converting a historical point of friction into a joint product. Early movers in this model gain distribution advantages that are difficult to replicate.

Campus and Enterprise Knowledge Video

Universities and large employers distribute lecture recordings, compliance training and product videos to thousands of simultaneous users. Seeding content from campus labs or office devices lowers WAN and cloud costs, and SaaS portals now make deployment feasible for teams without network specialists [7].

Commercial P2P CDN Market Future Outlook

AI-Driven Swarm Orchestration

Machine-learning models will increasingly decide which peers serve which segments, predicting churn, device capability and network congestion in real time. Vendors already use popularity forecasting to pre-position content. By the early 2030s, autonomous orchestration should push average offload ratios higher while reducing rebuffering, narrowing the reliability gap with pure edge delivery that still deters conservative buyers [17].

Platform Economics and Usage-Based Pricing

Pricing is migrating toward blended models: flat subscriptions for baseline traffic with usage-based rates for event spikes. Cloudflare's growth in usage-metered edge services [6] illustrates buyer appetite for spend that tracks demand. Expect peer delivery to be sold increasingly as a feature inside edge-compute bundles rather than as a separate product line.

Energy Efficiency and Sustainability Reporting

The IEA estimates data transmission networks consumed 260–360 TWh in 2022, around 1–1.5% of global electricity use [9]. As corporate sustainability disclosure tightens, buyers will ask vendors to quantify energy avoided when traffic shifts from backbone transit to local bandwidth sharing networks. Credible measurement methods could become a procurement differentiator by the late 2020s.

Telecom Collaboration and Standards

Standardization will shape the decade's competitive structure. Open Caching [16] and WebRTC [4] lower integration costs, while ISP partnerships determine whether peer traffic is welcomed or throttled. Vendors that secure operator alliances early will shape how the Commercial P2P Cdn Market interfaces with network infrastructure through 2035.

Regional Market Share Analysis

Region Key Metric (2025, one per row) Primary Investment Themes
North America 36.5% share OTT live sports, cloud gaming, enterprise live video
Europe 26.0% share Public-broadcaster streaming, privacy-compliant peering, gigabit rollouts
Asia-Pacific 14.3% CAGR (2026–2035) Mobile-first OTT, cricket and e-sports, game distribution
South America 11.4% CAGR (2026–2035) Football streaming, mobile video, piracy displacement
Middle East & Africa USD 0.11 Billion Vision 2030 digital content, 5G rollout, sports rights
Total USD 2.49 Billion —

Regional demand in the Commercial P2P Cdn Market follows a clear pattern: mature streaming economies generate the largest revenue pools, while mobile-first regions generate the fastest growth.


North America

Country Key Metric (one per row) Key Driver
US 84.6% share of region Live sports streaming and cloud gaming scale
Canada 11.9% CAGR Enterprise video and bilingual OTT services
Mexico USD 0.05 Billion Mobile video and football streaming rights


The United States concentrates the region's largest buyers: streaming platforms, game publishers and hyperscale enterprises running internal broadcasts. Several data shows streaming consistently exceeding 40% of US television viewing time [18], and live sports rights moving online create exactly the synchronized, high-concurrency events where peers deliver the most value. The BEAD program [11] will raise rural upload capacity, extending viable peer coverage beyond metro areas. Canada and Mexico follow with smaller but steadily expanding demand in the Commercial P2P Cdn Market.

Europe

Country Key Metric (one per row) Key Driver
Germany 21.8% share of region Public-broadcaster streaming and enterprise video
UK USD 0.14 Billion Live sports OTT and gaming studios
France 11.7% CAGR Fiber-to-the-home penetration
Italy 9.4% share of region Football streaming rights
Spain 12.3% CAGR High fiber upload speeds
Nordic Countries USD 0.05 Billion Early adoption of enterprise peer delivery
Russia 10.2% CAGR Domestic platform localization
Rest of Europe 14.5% share of region Regional OTT launches


Europe's growth rests on dense fiber deployments that provide the symmetric upload speeds peer delivery favors, and the Digital Decade target of gigabit connectivity for all households by 2030 [10] strengthens that foundation. Ofcom reports continued migration of UK viewing to online services [22]. GDPR obligations [14] shape product design, pushing vendors toward regional peer isolation and consent-based participation, which adds cost but also builds trust with public broadcasters.

Asia-Pacific

Country Key Metric (one per row) Key Driver
China 38.6% share of region Large domestic video and live-commerce platforms
India 17.8% CAGR Mobile OTT and cricket streaming
Japan USD 0.12 Billion Anime streaming and console gaming
South Korea 14.1% CAGR E-sports and high-speed broadband
ASEAN 15.9% CAGR Mobile-first viewing in Indonesia and Vietnam
Rest of Asia-Pacific 8.3% share of region Australian OTT and gaming demand


Asia-Pacific combines the world's largest mobile audiences with uneven edge infrastructure, an ideal setting for peer delivery. Chinese cloud providers have long used peer-assisted techniques for live streaming at massive concurrency. India's growth reflects cricket streaming peaks and BharatNet rural fiber [12], while South Korea's e-sports ecosystem demands tightly synchronized feeds. GSMA expects Asia-Pacific to lead global 5G connection additions [13].

South America

Country Key Metric (one per row) Key Driver
Brazil 58.4% share of region Football streaming and mobile video
Argentina 10.9% CAGR Cost-sensitive OTT platforms
Rest of South America USD 0.03 Billion Regional broadcaster digitization


Brazil dominates regional demand, driven by football streaming and a large, digitally engaged population. Local currency volatility makes dollar-denominated edge contracts expensive, strengthening the case for peer offload. World Bank data on uneven fixed broadband access [21] explains slower adoption outside major cities, where asymmetric links limit peer contribution.

Middle East & Africa

Country Key Metric (one per row) Key Driver
Saudi Arabia 15.6% CAGR Vision 2030 entertainment and gaming investment
UAE 21.7% share of region Regional media hubs and 5G coverage
South Africa USD 0.02 Billion Sports streaming and enterprise video
Egypt 14.8% CAGR Arabic-language OTT growth
Rest of MEA 19.5% share of region Mobile video across Sub-Saharan Africa


Saudi Arabia's Vision 2030 program channels significant investment into gaming, e-sports and entertainment, while the Communications, Space and Technology Commission reports rising broadband speeds [19]. The UAE serves as a regional media and data-center hub. Across Sub-Saharan Africa, limited edge presence makes peer delivery attractive, though asymmetric links remain a constraint.

Commercial P2P CDN Market By Region, 2025-2035

Commercial P2P CDN Market Segmentation

By Component

Segment Key Metric (2025, one per row) Primary Demand Driver
Solutions 57.9% share Unified consoles for peer coordination, failover and analytics
Services 13.3% CAGR Managed onboarding, performance audits and security operations


Solutions form the revenue backbone of the Commercial P2P Cdn Market, since large streaming services prefer platforms that slot into existing DevOps tooling and manage peer logic alongside conventional edges. Services, though smaller, grow faster because many buyers lack specialists to tune swarms against content popularity curves. Integrators increasingly bundle 24×7 security monitoring and performance audits, lifting contract values even as core software penetration matures.

By Content Type

Segment Key Metric (2025, one per row) Primary Demand Driver
Video 71.5% share 4K, HDR and live event concurrency
Non-Video USD 0.71 Billion Software patches, web assets and IoT firmware


Video dominates the Commercial P2P Cdn Market and also grows fastest, because adaptive bitrate ladders and higher resolutions multiply segment requests that peers can cache efficiently. Non-Video delivery earns steadier adoption driven by software updates and firmware rollouts, where checksum validation matters more than latency. Demand there spikes around specific events, such as operating-system releases or major game launches, rather than daily viewing patterns.

By Vertical

Segment Key Metric (2025, one per row) Primary Demand Driver
Media and Entertainment 43.9% share OTT live sports and premieres
Gaming 16.6% CAGR Large patches and e-sports broadcasts
E-Commerce USD 0.27 Billion Product-media bursts during sales events
BFSI 12.4% CAGR Internal research portals and training videos
Education 5.8% share Lecture video distribution
Other Verticals USD 0.21 Billion Government and healthcare communications


Media and Entertainment remains the largest vertical in the Commercial P2P Cdn Market, driven by OTT platforms managing sports and premiere peaks. Gaming grows fastest as AAA updates exceed 50 GB and simultaneous global releases strain single origins. E-Commerce, BFSI and Education adopt peers for narrower workflows such as product-asset bursts, internal video and lectures, although security evaluations slow rollouts in regulated sectors.

By Revenue Model

Segment Key Metric (2025, one per row) Primary Demand Driver
Subscription-Based 57.5% share Predictable monthly budgeting
Pay-Per-Use 14.2% CAGR Alignment of spend with unpredictable peaks
Ad-supported/Freemium USD 0.39 Billion Low-cost entry for smaller publishers


Subscription-Based contracts lead the Commercial P2P Cdn Market because finance teams value stable forecasting. Pay-Per-Use grows fastest as event-driven streamers and seasonal retailers burst without over-provisioning. Ad-supported/Freemium tiers serve publishers whose margins fluctuate with advertising rates, using peer offload to protect profitability. Blended plans that pair flat baselines with usage overages are emerging as a practical compromise.

By End-User

Segment Key Metric (2025, one per row) Primary Demand Driver
SMEs 13.7% CAGR Self-service portals and embed scripts
Large Enterprises 72.4% share Multi-region OTT, studios and cloud gaming


Large Enterprises hold most revenue in the Commercial P2P Cdn Market, integrating peers into CI/CD pipelines and real-time analytics suites. SMEs grow faster as platform simplification lowers the skill barrier: self-service portals generate embed scripts automatically, and SaaS dashboards display peer heatmaps that non-specialists can interpret. Mid-sized game studios and education providers form the leading edge of this broader adoption wave.

Competitive Benchmarking

The Commercial P2P Cdn Market shows medium concentration, with an estimated Herfindahl-Hirschman Index of 1,100–1,300 and a top-five share of roughly 45–52%. Established CDN and cloud providers dominate revenue by bundling peer capabilities into broader platforms, while specialist vendors compete on offload efficiency, enterprise integration and live-event performance. Consolidation continues as weaker delivery players exit and incumbents absorb their customer contracts.

Company Est. Revenue Share Range Key Offerings for Commercial P2P Cdn Market Strategic Positioning
Akamai Technologies ~13–17% Edge delivery with peer-assist integrations, cloud compute Full-stack edge leader expanding via acquisitions
Cloudflare ~10–13% Usage-metered edge network, streaming and edge functions Developer-centric platform with global reach
Microsoft ~7–10% eCDN for Teams and enterprise live events Enterprise distribution through productivity suite
Tencent Cloud ~6–9% Live-streaming acceleration with peer assistance Scale leader in Chinese live video and gaming
Alibaba Cloud ~5–8% Peer-assisted CDN for video and e-commerce Commerce-linked delivery across Asia
Lumen Technologies ~4–6% Mesh delivery and network services Carrier-backed hybrid delivery
CDNetworks ~3–5% Hybrid CDN and live acceleration Asia-Pacific and cross-border strength
Kollective Technology ~2–4% Enterprise peer delivery for video and software Enterprise IT specialist
Hive Streaming ~2–4% Enterprise video distribution and analytics Corporate communications focus
System73 ~1–3% Edge-mesh overlay for live OTT Live sports and large-audience specialist


Recent News & Developments

  • NTIA (June 2023): Announced state allocations under the USD 42.45 billion BEAD program, expanding the base of households with upload capacity suited to peer delivery [11]
  • Government of India (August 2023): Enacted the Digital Personal Data Protection Act, introducing consent and breach obligations that shape peer-discovery design for Indian audiences [15]
  • European Commission (February 2024): The Digital Services Act became fully applicable to all intermediary services, raising transparency expectations for delivery platforms operating in the EU [10]
  • Akamai (February 2024): Unveiled its Gecko distributed cloud initiative, placing compute closer to users and strengthening its combined edge and peer-assist proposition [5]
  • Edgio (September 2024): Filed for Chapter 11 protection, signalling consolidation pressure on mid-tier delivery providers [5]
  • Akamai (December 2024): Agreed to acquire select Edgio customer contracts, absorbing media and streaming accounts into its platform [5]
  • Cloudflare (May 2025): Reported Q1 2025 revenue of USD 479.1 million, reflecting continued demand for usage-based edge services [6]

Commercial P2P CDN Market Report Scope

Parameter Details
Market Scope Commercial P2P Cdn Market revenue from solutions and services across content types, verticals, revenue models, end-users and regions
Study Period 2021–2035 (Historical: 2021–2024; Base Year: 2025; Forecast: 2026–2035)
CAGR 12.1% (2026–2035)
Market Size checkpoints USD 2.49 Billion (2025); USD 2.79 Billion (2026); USD 4.41 Billion (2030); USD 7.80 Billion (2035)
Fastest Growing Segments Gaming (Vertical); Pay-Per-Use (Revenue Model); SMEs (End-User); Asia-Pacific (Region)
Companies Profiled Akamai Technologies, Cloudflare, Microsoft, Tencent Cloud, Alibaba Cloud, Lumen Technologies, CDNetworks, Kollective Technology, Hive Streaming, System73
Valuation Currency USD (Billion)

FAQs

How should buyers run a proof of concept with a Commercial P2P Cdn Market vendor?
Test on a live event with several thousand concurrent viewers, since offload ratios only stabilize at scale. Compare rebuffering, startup time and peer share against the incumbent CDN over identical sessions [17].
Does peer-assisted delivery work on smart TVs and set-top boxes?
Support depends on the device runtime. Modern smart-TV browsers handle WebRTC well, while older set-top boxes often lack memory for peer caching [4]. Vendors fall back to standard edge delivery on unsupported devices without visible disruption.
Which contract terms matter most in Commercial P2P Cdn Market procurement?
Tie SLAs to the combined delivery path rather than the peer layer alone, and require transparent offload reporting. Usage clauses should cap overage rates during unplanned viral spikes [6].
Can peer delivery meet low-latency needs for live betting feeds?
Only partially. Mesh delivery with chunked CMAF can hold latency near 3–5 seconds, but sub-second betting feeds still rely on WebRTC-based origin distribution [16].
How do telecom operators view growth in the Commercial P2P Cdn Market?
Operators accept peer traffic when it stays inside their networks. Localized peer selection avoids costly transit links, which is why several ISPs now trial joint deployments with open caching nodes [16].
What skills do in-house teams need to operate peer delivery?
Most platforms are SDK-driven, so teams need player integration and analytics skills rather than deep network engineering. Staff should understand segment duration choices, because they strongly influence peer efficiency [7].
Which emerging use case could reshape the Commercial P2P Cdn Market after 2030?
Distributing large on-device AI model files is a strong candidate. Models already reach several gigabytes, and peer sharing within offices or campuses can sharply cut repeated downloads [7].
Author
Author Author Profile Ankit Gupta LinkedIn Team Lead - Research
Ankit Gupta is a seasoned market intelligence and strategic research professional with over six plus years of experience in the ICT and Semiconductor industries. With academic roots in Telecom, Marketing, and Electronics, he blends technical insight with business strategy. Ankit has led 200+ projects, including work for Fortune 500 clients like Microsoft and Rio Tinto, covering market sizing, tech forecasting, and go-to-market strategies. Known for bridging engineering and enterprise decision-making, his insights support growth, innovation, and investment planning across diverse technology markets.
Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Global Diameter Signaling Market
Case Study
Information and Communications Technology
Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.


















