Cash Management System Market (2026 - 2035)

现金管理系统市场研究报告信息按组件类型(服务和软件)、产品类型(支票清算、采购卡、零售和批发市场、账户对账、控制支出、信息报告、电汇、自动清算和活期存款账户)、部署(本地和云)、企业(中小型企业和大型企业)、最终用户(零售、银行和非银行服务)地区(北美、欧洲、亚太地区)划分 - 预测至 2032 年
ID: MRFR/ICT/7130-HCR 111 Pages Ankit Gupta Last Updated: September 03, 2026
Cash Management System Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)7.45%
2025 Market SizeUSD 21.85 Billion
2035 Market SizeUSD 43.20 Billion
Key Players
Oracle
FIS
SAP
Fiserv
Kyriba
ACI Worldwide
Opportunities
  • SME Cloud Adoption
  • Embedded Treasury and Banking-as-a-Service
  • Emerging-Market Digital Banking

Cash Management System Market Summary

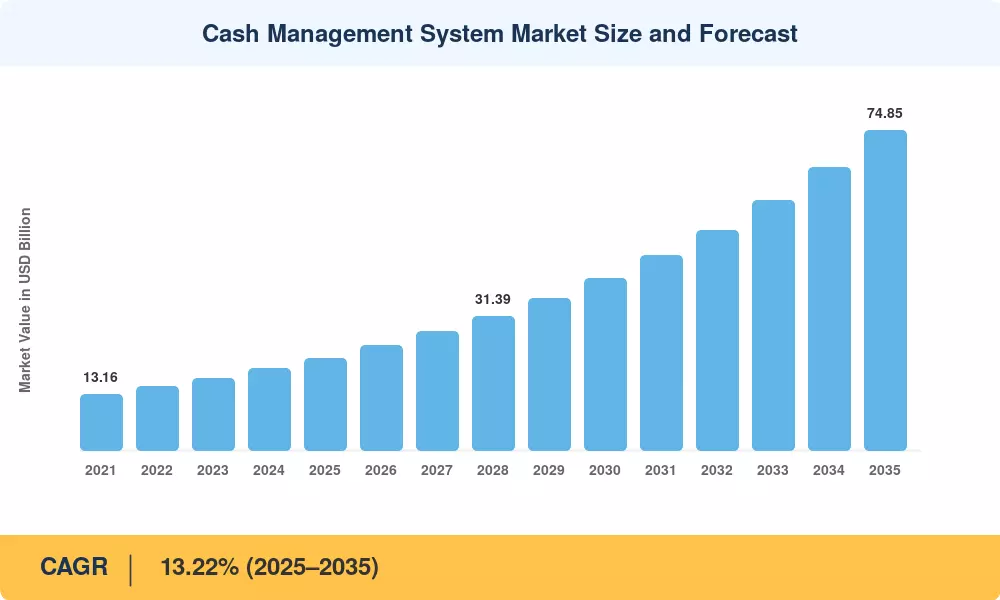
现金管理系统市场在2025年达到了218.5亿美元,并预计在2026年以234.5亿美元开启预测窗口,随后到2035年攀升至432.0亿美元,在2026年至2035年期间以7.45%的年均增长率增长。两个催化剂支撑着这一轨迹:ISO 20022实时支付轨道的全球推广和更严格的巴塞尔IV流动性压力测试规则,迫使财务团队证明始终可见的现金流。财务领导者不再将现金监督视为后台工作——它已成为与营运资金、欺诈风险和ESG报告相关的董事会级别的学科。

传统的电子表格对账和分隔的银行接口正在被云原生解决方案所取代,这些解决方案连接银行、企业资源规划(ERP)和金融科技API。在削减IT成本和提高预测精度的努力中,现金处理的自动化正在进行中。美国企业的资产负债表上仍有1.76万亿美元的被困营运资金,因此对端到端财务现金解决方案的需求仍然结构性强劲,基于AI的现金流预测正从试点项目转向生产部署。

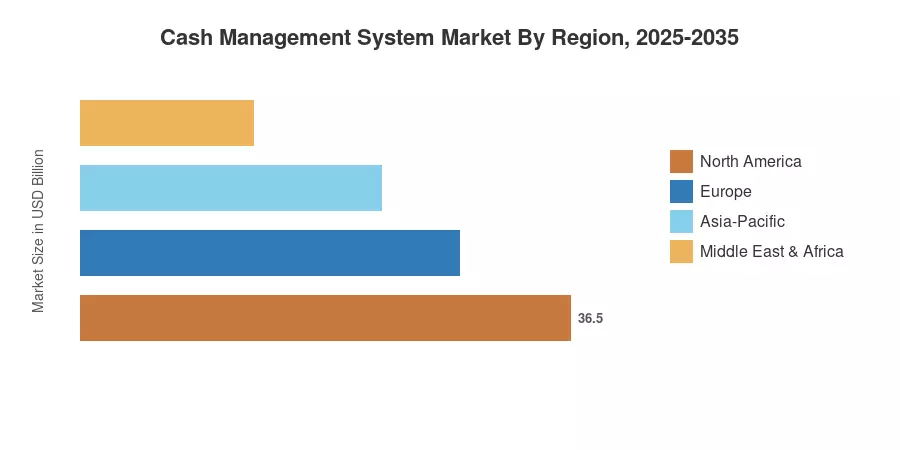
北美是最大的市场,2025年市场份额为41.5%,这得益于强大的金融基础设施和早期实施的商业现金控制。亚太地区是增长最快的区域,年均增长率为14.05%,其次是受益于监管驱动的财务改革的欧洲。那些掌握互操作性的供应商将在未来十年中获胜。

第二部分 — 关键报告要点

按组件划分

  • 云部署在2025年占据了现金管理系统市场约67%的份额,因为财务团队逐步淘汰了本地堆栈
  • 现金流预测工具以17.6%的年均增长率扩展,是现金管理系统市场中增长最快的操作类型细分市场

按最终用户划分

  • 银行、金融服务和保险(BFSI)在2025年产生了近59亿美元的现金管理系统价值,保持领先地位
  • 零售和电子商务是到2035年增长最快的最终用户垂直行业,年均增长率为12.4%

按区域划分

第三部分 — 市场规模和预测(2021–2035)

市场规模结合了自下而上的供应商收入跟踪与自上而下的财务技术支出基准,经过银行基础设施数据的校准,并与企业软件接受调查进行交叉核对。历史年份(2021-2024)为报告的财务数据;2025年为基准年;2026-2035年为MRFR的预测值。

现金管理系统市场规模和预测
Our Impact
Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals
Partnering with 2000+ Global Organizations Each Year
30K+ Citations by Top-Tier Firms in the Industry
 

驱动因素影响分析

驱动因素 ~% 对CAGR的影响 地理相关性 影响时间线 参考
ISO 20022 实时支付通道 21% 全球 短期  
基于AI的现金流预测 19% 北美,欧洲 中期  
巴塞尔IV流动性压力测试 16% 欧洲,北美 短期  
云原生平台迁移 15% 全球 中期  
营运资金优化压力 12% 北美,亚太 长期  
开放银行和金融科技API 10% 欧洲,亚太 中期  
欺诈和网络安全要求 7% 全球 长期  


ISO 20022 实时支付通道

全球向ISO 20022消息的迁移是自动现金处理需求的最强驱动因素。SWIFT的共存期将在2025年11月结束,迫使银行和企业采用更丰富的数据格式,以实现结构化汇款和即时对账。美国联邦储备的FedNow服务自2023年起上线,处理到2025年不断上升的即时支付量,能够原生解析ISO 20022数据的财务现金解决方案已成为采购的基本要求。

基于AI的现金流预测

机器学习预测正在从实验转向必需。供应商报告称,当AI模型取代基于规则的预测时,预测准确性提高了20-30%,直接改善了企业现金控制。美国企业的营运资金锁定在1.76万亿美元,即使是适度的准确性提升也能释放出有意义的流动性,使现金流管理工具成为首席财务官的投资优先事项。

巴塞尔IV流动性压力测试

巴塞尔IV修订的流动性覆盖和净稳定资金要求将在2025-2028年逐步实施,迫使银行展示细致的实时现金头寸。这一监管压力推动金融机构朝向能够进行日内流动性监测和自动压力测试报告的复杂财务现金解决方案发展。

云原生平台迁移

本地财务工作站的退役正在加速。云平台降低了基础设施成本并缩短了部署周期。财务领导者越来越倾向于基于订阅的自动现金处理,而不是资本密集型的安装,从而扩大了可服务市场的基础,包括中型市场公司。

Restraints Impact Analysis

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
Data security and breach exposure 28% Global Long-term
Integration complexity with legacy ERPs 24% North America, Europe Medium-term
High switching and implementation costs 19% Global Short-term
Shortage of skilled treasury technologists 16% Asia-Pacific, MEA Medium-term
Fragmented cross-border banking standards 13% Europe, South America Long-term


Data Security and Breach Exposure

Cash systems concentrate sensitive financial data, making them prime targets. The cost of a financial-sector data breach averaged USD 6.08 million in 2024, and treasury teams remain cautious about exposing payment infrastructure to cloud and API surfaces, slowing some enterprise cash control deployments.

Integration Complexity with Legacy ERPs

Many corporations run decades-old ERP installations that resist clean API connectivity. Stitching modern cash flow management tools into these environments demands costly middleware and custom development, extending implementation timelines and deterring risk-averse buyers.

High Switching and Implementation Costs

Replacing an entrenched treasury platform carries substantial cost and operational risk. Implementation fees, data migration, and staff retraining can run into seven figures for large enterprises, anchoring incumbents and lengthening sales cycles for new automated cash handling vendors.


Cash Management System Market Opportunities

SME Cloud Adoption

Small and medium enterprises represent the largest untapped pool of demand. As cloud pricing falls and onboarding simplifies, lightweight cash flow management tools designed for lean finance teams open a high-growth segment historically priced out of treasury technology

Embedded Treasury and Banking-as-a-Service

Banking-as-a-service lets software vendors embed payments and cash visibility directly into ERP and vertical platforms. This blurs the line between treasury software and banking, creating new revenue models for vendors that position enterprise cash control as a native platform feature

Emerging-Market Digital Banking

Asia-Pacific, Africa, and Latin America are leapfrogging legacy banking infrastructure. Rapid digital-bank rollouts and government real-time payment schemes — India's UPI, Brazil's Pix — create greenfield demand for treasury cash solutions among newly formalized corporates

Cash-Flow Data Monetization

The transaction and forecasting data generated by cash systems hold standalone value. Vendors can monetize anonymized liquidity benchmarks, credit-scoring inputs, and working-capital analytics, turning ATM cash management and treasury data exhaust into a recurring revenue line.

ESG and Sustainable Treasury Reporting

Boards increasingly require treasury teams to track ESG-linked financing and sustainable cash allocation. Platforms that bake ESG reporting into automated cash handling workflows can capture compliance-driven budget


Cash Management System Market Future Outlook

AI and Autonomous Treasury

By the early 2030s, treasury operations will trend toward autonomous cash management — systems that forecast, sweep, and fund positions with minimal human input. AI-based cash-flow forecasting will mature into prescriptive engines that recommend liquidity actions, making cash flow management tools indispensable to the modern finance function.

Platform Economics and Consolidation

The vendor landscape will consolidate around interoperable platforms. As switching costs and integration complexity favor scale, leading vendors will expand through acquisition, and embedded treasury models will redistribute value toward whoever owns the enterprise cash control layer.

Real-Time Everything

The decade ahead belongs to instant settlement. With over 70 countries operating real-time payment schemes by 2025, treasury cash solutions must process continuous, 24/7 cash flows. ATM cash management and physical-cash logistics will increasingly integrate with digital rails into unified visibility layers.

ESG-Linked Cash Governance

Sustainability reporting will reshape treasury mandates. Regulators and boards will expect cash allocation tied to ESG criteria, and automated cash handling platforms that embed sustainability metrics will capture compliance-driven budget through the back half of the forecast period.


Cash Management System Market Segmentation

By Component

The Cash Management System Market splits cleanly between solutions and the services that deploy them.

Segment 2025 Share (%) Primary Demand Driver
Solution 66.5 Platform standardization
Services 33.5 Implementation and support


Solutions dominate as corporates prioritize core platform capability, while services grow faster as complex integrations demand specialist consulting. The services tier benefits directly from the integration challenges that slow some enterprise cash control rollouts.

By Organization Size

Segment CAGR (%) Primary Demand Driver
Large Enterprises 6.1 Multi-entity complexity
SMEs 14.8 Affordable cloud tooling


Large enterprises hold the revenue majority, but SMEs are the growth story — falling cloud prices put credible cash flow management tools within reach of lean finance teams for the first time.

By Deployment Mode

Segment 2025 Share (%) Primary Demand Driver
Cloud 67.0 Lower IT overhead
On-Premise 33.0 Data sovereignty needs


Cloud deployment leads decisively and continues to gain share as vendors retire on-premise roadmaps. On-premise persists mainly where data-residency rules or security policy require local control.

By Operation Type

Segment 2025 Share (%) Primary Demand Driver
Cash-Flow Forecasting 35.0 AI accuracy gains
Corporate Liquidity Management 29.5 Basel IV pressure
Receivables & Payables 21.0 Working-capital focus
Other Operations 14.5 Niche workflows


Cash-flow forecasting is the largest and fastest-expanding operation type as AI lifts accuracy. Corporate liquidity management follows, propelled by regulatory stress-testing demands.

By End-User Industry

Segment Value (USD B) Primary Demand Driver
BFSI 5.90 Regulatory compliance
IT & Telecom 3.85 Multi-currency operations
Retail & E-commerce 3.40 Transaction volume
Manufacturing 3.10 Supply-chain finance
Others 5.60 Broad digitization


BFSI remains the anchor vertical given its regulatory burden and cash intensity. Retail and e-commerce grow fastest as transaction volumes and omnichannel payments demand sharper cash visibility.

Regional Market Share Analysis

Region 2025 Share (%) Primary Investment Themes
North America 41.5 Real-time rails, AI forecasting
Europe 27.0 Basel IV compliance, open banking
Asia-Pacific 21.0 Digital banking, SME adoption
South America 6.5 Pix-driven modernization
Middle East & Africa 4.0 Banking digitization
Total 100.0

The Cash Management System Market shows clear regional concentration, with North America and Europe together holding the majority of revenue, while Asia-Pacific drives incremental growth.


North America

Country Share of Region (%) Key Driver
US 82.0 FedNow adoption
Canada 12.5 Real-time Rail launch
Mexico 5.5 SPEI modernization


North America anchors the Cash Management System Market on the strength of FedNow's expanding instant-payment footprint and aggressive AI forecasting adoption among large banks. US corporates lead working-capital optimization programs, and Canada's Real-Time Rail rollout reinforces regional treasury cash solutions demand.

Europe

Country Value (USD B) Key Driver
Germany 1.45 Industrial treasury demand
UK 1.30 Open banking maturity
France 0.98 Corporate liquidity focus
Italy 0.62 SME digitization
Spain 0.55 Banking consolidation
Nordic Countries 0.48 Cashless economy leads
Russia 0.30 Domestic payment systems
Rest of Europe 0.22 Cross-border harmonization


Europe's market reflects Basel IV compliance pressure and the world's most mature open-banking regime under PSD2. German and UK corporates lead enterprise cash control investment, while Nordic economies — already near-cashless — push advanced automated cash handling adoption.

Asia-Pacific

Country CAGR (%) Key Driver
China 14.8 Digital yuan rollout
India 16.5 UPI corporate expansion
Japan 9.2 Treasury modernization
South Korea 11.0 Open banking mandate
ASEAN 15.2 Cross-border QR linkage
Rest of Asia-Pacific 12.0 Banking digitization


Asia-Pacific is the growth engine of the Cash Management System Market, led by India's extension of UPI rails into corporate payments and China's digital yuan pilots. ASEAN's cross-border QR payment linkages create fresh demand for interoperable cash flow management tools.

South America

Country Share of Region (%) Key Driver
Brazil 62.0 Pix instant payments
Argentina 18.5 Inflation-driven cash control
Rest of South America 19.5 Banking digitization


South America's expansion rides on Brazil's Pix, one of the world's most successful instant-payment schemes, which has normalized real-time settlement and pushed corporates toward modern treasury cash solutions. Argentina's high-inflation environment intensifies the need for tight enterprise cash control.

Middle East & Africa

Country Value (USD B) Key Driver
Saudi Arabia 0.28 Vision 2030 fintech push
UAE 0.26 Banking innovation hub
South Africa 0.18 PayShap real-time rails
Egypt 0.10 Financial inclusion drive
Rest of MEA 0.05 Gradual digitization


The Middle East & Africa region is small but accelerating. Saudi Arabia's Vision 2030 fintech agenda and the UAE's role as a regional banking hub drive automated cash handling uptake, while South Africa's PayShap rails extend real-time capability across the continent.

Cash Management System Market By Region, 2025-2035
 

Competitive Benchmarking

The Cash Management System Market is moderately concentrated with an estimated HHI in the 900 - 1,200 range. The top five vendors together account for between 38–44% of sales, with a lengthy tail of regional and niche specialists. The competition is not only on pricing but on interoperability, AI capability and depth of bank connectivity.

Company Est. Revenue Share Range Key Offerings for Cash Management System Market Strategic Positioning
Oracle ~9–12% Treasury and cash modules in the ERP suite Enterprise incumbent
FIS ~8–11% Banking and treasury cash platforms Bank-channel leader
SAP ~7–10% Integrated treasury management ERP-embedded reach
Fiserv ~6–9% Cash and payments solutions Financial institution focus
Kyriba ~5–8% Cloud treasury and liquidity platform Cloud-native specialist
ACI Worldwide ~4–6% Real-time payments and cash tools Payments infrastructure
Nomentia ~3–5% European treasury and cash platform Regional cloud player
Bottomline Technologies ~3–5% Payment and cash management software Mid-market specialist
GTreasury ~2–4% Treasury and risk management platform Integration-focused vendor
Coupa ~2–4% Spend and cash flow management tools Source-to-pay adjacency


Revenue share ranges are MRFR estimates and are not intended to sum precisely. Source: MRFR analysis, 2026.


Recent News & Developments

  • Kyriba (March 2025): Launched an expanded AI forecasting suite, sharpening cash flow management tools' accuracy for multi-entity corporates.
  • FIS (November 2024): Announced enhanced ISO 20022 connectivity across its treasury platform, easing real-time payment adoption for bank clients.
  • Oracle (September 2024): Released embedded liquidity analytics within Fusion Cloud ERP, strengthening enterprise cash control.
  • SAP (June 2024): Partnered with a major bank to deliver embedded treasury services via banking-as-a-service.
  • Federal Reserve (April 2024): Reported accelerating FedNow participation, expanding the real-time rails underpinning automated cash handling.
  • Nomentia (January 2024): Acquired a complementary payments vendor to broaden its European cash management footprint.
  • ACI Worldwide (October 2023): Launched a real-time cash positioning module aligned with global instant-payment schemes.
  • Bottomline Technologies (May 2023): Introduced fraud-detection enhancements for its cash and payments platform amid rising breach concerns.

Section 12 — Report Scope and Methodology

Parameter Detail
Market Scope Global Cash Management System Market — solutions and services
Study Period 2021–2035
CAGR 7.45% (2026–2035)
Market Size Checkpoints USD 21.85B (2025); USD 23.45B (2026); USD 43.20B (2035)
Fastest Growing Segments SMEs; Cloud deployment; Cash-flow forecasting
Companies Profiled Oracle, FIS, SAP, Fiserv, Kyriba, ACI Worldwide, Nomentia, Bottomline, GTreasury, Coupa
Valuation Currency USD Billion


Section 13 — Detailed Sources and Citations

# Full Citation URL / Source
1 Nomentia, "Treasury Technology Trends 2025," 2025 nomentia.com
2 World Bank, "Global Financial Development Report," 2023 worldbank.org
3 SWIFT, "ISO 20022 Migration Status Update," 2024 swift.com
4 US Federal Reserve, "FedNow Service Adoption Report," 2025 federalreserve.gov
5 Bank for International Settlements, "Fast Payments Tracker," 2024 bis.org
6 Oracle, "Annual Report and Treasury Cloud Brief," 2024 oracle.com
7 Gartner, "Treasury and Cash Management Technology Forecast," 2024 gartner.com
8 OECD, "Sustainable Finance and Corporate Treasury," 2025 oecd.org
9 Bank for International Settlements, "Basel IV Implementation Note," 2024 bis.org
10 J.P. Morgan, "Working Capital Index," 2024 jpmorgan.com
11 European Banking Authority, "Open Banking and PSD2 Review," 2024 eba.europa.eu
12 IBM Security, "Cost of a Data Breach Report," 2024 ibm.com
13 Deloitte, "Global Treasury Survey," 2024 deloitte.com
14 PwC, "Treasury Technology Benchmarking Study," 2024 pwc.com
15 McKinsey & Company, "The Future of Corporate Treasury," 2024 mckinsey.com
16 Reserve Bank of India, "UPI Statistics and Roadmap," 2025 rbi.org.in
17 Banco Central do Brasil, "Pix Adoption Report," 2024 bcb.gov.br
18 FIS, "Annual Report," 2024 fisglobal.com
19 SAP, "Integrated Report," 2024 sap.com
20 Kyriba, "State of Treasury Report," 2025 kyriba.com
21 EY, "Treasury Operations Benchmarking," 2024 ey.com
22 Aite-Novarica, "Cash Management Technology Landscape," 2024 aite-novarica.com


Section 14 — Frequently Asked Questions

Q1. What should buyers prioritize when evaluating vendors in the Cash Management System Market?

Prioritize bank connectivity breadth, native ISO 20022 support, and proven ERP integration. A vendor with shallow bank coverage forces costly workarounds regardless of interface quality.

Q2. How do cloud and on-premise deployments compare for total cost of ownership?

Cloud lowers upfront capital and shortens deployment, but carries recurring subscription costs that compound over time. On-premise demands heavier IT investment yet may suit firms with strict data-residency rules.

Q3. What integration challenges most often delay implementations in the Cash Management System Market?

Legacy ERP connectivity is the top obstacle, followed by inconsistent bank data formats. Projects stall when middleware must bridge old systems to modern APIs, extending timelines and budgets.

Q4. How is AI changing competitive dynamics among vendors?

AI forecasting accuracy has become a primary differentiator. Vendors with mature machine-learning models win deals on liquidity-prediction performance, pressuring slower incumbents to acquire AI capability.

Q5. What regulatory nuance should procurement teams watch in the Cash Management System Market?

Basel IV liquidity rules phase in unevenly across jurisdictions through 2028. Multinationals should confirm a platform handles regional stress-test reporting differences rather than assuming one-size compliance.

Q6. Are emerging-market deployments riskier than mature-market ones?

Emerging markets offer faster growth but face fragmented banking standards and thinner local support. Buyers should weigh real-time scheme maturity, such as UPI or Pix, before committing.

Q7. What new use cases are expanding beyond traditional treasury functions?

Cash-flow data monetization and embedded treasury are emerging fast. Vendors increasingly turn transaction data into credit-scoring and benchmarking products, opening revenue beyond core software licensing.

Cash Management System Market Report Scope

Parameter Detail
Market Scope Global Cash Management System Market — solutions and services
Study Period 2021–2035
CAGR 7.45% (2026–2035)
Market Size Checkpoints USD 21.85B (2025); USD 23.45B (2026); USD 43.20B (2035)
Fastest Growing Segments SMEs; Cloud deployment; Cash-flow forecasting
Companies Profiled Oracle, FIS, SAP, Fiserv, Kyriba, ACI Worldwide, Nomentia, Bottomline, GTreasury, Coupa
Valuation Currency USD Billion

常见问题

买家在评估现金管理系统市场的供应商时应该优先考虑什么?

优先考虑银行连接的广度、本地ISO 20022支持和经过验证的ERP集成。拥有较少银行覆盖的供应商会迫使进行昂贵的变通,无论接口质量如何[13]

云部署和本地部署在总拥有成本方面如何比较?

云降低了前期资本支出并缩短了部署时间,但会产生随时间累积的重复订阅费用。本地部署需要更大的IT投资,但可能适合有严格数据驻留规则的公司[3]

在现金管理系统市场中,最常延迟实施的集成挑战是什么?

遗留ERP连接是最大的障碍,其次是银行数据格式不一致。当中间件必须将旧系统与现代API连接时,项目会停滞,延长时间表和预算[13]

人工智能如何改变供应商之间的竞争动态?

人工智能预测准确性已成为主要的差异化因素。拥有成熟机器学习模型的供应商在流动性预测性能上赢得交易,迫使较慢的现有供应商获取人工智能能力[1]

采购团队在现金管理系统市场中应该关注哪些监管细节?

巴塞尔IV流动性规则将在2028年前在不同司法管辖区不均匀地逐步实施。跨国公司应确认平台能够处理区域压力测试报告的差异,而不是假设一刀切的合规性[9]

新兴市场的部署是否比成熟市场的风险更大?

新兴市场提供更快的增长,但面临分散的银行标准和较薄的本地支持。买家在承诺之前应权衡实时方案的成熟度,例如UPI或Pix[16]

有哪些新的用例正在超越传统的财务职能?

现金流数据货币化和嵌入式财务正在快速兴起。供应商越来越多地将交易数据转化为信用评分和基准产品,开辟了超越核心软件许可的收入[22]

作者
作者
Author Profile
Ankit Gupta LinkedIn Team Lead - Research
Ankit Gupta is a seasoned market intelligence and strategic research professional with over six plus years of experience in the ICT and Semiconductor industries. With academic roots in Telecom, Marketing, and Electronics, he blends technical insight with business strategy. Ankit has led 200+ projects, including work for Fortune 500 clients like Microsoft and Rio Tinto, covering market sizing, tech forecasting, and go-to-market strategies. Known for bridging engineering and enterprise decision-making, his insights support growth, innovation, and investment planning across diverse technology markets.

Research Approach

Research Methodology on Cash Management System Market

1. Introduction:

Market Research Future (MRFR) has initiated an in-depth study of the global cash management system market. The present research document provides a detailed understanding of the cash management system market, with an exhaustive analysis of the market size and market potential for the period of 2023 to 2030 (forecast period). The report aims to offer lucrative insights and attainable growth prospects of the cash management system market. The study further elaborates on the current trends, market opportunities, and driving forces in the cash management system market.

2. Research Objective:

The research objectives for this report on the cash management system market are:

  • To analyze and forecast the market size of the cash management system market globally
  • To offer an in-depth assessment of the market segments
  • To provide a detailed analysis of macro- and micro-economic factors
  • To evaluate the regional market profiles and changes
  • To analyze the changes in demand patterns and pricing structure
  • To offer an extensive analysis of the key players contributing to the market
  • To provide a comprehensive analysis of the major dynamics surrounding the industry

3. Research Methodology:

MRFR’s data-driven approach is used to derive the market size, industry trends, market opportunity, and revenue estimates. For the cash management system market, MRFR has compiled primary and secondary data sources such as industry reports, press releases, annual reports, interviews, and newsletters. The data gathered from primary and secondary sources is further analyzed and processed to obtain qualitative and quantitative insights into the global cash management system market. Primary research is conducted through surveys and interviews with key opinion leaders from the cash management system market. Secondary research involves desk-top research techniques such as literature review.

4. Data Collection:

For the study of the cash management system market, MRFR has conducted a detailed analysis of the market size and market potential for the period of 2023 to 2030 (forecast period). The market sizing procedure involves analyzing historical data of various cash management systems and comparing them with the current market trends. This helps to derive the current market size and deduce future opportunities.

MRFR has adopted a methodical approach to studying the cash management system market. This involves a detailed market understanding of cash management systems - the types, complexities, and industry dynamics. Further, MRFR has conducted extensive primary and secondary research to compile the report. Primary research includes surveys and interviews with key opinion leaders, such as industry experts and business professionals. Secondary research includes sources such as industry reports, press releases, and annual reports.

4. Market Segmentation:

The global cash management system market has been segmented based on type, solution, application, and end user. By type, the market has been segmented into automated teller machines (ATMs), point-of-sale (POS) systems, cash-in-transit (CTI), and others. By solution, the market has been segmented into cash management solutions, cash flow management solutions, currency management solutions, and others. By application, the market has been segmented into banking, retail, healthcare, and others. By end user, the market has been segmented into retail, hospitality, BFSI, and others.

5. Regional Analysis:

The global cash management system market has been studied across five regions, namely, North America, Europe, Asia-Pacific (APAC), Middle East & Africa (MEA), and South America. North America is dominating the global cash management system market. The growth of the cash management system market in North America is due to the presence of leading IT companies, increasing adoption of cash management systems, massive investments in machine learning and artificial intelligence (AI) technology, implementation of cutting-edge technologies, and increasing focus on data analytics.

Europe is the second-largest market for cash management systems, after North America. The steady growth of the European cash management system market can be attributed to the introduction of innovative and advanced cash management systems, increasing government initiatives, and rising investments in research & development (R&D) activities.

Furthermore, the market in APAC is expected to witness growth at the highest CAGR during the forecast period. The growth in the APAC region is due to increasing demand for cash management systems in the banking and retail sectors, implementation of cash management systems by small and medium-sized enterprises (SMEs), and rising investments in digital technologies.

6. Competitive Analysis:

The competitive analysis section of the report provides a detailed analysis of the key players operating in the global cash management system market. The players have been studied based on their product offerings, business strategies, recent developments, and financials. The market potential of all the leading players has been extensively studied in the report and provides an adequate data set for risk analysis. Moreover, the players have been studied based on their respective strengths and weaknesses in the market.

The prominent players in the global cash management system market are BEAMEX AG (Switzerland), Tieto Oyj (Finland), CashGuard Oy (Finland), Diebold Nixdorf (US), RDM Corporation (Canada), Giesecke and Devrient GmbH (Germany), NCR Corporation (US), Sampi Secure Oy (Finland), Wincor Nixdorf (Germany), Nautilus Hyosung Corporation (South Korea), Bally Technologies (US), Diebold (US), Tidel Engineering LP (US), Glory Global Solutions (UK), and CPI Card Group Inc. (US).
下载免费样本

请填写以下表格以获取本报告的免费样本

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.
















