Wind Turbine Nacelle Market Summary
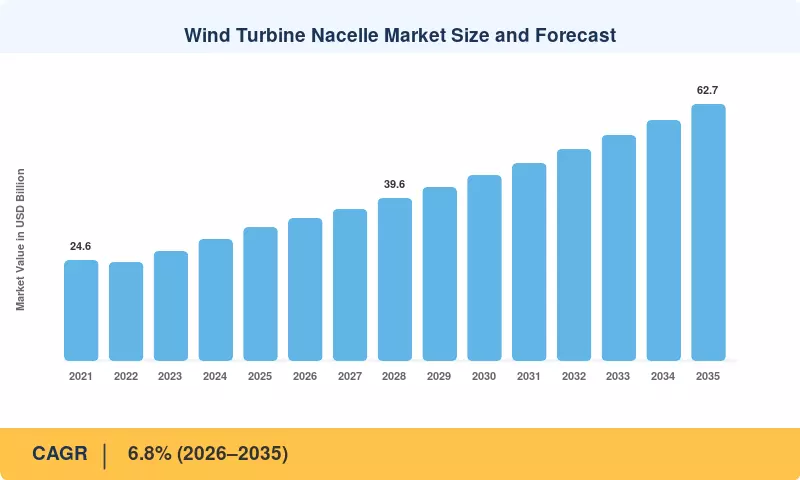
The Wind Turbine Nacelle Market closed 2025 at USD 32.5 billion, and the trajectory from here is shaped less by turbine counts than by the size of each unit shipped. Forecasts place the Wind Turbine Nacelle Market at USD 34.7 billion entering 2026 and USD 62.7 billion by 2035, a 6.8% CAGR across the window. Two catalysts anchor that path: the European Union's Wind Power Package, which committed member states to permitting reform and grid buildout for roughly 500 GW of capacity by 2030 [3], and the US advanced manufacturing production credit under Section 45X, which pays USD 0.02 per watt on qualifying nacelle-side components produced domestically [6].
Drivetrain architecture is where the real substitution is happening. High-speed geared trains — three-stage gearboxes paired with doubly-fed induction generators — dominated the installed base built before 2020, and they are steadily giving way to medium-speed hybrid and permanent-magnet direct-drive designs that cut moving parts and lift availability. Offshore, that shift is nearly complete. The International Energy Agency estimates global wind investment reached about USD 320 billion in 2024 [1], and a rising share of it flows into heavier, higher-rated nacelles rather than more of them.
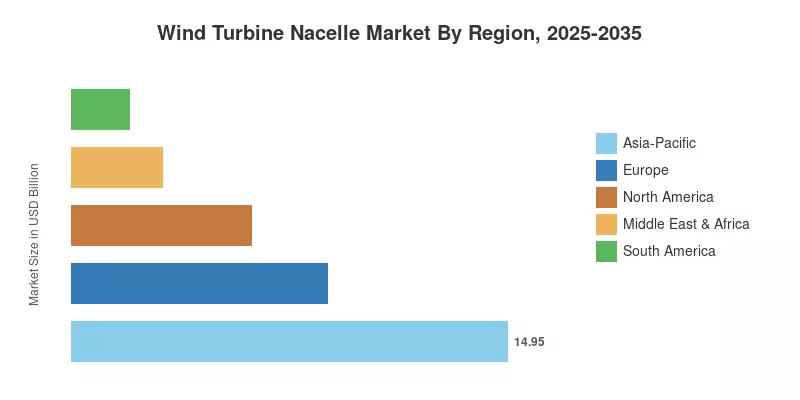
Geography tells a similar story of concentration. Asia-Pacific holds 46% of the Wind Turbine Nacelle Market on the strength of Chinese assembly capacity and India's expanding supplier base. Europe follows at 27%, carried by North Sea offshore pipelines and a repowering wave across Germany and Denmark. Middle East & Africa is the smallest but fastest, compounding at 9.6% as Saudi and Egyptian auctions convert into orders. Through 2035, the winners will be the platforms that scale megawatts per tonne, not merely megawatts.
Key Report Takeaways
• By Technology
- High-speed geared drivetrains still command 41% of Wind Turbine Nacelle Market revenue in 2025, though the share erodes annually as hybrid platforms mature
- Permanent-magnet direct-drive systems generated USD 9.8 billion in 2025, concentrated in offshore and Chinese onshore fleets
- Medium-speed hybrid architectures grow at 8.9% CAGR, the strongest of any drivetrain class
• By Sector
- Onshore installations account for 71% of demand, but the growth premium sits offshore
- Offshore nacelle demand expands at 10.1% CAGR through 2035
- Repowering and retrofit work grows at 9.6% CAGR as pre-2010 European and American fleets reach end of design life
• By Region
- Asia-Pacific led the Wind Turbine Nacelle Market with 46% share in 2025
- Europe generated USD 8.78 billion, second largest globally
- Middle East & Africa posts the fastest regional CAGR at 9.6%
Market Size and Forecast (2021–2035)
Sizing here combines OEM shipment disclosures, customs-level trade data on generators and gear units, project-level capacity awards from national registries, and bottom-up bill-of-materials modelling at platform level. Historical years reconcile against audited segment revenue from listed turbine manufacturers; forecast years apply capacity pipelines discounted for historical auction-to-commissioning slippage.




 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA



