Wind Turbine Nacelle Market Summary
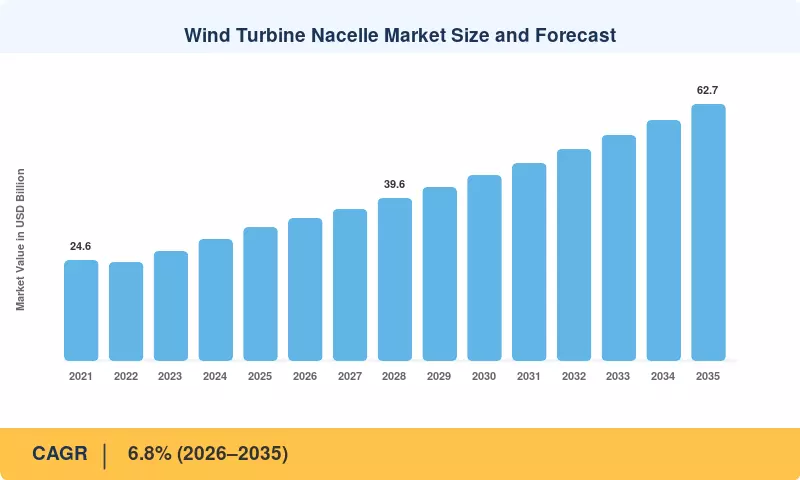
The Wind Turbine Nacelle Market closed 2025 at USD 32.5 billion, and the trajectory from here is shaped less by turbine counts than by the size of each unit shipped. Forecasts place the Wind Turbine Nacelle Market at USD 34.7 billion entering 2026 and USD 62.7 billion by 2035, a 6.8% CAGR across the window. Two catalysts anchor that path: the European Union's Wind Power Package, which committed member states to permitting reform and grid buildout for roughly 500 GW of capacity by 2030 [3], and the US advanced manufacturing production credit under Section 45X, which pays USD 0.02 per watt on qualifying nacelle-side components produced domestically [6].
Drivetrain architecture is where the real substitution is happening. High-speed geared trains — three-stage gearboxes paired with doubly-fed induction generators — dominated the installed base built before 2020, and they are steadily giving way to medium-speed hybrid and permanent-magnet direct-drive designs that cut moving parts and lift availability. Offshore, that shift is nearly complete. The International Energy Agency estimates global wind investment reached about USD 320 billion in 2024 [1], and a rising share of it flows into heavier, higher-rated nacelles rather than more of them.
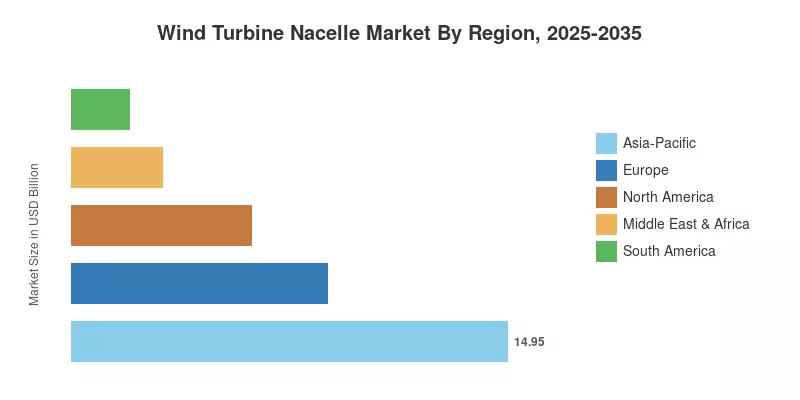
Geography tells a similar story of concentration. Asia-Pacific holds 46% of the Wind Turbine Nacelle Market on the strength of Chinese assembly capacity and India's expanding supplier base. Europe follows at 27%, carried by North Sea offshore pipelines and a repowering wave across Germany and Denmark. Middle East & Africa is the smallest but fastest, compounding at 9.6% as Saudi and Egyptian auctions convert into orders. Through 2035, the winners will be the platforms that scale megawatts per tonne, not merely megawatts.
Key Report Takeaways
• By Technology
- High-speed geared drivetrains still command 41% of Wind Turbine Nacelle Market revenue in 2025, though the share erodes annually as hybrid platforms mature
- Permanent-magnet direct-drive systems generated USD 9.8 billion in 2025, concentrated in offshore and Chinese onshore fleets
- Medium-speed hybrid architectures grow at 8.9% CAGR, the strongest of any drivetrain class
• By Sector
- Onshore installations account for 71% of demand, but the growth premium sits offshore
- Offshore nacelle demand expands at 10.1% CAGR through 2035
- Repowering and retrofit work grows at 9.6% CAGR as pre-2010 European and American fleets reach end of design life
• By Region
- Asia-Pacific led the Wind Turbine Nacelle Market with 46% share in 2025
- Europe generated USD 8.78 billion, second largest globally
- Middle East & Africa posts the fastest regional CAGR at 9.6%
Market Size and Forecast (2021–2035)
Sizing here combines OEM shipment disclosures, customs-level trade data on generators and gear units, project-level capacity awards from national registries, and bottom-up bill-of-materials modelling at platform level. Historical years reconcile against audited segment revenue from listed turbine manufacturers; forecast years apply capacity pipelines discounted for historical auction-to-commissioning slippage.
Driver Impact Analysis
| Driver |
~% Impact on CAGR |
Geographic Relevance |
Impact Timeline |
Ref |
| Offshore buildout and turbine upscaling |
~1.4 pp |
Europe, APAC |
Long-term (≥4 yr) |
[1][5]
|
| Repowering of aging onshore fleets |
~1.1 pp |
North America, Europe |
Medium-term (2–4 yr) |
[8] |
| Local-content rules and manufacturing credits |
~0.9 pp |
North America, India, EU |
Medium-term (2–4 yr) |
[6][11]
|
| Permanent-magnet drivetrain adoption |
~0.8 pp |
Asia-Pacific |
Long-term (≥4 yr) |
[14] |
| Auction-driven volume and falling LCOE |
~0.7 pp |
Global |
Short-term (≤2 yr) |
[2] |
| Rising service and monitoring attach rates |
~0.6 pp |
Global |
Short-term (≤2 yr) |
[21] |
| Green hydrogen and corporate PPA demand |
~0.5 pp |
Europe, MEA |
Long-term (≥4 yr) |
[4] |
Offshore Scale Economics
Every megawatt added to a platform rating raises nacelle content faster than it raises unit count, which is why the Wind Turbine Nacelle Market grows even in years when global turbine shipments are flat. A 15 MW offshore nacelle weighs roughly 500 tonnes against about 70 tonnes for a 3 MW onshore unit — a mass ratio that flows almost directly into bill-of-materials value. The Global Wind Energy Council projects offshore additions climbing past 25 GW annually by 2030 [2], with the North Sea and the Taiwan Strait absorbing the bulk.
Repowering as a Second Demand Cycle
Roughly 60 GW of European onshore capacity was commissioned before 2010 and now sits at or past its 20-year design assumption [3]. Full repowering replaces the nacelle outright while reusing foundations, roads and grid connections, which compresses payback to a fraction of a greenfield build. Germany's EEG amendments explicitly shortened repowering approvals, and WindEurope has tracked a measurable rise in repowered capacity since 2023 [3].
Manufacturing Incentives Reshaping Supply
As regional mandates transform sourcing, local-content regulations and manufacturing credits are driving a structural shift in supply chains, providing about 0.9 percentage points of growth value [6][11]. Turbine manufacturers are forced to localize manufacturing over a medium-term horizon of two to four years due to industrial policies in North America, India, and the European Union that explicitly link subsidies to domestic footprints [6][11]. Domestic investment is a crucial prerequisite for future growth since suppliers who do not create local manufacturing hubs run the danger of being excluded from important regional markets [6][11].
Restraints Impact Analysis
Restraint impacts are directional drags on the growth rate, modelled independently against a no-friction baseline. They are not additive, and their combined effect is already embedded in the published forecast for the Wind Turbine Nacelle Market rather than layered on top of it.
| Restraint |
~% Impact on CAGR |
Geographic Relevance |
Impact Timeline |
Ref |
| Rare-earth price volatility and supply concentration |
~-0.9 pp |
Global |
Medium-term (2–4 yr) |
[19] |
| OEM margin compression and serial-defect costs |
~-0.8 pp |
Europe, North America |
Short-term (≤2 yr) |
[12] |
| Grid interconnection and permitting backlogs |
~-0.7 pp |
North America, Europe |
Medium-term (2–4 yr) |
[7] |
| Heavy-lift vessel and crane availability |
~-0.5 pp |
Global offshore |
Long-term (≥4 yr) |
[16] |
| Tariffs, trade friction and freight cost |
~-0.4 pp |
Global |
Short-term (≤2 yr) |
[9] |
The Magnet Problem
Permanent-magnet generators need neodymium-iron-boron, and China refines the overwhelming majority of global rare-earth output [19]. Price swings of the magnitude seen since 2021 move generator cost by double-digit percentages within a single procurement cycle, which pushes some buyers back toward electrically excited or geared alternatives despite the efficiency penalty. Substitution research at Fraunhofer IWES continues, but nothing at commercial scale displaces NdFeB before the late 2020s [17].
Quality Costs and Warranty Exposure
Serial defects are the industry's most expensive failure mode because they replicate across a fleet. Siemens Energy disclosed multi-billion-euro provisions after quality issues surfaced in its onshore platforms in 2023 [12], a reminder that a single design flaw in a bearing or blade-root interface can erase years of margin. Buyers have responded by demanding tighter defect clauses, which raises the cost of capital for every supplier.
Wind Turbine Nacelle Market Opportunities
Modular Nacelle Architectures
Splitting the nacelle into transportable modules that assemble on site removes the road and bridge limits that cap unit mass in landlocked geographies. Suppliers who certify sectional designs open interior India, western China, and the Andean corridor without new highway infrastructure.
Materials Substitution
Credible nacelle weight reduction composite improvements are achieved by applying structural resin and hybrid castings to coverings, bedplate sub-frames, and canopies. These gains translate into smaller towers and less expensive foundations. In tenders where the Wind Turbine Nacelle Market is otherwise priced on commodity terms, vendors who can provide verified mass savings have an advantage.
Emerging-Market Localization
Saudi Arabia, Egypt, Morocco and Vietnam all pair auction programmes with domestic-content ambitions but lack tier-one assembly. Joint ventures that place final assembly locally while importing gearboxes and generators capture policy preference at modest capital exposure.
Data-Enabled Service Models
Availability-guaranteed contracts that are based on results rather than labor hours are supported by nacelle-resident sensors on gearboxes, main bearings, and converters. This allows OEMs to defend themselves against independent servicers and turns a one-time hardware sale into recurring revenue.
Offshore Durability Engineering
Salt aerosol, condensation, and cathodic effects drive failure rates well above onshore norms, making offshore nacelle corrosion protection a genuine differentiator in North Sea and East Asian tenders. Suppliers with documented coating and enclosure qualification win specification battles before price is discussed.
Wind Turbine Nacelle Market Future Outlook
Condition Monitoring Becomes Standard Equipment
Sensor-instrumented drivetrains with model-based fault detection shift maintenance from calendar-based to condition-based, and NREL work suggests operations and maintenance can represent a quarter or more of onshore lifetime cost [8]. As that spend concentrates on nacelle internals, buyers will treat diagnostics as a specification line rather than an upsell.
Platform Consolidation
Fewer platforms, longer production runs. OEMs burned by the 2022–2023 margin cycle have publicly narrowed portfolios, and the resulting standardization lowers unit cost while raising the stakes of any single design defect. Expect the Wind Turbine Nacelle Market to reward suppliers who resist bespoke variants.
Electrification and Hydrogen Coupling
IRENA's transition scenarios call for wind capacity several multiples of today's installed base by mid-century [5], with a growing slice dedicated to electrolysis rather than grid export. Dedicated hydrogen-linked wind farms change duty cycles and, with them, drivetrain specification priorities.
Circularity Requirements
Reports on recyclability are moving from voluntary disclosure to procurement requirements. The Wind Turbine Nacelle Market will require auditable recovery pathways for rare-earth elements long before 2035, and European tenders are progressively requesting material passports including magnets, copper, and structural steel [22].
Regional Market Share Analysis
| Region |
Metric (2025) |
Primary Investment Themes |
| Asia-Pacific |
46% share |
Offshore scale-up, PM drivetrain export capacity |
| Europe |
USD 8.78 Billion |
Repowering, North Sea offshore, resilience criteria |
| North America |
19% share |
45X-linked plant buildout, interconnection reform |
| South America |
6.1% CAGR |
Auction pipelines, hydrogen-linked demand |
| Middle East & Africa |
9.6% CAGR |
Sovereign renewable targets, localization mandates |
| Total |
USD 32.5 Billion |
— |
Regional structure in the Wind Turbine Nacelle Market reflects where assembly capacity sits, not merely where turbines spin. China exports nacelles; most other regions import them.
North America
| Country |
Metric |
Key Driver |
| United States |
82% of region |
Section 45X manufacturing credit [6]
|
| Canada |
6.4% CAGR |
Provincial procurement in Alberta and Quebec |
| Mexico |
USD 0.31 Billion |
Industrial self-supply and PPA renewals |
Interconnection queues remain the binding constraint. FERC Order 2023 restructured queue processing toward cluster studies with financial commitments, which should shorten the multi-year waits that stranded projects across MISO and SPP [7]. Nacelle demand tracks that unblocking with a lag of roughly eighteen months.
Europe
| Country |
Metric |
Key Driver |
| Germany |
24% of region |
EEG repowering approvals [3]
|
| United Kingdom |
7.9% CAGR |
Contracts for Difference offshore rounds |
| Netherlands |
USD 0.72 Billion |
IJmuiden Ver and Nederwiek tenders |
| Denmark |
9% of region |
Test-site prototype and export assembly base |
| Rest of Europe |
8.1% CAGR |
Iberian repowering, Polish Baltic pipeline |
Auction design changed the buying calculus here. Non-price criteria under the Net-Zero Industry Act let procurers weight supply-chain resilience, cybersecurity and responsible sourcing alongside strike price [11], which favours European assembly over lowest-bid imports. That policy tilt matters more to nacelle suppliers than to any other part of the turbine.
Asia-Pacific
| Country |
Metric |
Key Driver |
| China |
68% of region |
Provincial offshore allocations and export volume [2]
|
| India |
8.7% CAGR |
Approved-model list and hybrid tenders [11]
|
| Japan |
USD 0.54 Billion |
Round 3 offshore awards |
| South Korea |
9.1% CAGR |
Floating pipeline off Ulsan |
| Australia |
4% of region |
Capacity Investment Scheme underwriting |
| Rest of Asia-Pacific |
7.4% CAGR |
Vietnam and Taiwan localization |
Chinese OEMs now ship platforms above 16 MW and have compressed nacelle cost per megawatt to levels European competitors struggle to match [2]. Whether that pricing travels depends on trade policy, and the Wind Turbine Nacelle Market outside China is increasingly segmented by which suppliers are eligible rather than which are cheapest.
South America
| Country |
Metric |
Key Driver |
| Brazil |
71% of region |
Northeast wind corridor and BNDES financing |
| Chile |
8.2% CAGR |
Green hydrogen export projects [4]
|
| Argentina |
USD 0.11 Billion |
RenovAr contract restarts |
| Rest of South America |
6.9% CAGR |
Colombian and Uruguayan tenders |
Curtailment is the region's quiet risk. Brazilian transmission constraints in the Northeast forced significant output restrictions during 2024, and developers now weigh grid access ahead of resource quality when siting.
Middle East & Africa
| Country |
Metric |
Key Driver |
| Saudi Arabia |
11.2% CAGR |
National Renewable Energy Program rounds |
| South Africa |
26% of region |
REIPPPP bid windows |
| Egypt |
10.4% CAGR |
Gulf of Suez corridor and hydrogen MoUs |
| Morocco |
USD 0.14 Billion |
Domestic-content industrial policy |
| Rest of MEA |
8.8% CAGR |
Kenyan and Omani pipelines |
Sovereign programmes anchor demand here, which makes volumes lumpy but bankable. The World Bank's ESMAP offshore wind roadmaps have accelerated feasibility work across the region [4], though assembly capacity remains almost entirely absent.
Wind Turbine Nacelle Market Segmentation
Segmentation across the Wind Turbine Nacelle Market follows the drivetrain first, because that choice determines component mix, weight, and service economics downstream.
By Drivetrain Technology
| Segment |
Metric (2025) |
Primary Demand Driver |
| High-Speed Geared |
41% share |
Installed onshore base and low capital cost |
| Medium-Speed Geared (Hybrid) |
8.9% CAGR |
Weight-to-rating optimization at 5–8 MW |
| Direct Drive PMSG |
USD 9.8 Billion |
Offshore availability requirements |
| Direct Drive EESG |
6% share |
Rare-earth-independent supply strategy |
High-speed geared trains persist because they are cheap to build and well understood by service networks, and in the Wind Turbine Nacelle Market that installed-base gravity slows any transition. Medium-speed hybrids are the pragmatic middle: a single- or two-stage gearbox with a permanent-magnet generator, delivering much of the direct-drive availability benefit at meaningfully lower mass and magnet content. That combination is winning specification battles in the 5–8 MW onshore class across Europe and India.
By Component
| Segment |
Metric (2025) |
Primary Demand Driver |
| Gearbox |
21% share |
Torque density at higher ratings |
| Generator |
USD 6.2 Billion |
Magnet-based efficiency gains |
| Main Shaft & Bearings |
7.1% CAGR |
Forging capacity constraints |
| Power Converter & Electrical |
15% share |
Grid-code compliance and fault ride-through |
| Yaw & Pitch Systems |
USD 3.1 Billion |
Load-mitigation control strategies |
| Cover, Bedplate & Auxiliary |
8.4% CAGR |
Mass reduction and thermal management |
Gearboxes and generators together carry about 40% of nacelle value, and both sit behind narrow supplier bases. Large-diameter main bearings are the sharper bottleneck — a handful of forgers worldwide can produce them at the sizes 15 MW-plus platforms require, and lead times stretch past a year.
By Capacity Rating
| Segment |
Metric (2025) |
Primary Demand Driver |
| Below 3 MW |
9% share |
Distributed and constrained-site projects |
| 3–6 MW |
USD 14.6 Billion |
Mainstream onshore repowering class |
| 6–10 MW |
8.8% CAGR |
Early offshore fleets and large onshore |
| Above 10 MW |
12.6% CAGR |
Next-generation offshore platforms |
The 3–6 MW class is the volume engine of the Wind Turbine Nacelle Market and will stay so through the forecast, because it fits existing logistics, crane fleets, and grid connections. Above 10 MW grows fastest from a small base, and its economics depend entirely on whether installation vessel supply keeps pace with unit mass.
By Installation
| Segment |
Metric (2025) |
Primary Demand Driver |
| Onshore |
71% share |
Repowering and land-based auctions |
| Offshore |
10.1% CAGR |
Fixed-bottom and floating pipelines |
Onshore wind dominates with a 71% market share, propelled by steady repowering initiatives and land-based auctions, while offshore installations expand at a 10.1% CAGR driven by advancing fixed-bottom and floating pipelines.
By End Use
| Segment |
Metric (2025) |
Primary Demand Driver |
| New Installations (OEM Supply) |
74% share |
Greenfield capacity additions |
| Repowering & Retrofit |
9.6% CAGR |
End-of-life fleet replacement |
| Aftermarket Replacement & Overhaul |
USD 2.6 Billion |
Gearbox and generator exchange cycles |
New OEM supply installations anchor the market with a dominant 74% share driven by ongoing greenfield capacity additions, while repowering and retrofit services expand at a 9.6% CAGR to address aging, end-of-life fleet replacements. Meanwhile, aftermarket replacement and overhaul activities form a robust USD 2.6 billion sector fueled by critical gearbox and generator exchange cycles.
Competitive Benchmarking
Concentration is high but not monopolistic. Top-five suppliers account for an estimated 52–58% of the Wind Turbine Nacelle Market, and a revenue-based HHI in the 850–1,000 range places the sector at the boundary between moderately concentrated and competitive. The structure is regionally bifurcated: Chinese OEMs dominate domestic volume while Western OEMs hold most of the North Sea and North American installed base, with component specialists supplying across both blocs.
| Company |
Est. Revenue Share Range |
Key Offerings |
Strategic Positioning |
| Vestas Wind Systems |
~13–16% |
EnVentus and offshore platforms |
Broadest global service footprint |
| Goldwind |
~11–14% |
Medium-speed and direct-drive PM platforms |
Cost leadership, export expansion |
| Siemens Gamesa (Siemens Energy) |
~9–12% |
Direct-drive onshore and offshore units |
Offshore technology depth, quality remediation |
| Envision Energy |
~7–10% |
Smart onshore platforms |
Software-led operations positioning |
| Mingyang Smart Energy |
~6–9% |
Large offshore and floating platforms |
Rating leadership at the top end |
| GE Vernova |
~5–8% |
Workhorse onshore and Haliade platforms |
Selective market focus, margin discipline |
| Nordex Group |
~4–6% |
Delta4000 series |
European onshore specialization |
| ZF Wind Power |
~3–5% |
Gearboxes and hybrid drivetrains |
Tier-one drivetrain independence |
| Winergy (Flender) |
~3–5% |
Gear units, generators, couplings |
Multi-OEM component supply |
| Sany Renewable Energy |
~2–4% |
Onshore platforms and assembly |
Domestic scale, emerging-market entry |
Recent News & Developments
- Siemens Energy (June 2023): Disclosed substantial quality provisions tied to onshore turbine components, triggering an industry-wide tightening of design validation protocols [12].
- European Commission (October 2023): Launched the Wind Power Package, pairing permitting acceleration with grid investment commitments and pre-qualification reform [3].
- Mingyang Smart Energy (January 2024): Unveiled an offshore platform in the 18–20 MW class, resetting expectations for nacelle mass and bearing requirements [2].
- GE Vernova (April 2024): Completed separation into a standalone energy company, sharpening capital allocation toward selective wind markets [13].
- European Union (June 2024): Net-Zero Industry Act entered into force, embedding resilience and sustainability criteria into renewable auctions [11].
- US Treasury and IRS (October 2024): Finalized Section 45X rules clarifying credit eligibility for nacelle-side components and spurring domestic plant commitments [6].
- Vestas (March 2025): Expanded serial production of its largest offshore nacelle platform following prototype validation at the Danish national test centre [15].
- Saudi Power Procurement Company (July 2025): Awarded further utility-scale wind capacity under the National Renewable Energy Program, with localization conditions attached [4].



 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA


