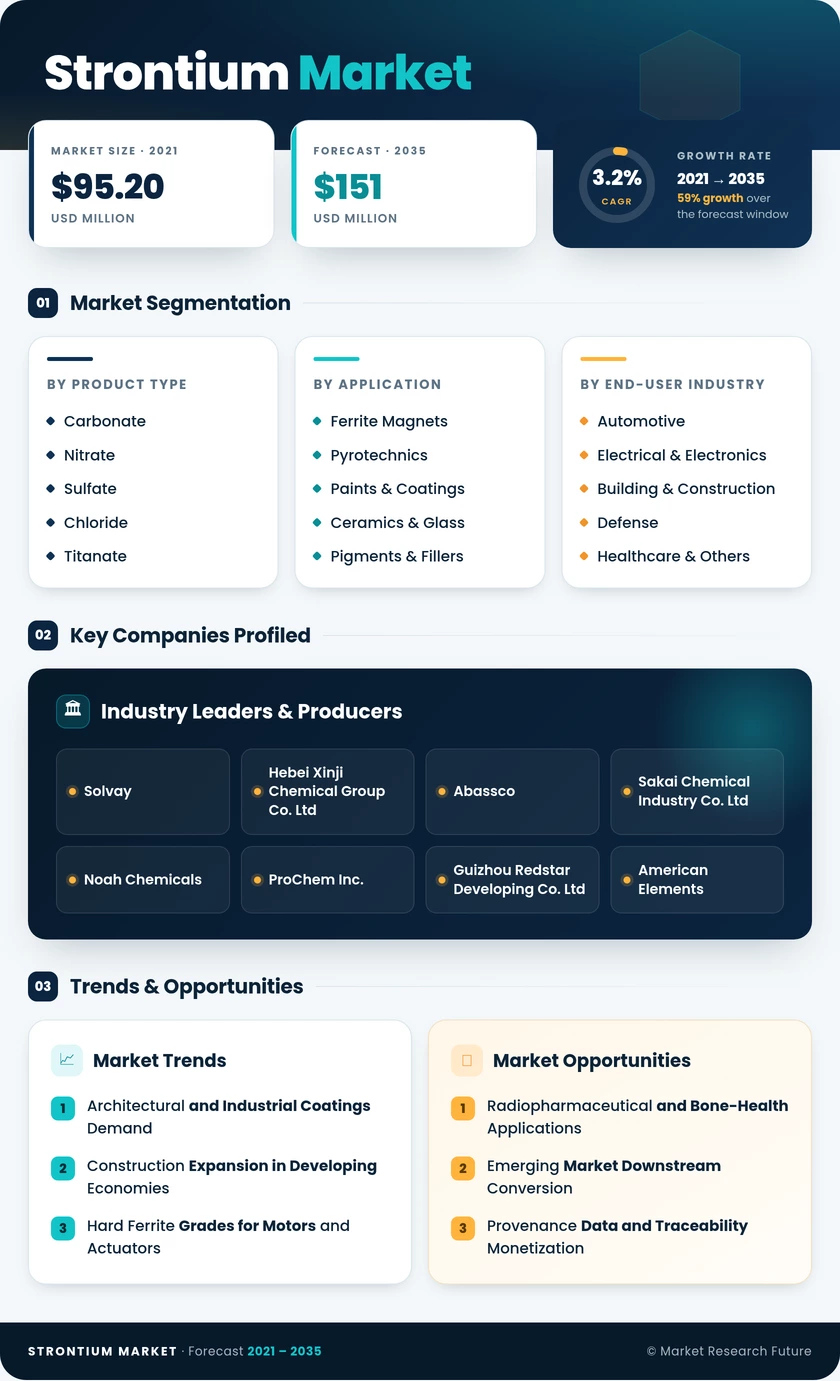
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
| By Product Type | Carbonate; Nitrate; Sulfate; Chloride; Titanate; Other Product Types | Carbonate | Titanate |
| By Application | Ferrite Magnets; Pyrotechnics; Paints & Coatings; Ceramics & Glass; Pigments & Fillers; Other Applications | Ferrite Magnets | Paints & Coatings |
| By End-User Industry | Automotive; Electrical & Electronics; Building & Construction; Defense; Healthcare & Others | Automotive | Building & Construction |
| By Region | North America; Europe; Asia-Pacific; South America; Middle East & Africa | Asia-Pacific | Asia-Pacific |
Market Segmentation Overview
By Product Type
| Sub-Segment | Key Trend |
| Carbonate | Bulk demand tied to magnet powder output; consolidation of small Chinese converters raising average plant scale |
| Nitrate | Procurement-driven demand from defense and marine signalling; oxidizer logistics costs increasingly priced separately |
| Sulfate | Steady growth from drilling fluids and inhibitor chemistries replacing chromate systems |
| Chloride | Small but stable volumes in dental and pharmaceutical formulations requiring documented purity |
| Titanate | Highest growth rate; purity thresholds above 99.99% restrict qualified supply and support premium pricing |
| Other Product Types | Metallurgical deoxidizers and research reagents; fragmented, low-volume demand |
Product-type economics divide sharply between bulk and specialty. Carbonate competes on landed cost and is the segment most exposed to Chinese capacity decisions, while titanate, chloride, and isotope grades compete on qualification credentials and documentation quality. Producers increasingly manage these as separate businesses with different sales models.
By Application
| Sub-Segment | Key Trend |
| Ferrite Magnets | Motor count growth per vehicle sustains demand even as powertrains electrify |
| Pyrotechnics | Defense budget growth and SOLAS carriage rules maintain a stable replacement cycle |
| Paints & Coatings | Chromate restriction driving reformulation and raising strontium intensity per litre |
| Ceramics & Glass | Lead-free glaze transition lifting loadings in tile, sanitaryware, and tableware |
| Pigments & Fillers | Weatherability and opacity requirements in exterior architectural systems |
| Other Applications | Metallurgy, drilling fluids, and medical uses; niche but rising in value contribution |
Application demand is being reshaped by regulation more than by technology. Restrictions on hexavalent chromium and lead are the two most consequential policy levers, and both increase strontium intensity in the formulations that replace legacy chemistries. Magnet demand remains the volume anchor.
By End-User Industry
| Sub-Segment | Key Trend |
| Automotive | Auxiliary motor counts and protective coating specifications hold demand steady through powertrain transition |
| Electrical & Electronics | Capacitor, speaker, and substrate demand pulling toward higher-purity grades |
| Building & Construction | Fastest-growing end user, driven by Asian and Middle Eastern building pipelines |
| Defense | Least price-elastic segment; procurement calendars govern order timing |
| Healthcare & Others | Radiopharmaceutical and bone-graft applications delivering outsized value per unit volume |
End-user mix determines margin structure. Automotive and construction supply the tonnage that keeps kilns loaded, while defense and healthcare supply the pricing power. Suppliers balancing both profiles have proven more resilient through energy price shocks than those concentrated in bulk industrial channels.

 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA