Hot Dip Galvanized Iron Wire Market Summary
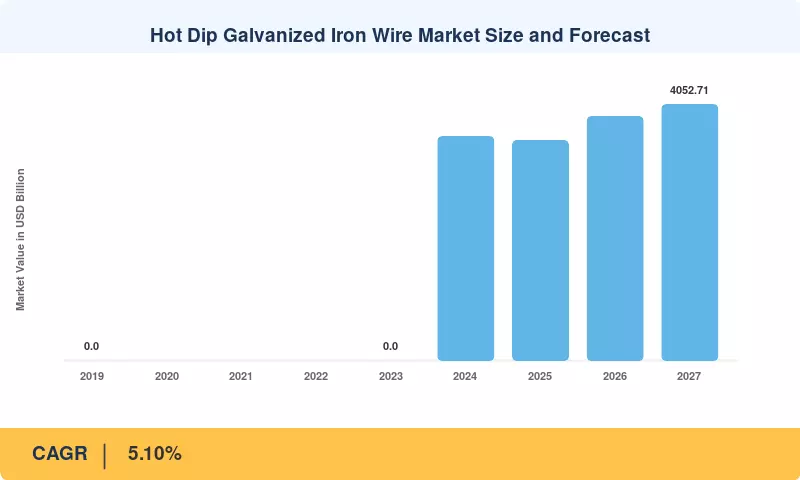
The global hot-dip galvanized iron wire (below 0.25% carbon) market was valued at 3,483.760 Billion in 2025, is expected to open the forecast period at 3,869.55 Billion in 2026, and is projected to reach 6,030.130 Billion by 2035, expanding at a compound annual growth rate of 5.10% over the 2026–2035 window[3]. Low-carbon galvanized wire is a volume commodity whose demand curve tracks fixed-capital formation almost one-for-one, and the three structural forces carrying the forecast are sustained global infrastructure investment and construction activity, renewable energy expansion and power grid modernization, and agricultural mechanization and food security infrastructure [2][4][6]. The apparent dip between the 2024 historical value of 3,543.47 and the 2025 base-year value of 3,483.76 reflects a destocking and price-normalization cycle in wire rod and zinc rather than a contraction in physical consumption; the model returns to a 4.7%–5.8% annual expansion band from 2026 onward as deferred infrastructure packages, grid capital expenditure and rural fencing programmes convert into orders[5].
The technology transition inside this market is a migration of value from commodity light-coating product toward heavy-coating and alloy-coated systems specified for multi-decade service life. Heavy-coating grades — those meeting the upper mass classes of ASTM A641 and the Class A/B thresholds of EN 10244-2 and ISO 1461 — command the larger share of revenue because coating mass is the dominant cost and performance variable in a below-0.25%-carbon wire, while fine wire below 1 mm and the industrial wire products application carry the strongest incremental growth as downstream fabricators substitute galvanized feedstock into mesh, cable armouring and fastener production [7][8][9]. Commercial evidence of this repositioning is visible in the portfolio moves of the leading producers: N.V. Bekaert S.A. divested its Steel Wire Solutions businesses in Costa Rica, Ecuador and Venezuela to Grupo AG in January 2025 at an enterprise value of approximately US$73 million in order to concentrate capital on higher-margin segments, while Tata Steel Limited consolidated full ownership of TSN Wires through its Siam Industrial Wire subsidiary in August 2025 to streamline its South-East Asian wire operations [11][12].
Regionally, North America hot-dip galvanized iron wire (below 0.25% carbon) market is the dominant region by 2025 revenue on the strength of infrastructure reauthorization spending, transmission rebuild programmes and a protected domestic wire market, while APAC is the fastest growing region, driven by grid buildout, rural infrastructure and the concentration of global wire drawing and galvanizing capacity in China, India and South-East Asia[4][15]. Europe ranks as the third major demand pool but faces the sharpest cost headwind from carbon border and decarbonization compliance, with Latin America and the Middle East & Africa contributing smaller but faster-normalizing volumes tied to agriculture, mining and utility rollout [10][13]. The forward view through 2035 is one of steady mid-single-digit volume-led growth in which competitive advantage shifts from tonnage to coating chemistry, energy intensity per tonne and proximity to protected end markets.
Key Report Takeaways
| Segment Dimension | Key Metric | Notes |
| Total Market | 3,483.760 (2025) → 6,030.130 (2035) | Headline sizing from the report details file; 5.10% CAGR across 2026–2035 |
| Total Market | 5.10% CAGR (2026–2035) | Forecast opens at 3,869.55 in 2026 after a base-year normalization |
| By Coating Type | Heavy Coating — dominant by 2025 revenue | Segment-level values not disclosed in the pre-extracted dataset; ranking is MRFR analyst assessment based on coating-mass pricing |
| By Coating Type | Light Coating — high-volume, lower-value tier | Serves binding wire and short-service-life fencing where coating mass is minimized |
| By Wire Diameter | Medium Wire (1–4 mm) — dominant diameter class | Core diameter band for fencing, gabion and general industrial mesh |
| By Wire Diameter | Fine Wire (Below 1 mm) — fastest growing diameter class | Driven by cable armouring, fine mesh and precision industrial fabrication |
| By Wire Diameter | Thick or Heavy Wire (Above 4 mm) — structural niche | Erosion control, marine gabion and heavy binding applications |
| By Application | Fencing — dominant application by 2025 revenue | Agricultural, highway and perimeter security demand across all five regions |
| By Application | Industrial Wire Products — fastest growing application | Substitution of galvanized feedstock into downstream fabricated products |
| By Application | Gabion and Erosion Control | Tied to flood defence, slope stabilization and transport corridor works |
| By Application | Cable Armouring | Correlates directly with grid modernization and submarine/underground cable spend |
| Regional | North America — dominant region (2025) | Infrastructure reauthorization plus trade-protected domestic wire pricing |
| Regional | APAC — fastest growing region | Grid buildout, rural infrastructure and concentration of galvanizing capacity |
| Competitive | Top-6 disclosed share ≈ 24.5% | N.V. Bekaert S.A. leads at 7.2%; residual "Others" at 75.5% |
MARKET SIZE AND FORECAST (2019–2035)
MRFR sizes this hot-dip galvanized iron wire (below 0.25% carbon) market bottom-up from galvanized wire production and apparent consumption, cross-checked against zinc coating consumption, wire rod conversion volumes and reported segment revenue of the profiled producers. The model treats 2025 as the base year, applies plant-level capacity and utilization assumptions to derive historical volumes, and forecasts forward using an infrastructure-investment elasticity model calibrated to construction, transmission and agricultural capital expenditure. All forecast values are held in constant-currency terms and reconciled to the terminal 2035 value and the 5.10% CAGR window.



 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA


