Strontium Market Summary
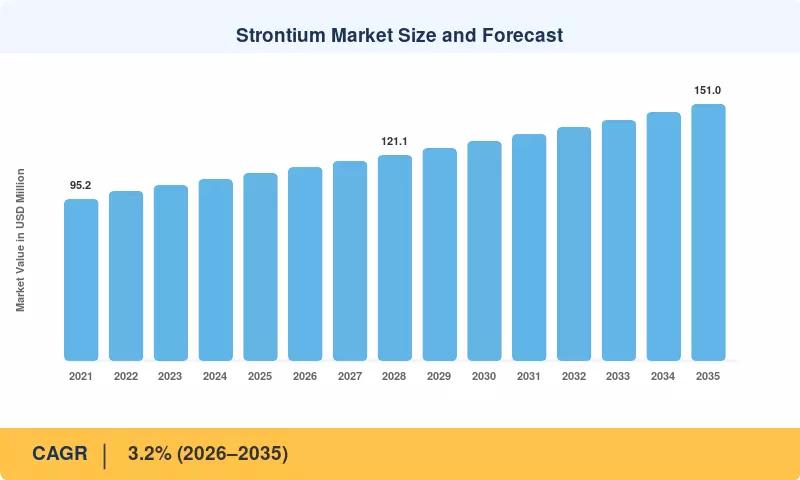
The Strontium Market reached USD 110.2 Million in 2025, opens the forecast window at USD 113.7 Million in 2026, and is projected to close at USD 151.0 Million by 2035, expanding at a 3.2% CAGR across 2026–2035. Two catalysts anchor that trajectory. First, the European Commission's Critical Raw Materials Act, which entered into force in May 2024, set benchmarks requiring 10% of annual EU consumption of listed strategic inputs to come from domestic extraction by 2030, pulling celestite processing and refining back into scope for European buyers [1]. Second, India's National Infrastructure Pipeline, carrying more than USD 1.4 trillion in committed project value, is lifting demand for architectural coatings and glass formulations where strontium additives improve weatherability and opacity .
Processing technology is shifting underneath this demand. Legacy black-ash roasting of celestite — coal-fired rotary kilns producing strontium sulfide intermediates — is steadily being displaced by direct carbonation and hydrometallurgical conversion routes that cut kiln fuel intensity and eliminate hydrogen sulfide off-gas handling. The United States Department of Energy's Industrial Demonstrations Program allocated up to USD 6.3 billion in 2024 for decarbonizing energy-intensive process industries, and chemical processors converting mineral feedstocks are named eligible applicants [3]. Sakai Chemical and Hebei Xinji have both moved portions of capacity toward closed-loop carbonation lines that recover sodium sulfate as a saleable co-product, raising yield per tonne of ore and lowering per-unit water draw. That conversion is capital-heavy, which is why the Strontium Market rewards incumbents with existing kiln footprints rather than new entrants.
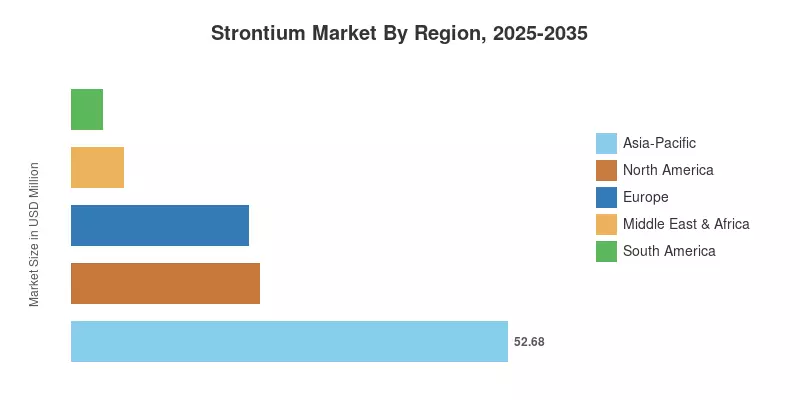
Regionally, Asia-Pacific holds 47.8% of global value on the strength of Chinese ferrite production and Indian construction chemicals demand, and it is simultaneously the fastest-growing region at a 3.9% CAGR through 2035. North America follows at USD 22.7 Million in 2025, supported by defense signalling stockpiles and a small but high-margin nuclear medicine stream. Europe ranks third with 19.4% of value, where regulatory pressure on chromate pigments is reshaping which strontium grades buyers specify. The Strontium Market over the next decade will be decided less by tonnage growth than by which producers can certify provenance, purity, and process emissions to industrial customers.
Key Report Takeaways
• By Product
- Carbonate grades account for 58.4% of global value in 2025, sustained by hard ferrite powder demand from motor and speaker manufacturing
- Nitrate grades contributed USD 16.9 Million in 2025, concentrated in defense signalling, marine distress devices, and specialty oxidizer blends
- Titanate grades posted the strongest product-level growth at a 3.7% CAGR, tied to dielectric and substrate applications in electronics
• By Applications
- Automotive end users represent 28.9% of Strontium Market value, driven by permanent-magnet motor counts per vehicle rather than by vehicle volume alone
- Electrical and electronics buyers absorbed USD 24.6 Million in 2025, the second-largest end-user pool
- Building and construction demand compounds at a 4.0% CAGR, the fastest end-user trajectory in the Strontium Market
• By Region
- Asia-Pacific commands 47.8% of global value and retains dominance across the entire forecast window
- Asia-Pacific also grows fastest at a 3.9% CAGR, led by China, India, and ASEAN consumption
- Middle East & Africa contributed USD 6.3 Million in 2025, the smallest regional pool but a rising host for downstream conversion capacity
Market Size and Forecast (2021–2035)
Values in this section were built bottom-up from celestite ore production statistics published by the United States Geological Survey, cross-checked against customs-level trade flows for HS 2836.92 and 2834.29, and reconciled top-down using reported segment revenues from listed and privately held converters [5]. Historical years were anchored to physical volumes and weighted average contract prices; forecast years apply demand elasticity coefficients derived from automotive motor production, architectural coatings output, and defense procurement budgets. All figures are expressed in USD Million at constant 2025 prices.



 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA


