Online Particle Size Market (2026 - 2035)

Online Particle Size Market Research Report Information By Measurement Technique (Sieving, Laser Diffraction, Image Analysis, and Others), By System Type (Lab-Based Systems and Industrial Online Systems), By End-User Industry (Mining, Pharmaceutical, Cement Industry, Food Processing, Chemical Industry, and Others), and By Region (North America, Europe, Asia-Pacific, South America, and Middle East & Africa) – Forecast Till 2035
ID: MRFR/CnM/66601-CR 111 Pages Chitranshi Jaiswal Last Updated: September 15, 2026
Online Particle Size Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)6.01%
2025 Market SizeUSD 165.31 Billion
2035 Market SizeUSD 293.69 Billion
Key Players
Malvern Panalytical Ltd
HORIBA Ltd
Anton Paar GmbH
Shimadzu Corporation
Micromeritics Instrument Corporation
TSI Incorporated
Opportunities
  • Integration Of AI And Machine Learning In Particle Size Analysis
  • Emerging Markets With Growing Industrialization
  • Development Of Customized Solutions For Specific Applications

Online Particle Size Market Summary

The Global Online Particle Size Market was valued at USD 165.31 Billion in 2025, the base year of this study, and is projected to reach USD 293.69 Billion by 2035, expanding at a CAGR of 6.01% over 2026–2035. The forecast window opens at USD 173,737.57 Million in 2026 and crosses the USD 200 Billion threshold in 2029 implying that roughly USD 128.4 Billion of incremental annual revenue is created across the ten-year horizon. Growth is structurally underwritten by three forces identified in the primary research base: the rising demand for nanotechnology applications, which pushes measurement requirements below the resolution limits of legacy sieving hardware; an intensified focus on quality control in manufacturing, which converts particle characterisation from a laboratory QC gate into a continuous, in-line process parameter; and the growth of the pharmaceutical and biotechnology sectors, the single largest end-user vertical at USD 45,173.01 Million in 2025 (27.33% of global revenue). Notably, growth is not linear: annual expansion decelerates modestly through 2027 (4.94% YoY) before re-accelerating to a 6.38–6.49% band from 2031 onward, a profile consistent with a capital-equipment replacement cycle that front-loads installed-base saturation and back-loads industrial online conversion [1][3][7].

The defining structural transition in this market is the migration from laboratory-based batch measurement to industrial, continuously operating online systems. In 2025, Lab-Based Systems remain dominant at USD 89,803.12 Million (54.32% share), but they grow at only 3.87% CAGR — barely above global GDP-type expansion. Industrial Online Systems, at USD 75,508.30 Million (45.68%), compound at 8.09% CAGR, more than twice the lab-based rate, and on the extracted trajectory overtake lab-based revenue during the early 2030s. The same transition is visible by measurement technique: Sieving, historically the workhorse of cement, mining and bulk-solids QC, holds USD 31,269.96 Million (18.92%) but grows at just 1.93% CAGR — effectively a stranded technology in real terms — while Laser Diffraction dominates at USD 68,998.84 Million (41.74%) with 7.06% CAGR and Image Analysis is the fastest-growing technique at 7.52% CAGR from a USD 24,753.55 Million base. Commercial evidence corroborates this: Malvern Panalytical's Mastersizer 3000+ (April 2024) embedded AI-enabled features to raise measurement accuracy and automation, and HORIBA's May 2025 pharmaceutical portfolio launch explicitly bundled particle characterisation with spectroscopy and process monitoring for real-time analysis in production environments, not merely in the QC lab [2][4][15][16].

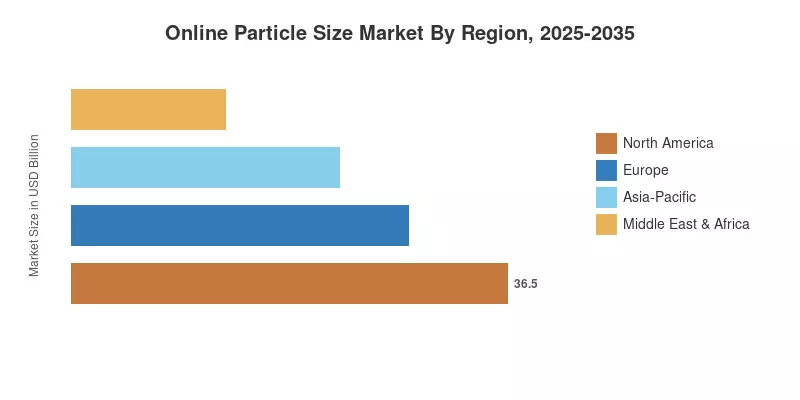
Regionally, the market is unusually evenly balanced across the two mature blocs. Europe holds USD 48,229.44 Million (29.17%) in 2025, marginally ahead of North America at USD 47,621.27 Million (28.81%), with Asia-Pacific third at USD 40,669.12 Million (24.60%) but posting the highest forecast CAGR in the sizing model at 6.82%. South America (USD 14,937.08 Million, 5.07% CAGR) and the Middle East & Africa (USD 13,854.51 Million, 6.15% CAGR) together account for 17.42% of 2025 revenue and represent the market's greenfield opportunity. Over the forecast horizon, the centre of gravity shifts eastward and downstream: Asia-Pacific's superior CAGR, combined with the 8.09% growth of industrial online systems concentrated in cement, mining and chemicals capacity additions, means the incremental revenue pool of the 2030s will look materially different in geography and product mix from the installed base of 2025.

Key Report Takeaways

Segment Dimension Key Metric Notes
Global Market USD 165,311.42 Mn (2025) → USD 293,690.45 Mn (2035) 6.01% CAGR, 2026–2035; 1.78× expansion over the decade
Measurement Technique — Dominant Laser Diffraction: USD 68,998.84 Mn (41.74% share, 2025) Default technique for wet and dry online deployment; 7.06% CAGR
Measurement Technique — Fastest Image Analysis: 7.52% CAGR (2026–2035) Smallest major technique (USD 24,753.55 Mn) but highest growth; shape/morphology data drives adoption
Measurement Technique — Laggard Sieving: 1.93% CAGR from USD 31,269.96 Mn Sub-inflation growth; structural displacement by optical methods
System Type — Dominant Lab-Based Systems: USD 89,803.12 Mn (54.32% share, 2025) Majority share today, but only 3.87% CAGR
System Type — Fastest Industrial Online Systems: 8.09% CAGR from USD 75,508.30 Mn Highest CAGR of any segment in the study; crossover with lab-based expected early 2030s
End-User — Dominant Pharmaceutical: USD 45,173.01 Mn (27.33% share, 2025) Also the fastest-growing vertical at 6.57% CAGR
End-User — Second Largest Chemical Industry: USD 31,421.75 Mn (19.01% share); 6.22% CAGR Continuous-process fit favours online conversion
End-User — Slowest Cement Industry: 5.32% CAGR from USD 20,825.33 Mn Mature installed base; growth tied to clinker capacity and grinding efficiency programmes
Region — Largest (model) Europe: USD 48,229.44 Mn (29.17% share, 2025) Marginally ahead of North America in the sizing model
Region — Fastest (model) Asia-Pacific: 6.82% CAGR from USD 40,669.12 Mn Highest regional CAGR in the extracted dataset
Competitive Concentration Top-5 share ≈ 63.4%; estimated HHI ≈ 1,030 Moderately concentrated; leader Malvern Panalytical at 18.5%


MARKET SIZE AND FORECAST (2019–2035)

MRFR sizes the Online Particle Size Market using a bottom-up market engineering approach. Installed-base and shipment data for laser diffraction, image analysis, sieving and adjacent instrumentation are triangulated against end-user capital expenditure patterns across mining, pharmaceutical, cement, food processing and chemical production. Revenue is built at the segment level (measurement technique × system type × end-user industry) for each of the five regional blocs, then reconciled top-down against vendor-reported instrumentation revenue and validated through primary interviews with instrumentation OEMs, contract manufacturers and process-analytics integrators. Base-year 2025 values are anchored to reported and disclosed revenue; forecast years apply segment-specific CAGRs adjusted for capital-cycle timing, regulatory triggers (notably process analytical technology adoption in regulated pharmaceutical manufacturing) and capacity-addition schedules in heavy industry [1][5][6][9].

Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Increased Focus On Quality Control In Manufacturing 26% Global; strongest in Europe (USD 48,229.44 Mn) and North America (USD 47,621.27 Mn) Short to Medium term
Rising Demand For Nanotechnology Applications 24% North America, Europe, Japan/South Korea within Asia-Pacific Medium to Long term
Growth Of The Pharmaceutical And Biotechnology Sectors 22% Global; anchors the USD 45,173.01 Mn pharmaceutical segment Short to Medium term
Advancements In Online Measurement Technologies 18% Global; enables the 8.09% CAGR of Industrial Online Systems Medium term
Expansion Of End-User Industries Such As Food And Beverage 10% Asia-Pacific (6.82% CAGR), South America, Middle East & Africa Medium to Long term
Total 100% — —


Increased Focus On Quality Control In Manufacturing

Quality control is the largest single contributor to forecast growth because it changes where particle measurement happens, not merely how much of it is purchased. Under a conventional QC regime, particle size is a release test — a batch is manufactured, sampled, carried to a laboratory instrument, and accepted or rejected after the fact. This model supports the USD 89,803.12 Million lab-based installed base but caps its growth at 3.87% CAGR, because instrument counts scale with the number of QC laboratories rather than with production volume. Under a process-control regime, particle size becomes a controlled variable measured continuously on the line, and instrument counts scale with the number of production streams. That is the mechanism behind the 8.09% CAGR of Industrial Online Systems and the reason the segment adds share every year of the forecast despite starting from a minority position at 45.68% of 2025 revenue.

The economics favour conversion in continuous-process industries first. The Chemical Industry (USD 31,421.75 Million, 6.22% CAGR) and Cement Industry (USD 20,825.33 Million, 5.32% CAGR) operate grinding and reaction circuits where a particle size excursion translates directly into energy waste or off-specification product; here, an online analyser pays back through yield and specific-energy consumption rather than through labour savings. In batch industries the payback is regulatory and documentary. The persistence of a 5.32% CAGR in cement — below the global 6.01% — indicates that in the most mature online applications, growth is now a function of clinker and grinding capacity additions rather than of penetration gains, which are already substantially realised [1][9][13].

Rising Demand For Nanotechnology Applications

Nanotechnology exerts its influence on the market through resolution, not volume. As formulations and engineered materials move into the sub-micron and nanometre range — nanomedicine carriers, battery electrode slurries, catalyst supports, advanced ceramics, printed electronics inks — the measurable range of sieving (practically limited to coarse fractions) becomes irrelevant, and even conventional laser diffraction reaches its lower boundary. This is the clearest explanation for the 1.93% CAGR of Sieving, the slowest-growing segment in the entire study: it is not losing to a cheaper substitute but to an application space it physically cannot address. Sieving's USD 31,269.96 Million base grows to only a modestly larger figure over ten years, meaning its 18.92% 2025 share contracts materially in relative terms.

The corresponding beneficiaries are optical and light-scattering techniques with sub-micron capability, and increasingly hybrid platforms that combine size with shape, count and concentration. Malvern Panalytical's acquisition of Creoptix in January 2026 is directly aligned with this: the transaction added biomolecular interaction analysis and high-sensitivity detection to a portfolio historically anchored in particle characterisation, creating multi-technique workflows for pharmaceuticals, biotechnology and advanced materials research. The strategic read-through is that the nanotechnology driver is pulling the market from single-parameter size instruments toward integrated characterisation suites, which raises average selling prices and supports the revenue growth of Image Analysis at 7.52% CAGR [8][11][15].

Growth Of The Pharmaceutical And Biotechnology Sectors

Pharmaceutical manufacturing is simultaneously the largest and the fastest-growing end-user vertical, at USD 45,173.01 Million and 6.57% CAGR respectively — the only major vertical that is both. Particle size in solid oral dosage forms governs dissolution rate and therefore bioavailability; in inhaled therapies it governs deposition site; in injectables and biologics it governs aggregation risk and immunogenicity. These are not quality preferences but efficacy and safety parameters, which places particle characterisation inside the regulatory filing itself rather than in discretionary process improvement. That regulatory embedding is what makes the pharmaceutical segment's demand comparatively insensitive to capital-cycle timing, and it explains why the vertical outgrows the global average by 56 basis points.

The commercial evidence is explicit. HORIBA's May 2025 expansion introduced integrated solutions spanning the full pharmaceutical workflow from drug discovery through to manufacturing, combining particle characterisation, spectroscopy and process monitoring specifically to support quality control, regulatory compliance and real-time analysis in both laboratory and production settings. A vendor building a discovery-to-manufacturing continuum is responding to a customer that increasingly wants one validated measurement chain across development and commercial supply — a procurement pattern that favours large-portfolio incumbents and partly explains the top-five concentration of 63.4% documented in Section 10 [5][6][16].

Advancements In Online Measurement Technologies

The 8.09% CAGR of Industrial Online Systems is only achievable because the technical barriers to continuous measurement have fallen. Historically, moving an analyser from a temperature-controlled laboratory to a plant environment meant confronting vibration, dust loading, temperature swings, representative sampling of a flowing stream, and the need for measurement without operator intervention. Advances in robust optics, automated sample presentation, self-cleaning windows, and — critically — the algorithmic handling of noisy in-process signals have made the online measurement reliable enough to close a control loop rather than merely generate a trend chart.

Artificial intelligence is now the leading edge of this driver. Malvern Panalytical's Mastersizer 3000+ (April 2024) incorporated AI-enabled features expressly to improve measurement accuracy and automation, which the development record characterises as evidence of a broader shift toward intelligent, digitalised particle characterisation. The commercial significance is that automation removes the skilled-operator dependency that, per Section 5.1, is one of the market's principal restraints. Every increment of on-instrument intelligence widens the addressable customer base beyond organisations that can employ a dedicated particle scientist — a mechanism that transfers value from the restraint column to the driver column over the forecast period [2][15][17].

Expansion Of End-User Industries Such As Food And Beverage

Food Processing represents USD 24,565.51 Million (14.86% share) growing at 6.18% CAGR, above the global average. Particle size determines mouthfeel in chocolate and dairy, dispersibility in powdered beverages and infant formula, extraction efficiency in coffee, and dosing uniformity in fortified products — attributes that are commercially decisive in branded consumer goods. Unlike heavy industry, food processing is driven less by energy economics than by sensory consistency and by food-safety regimes that increasingly require documented process control rather than end-product testing alone.

The geographic logic of this driver points away from the mature blocs. Food and beverage manufacturing capacity is expanding fastest in Asia-Pacific (6.82% regional CAGR), South America (USD 14,937.08 Million base) and the Middle East & Africa (6.15% CAGR), where rising incomes are shifting consumption toward processed and packaged formats and where new plants are specified with modern instrumentation from commissioning rather than retrofitted. This is the driver most responsible for the emerging-market share gains embedded in the 2030s portion of the forecast [12][13][14].

Restraints Impact Analysis

Restraint ~% Drag on CAGR Geographic Relevance Impact Timeline
High Initial Investment Costs 30% Strongest in South America (5.07% CAGR) and Middle East & Africa Short to Medium term
Technical Complexity And Expertise Requirements 28% Global; acute in emerging markets and among SMEs Short to Medium term
Limited Awareness Among Small And Medium Enterprises (SMEs) 18% Asia-Pacific, South America, Middle East & Africa Medium term
Integration Challenges With Existing Systems 15% Mature markets with legacy installed base (Europe, North America) Short term
Regulatory Hurdles In Various Regions 9% Fragmented; pharmaceutical and food verticals most exposed Medium to Long term
Total 100% — —


High Initial Investment Costs

Online particle size systems are capital purchases with installation, qualification and integration costs that frequently exceed the instrument price itself. The resulting hurdle rate is visible directly in the regional data: South America Online Particle Size Market grows at 5.07% CAGR — the slowest of the five blocs and 94 basis points below the global rate — despite hosting substantial mining and food-processing activity that is technically well suited to online measurement. Where capital is expensive or allocated to capacity rather than to instrumentation, plants defer analyser projects and continue with manual sampling, which caps conversion regardless of the technical case.

Technical Complexity And Expertise Requirements

Particle size measurement is deceptively difficult: results depend on dispersion protocol, optical model selection, refractive index assumptions and sampling representativeness, and two instruments can legitimately disagree if these are set differently. This creates an expertise dependency that is scarce outside large pharmaceutical, chemical and mining organisations, and it is a principal reason Lab-Based Systems retain 54.32% of 2025 revenue — a centralised laboratory concentrates the necessary skill in one place. The restraint is eroding rather than fixed, since AI-enabled automation of the type introduced in the Mastersizer 3000+ transfers method expertise into the instrument, but the erosion is gradual and does not materially change the forecast before the early 2030s.

Limited Awareness Among Small And Medium Enterprises (SMEs)

The addressable base of the market extends far beyond the large enterprises that dominate current revenue, but SME processors in food, specialty chemicals and building materials frequently do not know that continuous particle measurement is available at their scale, or assume it is reserved for large-capital plants. This awareness gap suppresses demand precisely in the geographies with the highest structural growth — Asia-Pacific, South America and the Middle East & Africa collectively represent USD 69,460.71 Million, or 42.02% of 2025 revenue, against a substantially larger share of global manufacturing establishments. Closing this gap is more a distribution and channel-education problem than a technology problem.

Integration Challenges With Existing Systems

An online analyser delivers value only when its output reaches a control system, a historian and a quality record. In brownfield plants, this means interfacing modern instruments with distributed control systems, manufacturing execution systems and validated data infrastructure of varying vintage — work that is unglamorous, project-specific and often the critical path of the installation. This restraint bites hardest in the mature blocs with the deepest legacy installed base, and it is a credible contributor to the modest 3.87% CAGR of Lab-Based Systems and to the 5.54% CAGR of North America, both below the global average.

Regulatory Hurdles In Various Regions

Regulatory divergence adds cost without adding capability. A method validated for one jurisdiction may require revalidation for another; pharmacopoeial and standards regimes differ in accepted techniques and reporting conventions; and in regulated manufacturing, changing an established measurement method carries filing consequences that create genuine switching inertia. This is the smallest of the five restraints at 9% assigned drag, because in the pharmaceutical vertical regulation is on balance a net driver — but it is real friction for multinationals operating a single global quality system, and it slows the replacement of validated legacy methods such as sieving even where superior techniques exist.

Online Particle Size Market Opportunities

Integration Of AI And Machine Learning In Particle Size Analysis

This is the highest-value opportunity in the study because it addresses the market's two largest restraints simultaneously. Machine learning applied to particle characterisation can automate optical-model selection, flag non-representative samples, detect dispersion failures, and convert raw distributions into predictive process actions — collapsing the expertise requirement (28% assigned drag) and shortening the integration effort (15% assigned drag). The commercial precedent already exists in the Mastersizer 3000+ launched in April 2024 with AI-enabled accuracy and automation features. If AI-enabled automation removes even a fraction of the expertise barrier, the primary beneficiary is Industrial Online Systems, already the fastest segment at 8.09% CAGR from a USD 75,508.30 Million base — the segment whose entire economic case rests on unattended operation. Realisation timeline: near-term, with material revenue effect from 2027–2030 as AI-enabled platforms move from flagship to mid-range product tiers.

Emerging Markets With Growing Industrialization

Asia-Pacific, South America and the Middle East & Africa Online Particle Size Market together represent USD 69,460.71 Million in 2025 (42.02% of the global market), with Asia-Pacific Online Particle Size Market carrying the highest regional CAGR in the model at 6.82% and MEA at 6.15%. The opportunity is qualitatively different from mature-market demand: greenfield plants specify instrumentation at design stage, so vendors compete for a full-line specification rather than for a single replacement unit, and there is no legacy integration burden of the kind described in Section 5.4. Capturing this requires local service coverage and application support rather than product innovation, which favours vendors willing to invest ahead of revenue. On the extracted CAGRs, Asia-Pacific alone adds materially more incremental revenue over the forecast decade than South America and MEA combined, making it the single most consequential geographic allocation decision for the sector.

Development Of Customized Solutions For Specific Applications

The end-user data shows six verticals with materially different growth profiles — Pharmaceutical 6.57%, Chemical 6.22%, Food Processing 6.18%, Mining 5.38%, Cement 5.32%, Others 5.59% — which is strong evidence that this is not one market but a portfolio of application markets sharing a measurement physics. A cement grinding circuit, an inhaled-drug formulation line and a chocolate conche impose entirely different requirements on sampling, environmental hardening, sanitary design and data reporting. Vendors who productise vertical-specific configurations — pre-validated methods, compliant materials of construction, application-tuned software — convert a commodity instrument sale into a specified solution with defensible margin. HORIBA's May 2025 pharmaceutical workflow suite is precisely this move executed in the largest vertical, and the same logic is available in food processing (USD 24,565.51 Million) and chemicals (USD 31,421.75 Million).

Collaborative Research And Development Initiatives

Because measurement credibility depends on method consensus, collaboration between instrument vendors, standards bodies, academic groups and end users has unusual commercial leverage in this market: a technique that becomes the reference method in a pharmacopoeial monograph or an industry standard acquires a durable installed-base advantage. Collaborative R&D also de-risks the transition away from sieving, whose 1.93% CAGR reflects entrenchment in existing specifications as much as technical merit — displacing it requires equivalence data that no single vendor can credibly generate alone. Malvern Panalytical's Creoptix acquisition points to a related pathway: assembling multi-technique capability enables joint development with pharmaceutical and advanced-materials partners on workflows that no single-technique vendor can support. Realisation timeline is long — standards cycles run in years — but the resulting positions are among the most defensible in the sector.

Online Particle Size Market Future Outlook

Technology Evolution: From Size Distribution To Process Intelligence

The forecast period will complete the Online Particle Size Market transition from an instrument market to a process-intelligence market. The measurement-technique data shows the direction unambiguously: Sieving at 1.93% CAGR is in structural decline in real terms; Laser Diffraction at 7.06% remains the volume workhorse; Image Analysis at 7.52% is the growth leader. Image analysis grows fastest not because it measures size better but because it measures more — shape, aspect ratio, agglomeration state, count — parameters that predict downstream behaviour (flowability, dissolution, compaction, sinterability) more reliably than a size distribution alone. By the mid-2030s the competitive question will be less "which technique" than "which combination," a shift already visible in Malvern Panalytical's multi-technique consolidation via the Creoptix acquisition. The corollary is that instrument revenue becomes increasingly bundled with software and method libraries, raising deal sizes and lengthening customer relationships.

Competitive Dynamics And Market Structure Evolution

With an estimated HHI of approximately 1,030 and a top-five share of 63.4%, the market enters the forecast period moderately concentrated with a substantial competitive fringe (Other players at 9.0%). Two forces will act on this structure in opposite directions. Consolidation pressure comes from the portfolio logic described above: as customers buy validated multi-technique workflows rather than single instruments, subscale single-technique vendors lose specification battles, and the January 2026 Creoptix transaction is a template for how leaders will close capability gaps. Fragmentation pressure comes from Asia-Pacific's 6.82% growth, which creates a large price-sensitive greenfield segment that regional and emerging vendors can serve on cost. The likely resolution is a barbell: a consolidated premium tier competing on integrated workflows in regulated and high-value applications, and a competitive volume tier in cost-driven heavy industry. Bettersize Instruments (5.8%) and Brookhaven Instruments (4.3%) sit at the strategic pinch point between these tiers.

Digital, Regulatory And Sustainability-Driven Shifts

Three non-technical forces will shape demand through 2035. Digitally, the value of an online analyser increasingly lies in the data it contributes to a plant-wide model rather than in the individual measurement, which raises the importance of open interfaces and historian integration — and makes the integration restraint (Section 5.4) a competitive differentiator rather than merely a cost. Regulatorily, continued momentum behind real-time release and continuous manufacturing in pharmaceuticals converts particle measurement from documentation into a control-strategy element, directly supporting the 6.57% CAGR of the pharmaceutical vertical. On sustainability, comminution is among the most energy-intensive operations in mining and cement; tightening industrial decarbonisation requirements make grind-size optimisation a compliance-relevant lever, which is the most credible route to lifting the cement segment's 5.32% CAGR above its current trajectory in the later forecast years.

Long-Range Demand Scenario To 2035

The base case carries the market to by 2035 at 6.01% CAGR, with growth accelerating from a 4.94% trough in 2027 to a 6.38–6.49% band from 2031. The most consequential swing factor is the pace of the lab-to-online crossover. On the extracted CAGRs — Lab-Based at 3.87% and Industrial Online at 8.09% — online systems overtake lab-based revenue during the early 2030s; an upside scenario in which AI-enabled automation removes the expertise barrier faster would pull that crossover forward and lift the terminal value, since the growing segment would compound over a larger base for longer. The downside scenario is a capital-expenditure contraction in heavy industry concentrated in 2027–2029, the period where the model already shows its weakest YoY growth; because online conversion in mining, cement and chemicals is capex-financed rather than opex-financed, a downturn defers rather than destroys demand, and the shape of the recovery in the 2030s would be steeper but the cumulative decade total lower.

Regional Market Share Analysis

Region 2025 Market (USD Mn) Share (2025) CAGR (2026–2035) Primary Investment Themes
Europe 48,229.44 29.17% 5.98% Pharmaceutical process analytics; specialty chemicals; sustainability-driven grinding efficiency
North America 47,621.27 28.81% 5.54% Regulated pharma manufacturing; advanced materials; brownfield lab-to-line conversion
Asia-Pacific 40,669.12 24.60% 6.82% Greenfield capacity in chemicals, cement and food; electronics and battery materials
South America 14,937.08 9.04% 5.07% Mining and mineral processing; food and beverage expansion
Middle East & Africa 13,854.51 8.38% 6.15% Petrochemical downstream integration; cement capacity; industrial diversification
Total 165,311.42 100.00% 6.01% —


Data reconciliation note: The report metadata register designates North America as the dominant region and Europe as the fastest growing region. The extracted sizing model instead shows Europe marginally largest in 2025 (USD 48,229.44 Mn vs USD 47,621.27 Mn — a gap of USD 608.17 Mn, or 0.37% of the global market) and Asia-Pacific with the highest forecast CAGR at 6.82%, with Europe second among the large blocs at 5.98%. Both statements are reported here. Where regional conclusions are drawn in this deliverable, the sizing model values are used, since they reconcile exactly to the global total. The metadata designation of North America as dominant is defensible on an installed-base and vendor-revenue-recognition view rather than on 2025 end-market value, and the two regions should be treated as effectively co-leading.

Europe

Country Key Metric Key Driver
Germany Largest national market in the region (national split not disaggregated in the extracted dataset) Chemical and pharmaceutical manufacturing density; process-instrumentation engineering base
United Kingdom Major regional market Pharmaceutical R&D and formulation development; advanced materials research
France Major regional market Pharmaceutical manufacturing; cement and specialty chemicals
Italy Significant regional market Food processing; building materials
Rest of Europe Balance of regional total (USD 48,229.44 Mn) Nordic minerals processing; Benelux chemicals cluster; Central European manufacturing


Europe's Online Particle Size Market USD 48,229.44 Million and 5.98% CAGR reflect a mature, high-specification market where growth comes from method upgrading rather than first-time adoption. Three factors sustain above-North-American growth: the concentration of pharmaceutical and specialty chemical manufacturing subject to stringent quality regimes; the region's position as the home base of several leading vendors (Malvern Panalytical, Anton Paar, Microtrac Retsch, Sympatec), which shortens sales and service cycles; and energy-cost and decarbonisation pressure in cement and minerals grinding, where particle size control is a direct lever on specific energy consumption. That last theme is under-appreciated commercially: in a region where industrial energy prices are structurally elevated, an online analyser that trims grinding energy has a payback calculated in months rather than years [1][9][18].

North America

Country Key Metric Key Driver
United States Dominant national market in the region (national split not disaggregated in the extracted dataset) Regulated pharmaceutical manufacturing; advanced materials and semiconductors; large installed lab base
Canada Secondary regional market Mining and mineral processing; oil sands and chemicals
Mexico Growth market within the bloc Contract manufacturing; food processing; cement


North America's Online Particle Size Market USD 47,621.27 Million places it within 0.4% of Europe in 2025, but its 5.54% CAGR is the second-slowest of the five blocs — a profile characteristic of a market with the deepest legacy installed base. The region's large stock of laboratory instruments is an asset for vendor service revenue but a drag on new-unit growth, and the integration burden of connecting modern analysers to established validated data systems (Section 5.4) is felt most acutely here. The offsetting strength is regulatory: process analytical technology and quality-by-design expectations in pharmaceutical manufacturing continue to convert particle measurement from a release test into an in-process control, which supports the region's outsized share of the USD 45,173.01 Million pharmaceutical vertical [5][6][10].

Asia-Pacific

Country Key Metric Key Driver
China Largest national market in the region (national split not disaggregated in the extracted dataset) Chemical, cement and battery-materials capacity; domestic vendor emergence
Japan Major regional market Advanced materials; instrumentation manufacturing base (HORIBA, Shimadzu)
India Fastest-growing national market in the bloc Generic pharmaceutical manufacturing; cement capacity additions; food processing
South Korea Significant regional market Electronics, display and battery materials
Rest of Asia-Pacific Balance of regional total (USD 40,669.12 Mn) Southeast Asian food, chemicals and minerals processing


Asia-Pacific's Online Particle Size Market 6.82% CAGR is the highest in the study, 81 basis points above the global rate, and it is the only bloc where greenfield specification rather than replacement dominates the demand mix. This matters for product mix as much as for geography: plants specified today are far more likely to include Industrial Online Systems at design stage than to add them later, which links the region's growth directly to the fastest-growing system-type segment. The region also hosts two of the ten profiled vendors (HORIBA at 14.2% global share and Shimadzu at 10.5%), giving it a domestic supply base with local service economics that mature-market vendors must match. The principal execution risk is price competition: greenfield buyers in cost-sensitive verticals such as cement and bulk chemicals are more willing to accept a lower-specification instrument, which compresses regional ASPs even as unit volumes grow [11][12][14].

South America

Country Key Metric Key Driver
Brazil Largest national market in the region (national split not disaggregated in the extracted dataset) Iron ore and mineral processing; food and beverage manufacturing
Argentina Secondary regional market Agricultural processing; chemicals
Chile Significant regional market Copper and lithium mining; mineral concentration circuits
Rest of South America Balance of regional total (USD 14,937.08 Mn) Andean mining; regional food processing


South America Online Particle Size Market is the market's clearest example of demand suppressed by capital constraint rather than by absence of application. At USD 14,937.08 Million and 5.07% CAGR, it is both the smallest and the slowest-growing bloc, yet it hosts world-scale copper, iron ore and lithium processing — exactly the grinding-and-classification circuits where online particle measurement produces the largest energy and recovery gains. The gap between technical fit and adoption rate is attributable to the high initial investment restraint (30% assigned drag), amplified by currency volatility that raises the local-currency cost of imported instrumentation and by financing conditions that favour capacity over instrumentation. Vendors who solve the financing problem — leasing, analyser-as-a-service, or performance-linked contracting — would be addressing the binding constraint directly [12][13].

Middle East and Africa

Country Key Metric Key Driver
Saudi Arabia Leading national market in the region (national split not disaggregated in the extracted dataset) Petrochemical downstream integration; industrial diversification programmes
United Arab Emirates Major regional market Chemicals, cement, and food-processing capacity
South Africa Significant regional market Mining and mineral beneficiation
Rest of MEA Balance of regional total (USD 13,854.51 Mn) North African cement; sub-Saharan minerals and food processing


MEA Online Particle Size Market is the smallest bloc at USD 13,854.51 Million (8.38% share) but posts 6.15% CAGR — above the global average and second only to Asia-Pacific, which makes it the most under-weighted opportunity relative to its growth rate. The driver is state-sponsored industrial diversification: petrochemical downstream integration in the Gulf and large cement and minerals investments across North and Southern Africa create new plants that specify instrumentation at build. As with Asia-Pacific, the greenfield character of demand favours online systems over lab retrofits. The constraint is service density — a region with dispersed plants and limited local application-support depth raises the total cost of ownership of complex instruments, which is precisely where the AI-enabled automation opportunity (Section 6.1) has the greatest marginal value [13][14].

Online Particle Size Market By Region, 2025-2035

Online Particle Size Market Segmentation

Dimension Sub-Segments Dominant Segment (2025) Fastest Growing Segment (2026–2035)
By Measurement Technique Sieving; Laser Diffraction; Image Analysis; Others Laser Diffraction — USD 68,998.84 Mn (41.74%) Image Analysis — 7.52% CAGR
By System Type Lab-Based Systems; Industrial Online Systems Lab-Based Systems — USD 89,803.12 Mn (54.32%) Industrial Online Systems — 8.09% CAGR
By End-User Industry Mining; Pharmaceutical; Cement Industry; Food Processing; Chemical Industry; Others Pharmaceutical — USD 45,173.01 Mn (27.33%) Pharmaceutical — 6.57% CAGR
By Region North America; Europe; Asia-Pacific; South America; Middle East & Africa Europe — USD 48,229.44 Mn (29.17%) Asia-Pacific — 6.82% CAGR


By Measurement Technique

Segment 2025 Value (USD Mn) Share (2025) CAGR (2026–2035) Primary Demand Driver
Laser Diffraction 68,998.84 41.74% 7.06% Broad dynamic range; established online deployment for wet and dry streams
Others 40,289.07 24.37% 5.75% Dynamic light scattering, sedimentation, acoustic and ultrasonic methods for specialised ranges
Sieving 31,269.96 18.92% 1.93% Entrenched specifications in bulk solids, aggregates and cement
Image Analysis 24,753.55 14.97% 7.52% Shape and morphology data alongside size; agglomeration detection
Total 165,311.42 100.00% 6.01% —


The technique mix is the clearest expression of the market's structural story. Laser diffraction's 41.74% share and 7.06% CAGR make it the only segment that is simultaneously large and fast — it is the default choice for new online installations because its dynamic range covers most industrial applications and its physics tolerate flowing samples. Image analysis grows fastest at 7.52% but from the smallest base, and its trajectory is driven by applications where size alone is insufficient: needle-shaped crystals in pharmaceutical crystallisation, fibre-containing food powders, agglomerate detection in battery slurries. Sieving's 1.93% CAGR is the most commercially significant number in this table — it implies a segment that shrinks meaningfully as a share of the market and signals where an installed base is available for competitive displacement, constrained mainly by the specification inertia described in Section 5.5.

By System Type

Segment 2025 Value (USD Mn) Share (2025) CAGR (2026–2035) Primary Demand Driver
Lab-Based Systems 89,803.12 54.32% 3.87% Method development, batch release testing, R&D and centralised QC


Industrial Online Systems 75,508.30 45.68% 8.09% Continuous process control, real-time release, energy and yield optimisation
Total 165,311.42 100.00% 6.01% —


This is the single most decisive segmentation in the report. A 422-basis-point CAGR spread between two segments of comparable size compounds into a structural reversal: on the extracted growth rates, industrial online systems overtake lab-based systems during the early 2030s and hold a clear majority by 2035. The strategic implication for vendors is that revenue quality changes with the mix — lab instruments are sold to procurement against specification and price, while online systems are sold to operations against a payback case and carry installation, integration, service and method-support revenue that materially extends lifetime value. Vendors whose commercial organisation is built around the laboratory channel face a genuine go-to-market transition, not merely a product transition.

By End-User Industry

Segment 2025 Value (USD Mn) Share (2025) CAGR (2026–2035) Primary Demand Driver
Pharmaceutical 45,173.01 27.33% 6.57% Bioavailability and dissolution control; regulatory quality requirements; continuous manufacturing
Chemical Industry 31,421.75 19.01% 6.22% Continuous-process control; catalyst and specialty product consistency
Mining 28,414.92 17.19% 5.38% Comminution circuit optimisation; recovery and energy efficiency
Food Processing 24,565.51 14.86% 6.18% Sensory consistency; dispersibility; food-safety documentation
Cement Industry 20,825.33 12.60% 5.32% Grinding energy efficiency; clinker and finish-mill quality control
Others 14,910.90 9.02% 5.59% Ceramics, coatings, batteries, cosmetics, construction materials
Total 165,311.42 100.00% 6.01% —


The vertical mix separates cleanly into two growth cohorts. Pharmaceutical (6.57%), Chemical (6.22%) and Food Processing (6.18%) all exceed the global rate and together account for 61.20% of 2025 revenue; what they share is that particle size is a product-quality attribute with direct commercial or regulatory consequence. Mining (5.38%) and Cement (5.32%) fall below the global rate; here particle size is a process-efficiency variable, so demand tracks capital cycles and energy economics rather than product specification. Pharmaceutical is the standout because it is dominant and fastest simultaneously — a combination that concentrates strategic attention and explains why both Malvern Panalytical and HORIBA directed their most recent portfolio moves at pharmaceutical and biotechnology workflows.

By Region

Segment 2025 Value (USD Mn) Share (2025) CAGR (2026–2035) Primary Demand Driver
Europe 48,229.44 29.17% 5.98% Pharmaceutical and specialty chemical density; energy-efficiency mandates
North America 47,621.27 28.81% 5.54% Regulated pharmaceutical manufacturing; large legacy installed base
Asia-Pacific 40,669.12 24.60% 6.82% Greenfield industrial capacity; electronics and battery materials
South America 14,937.08 9.04% 5.07% Mining and mineral processing; food and beverage
Middle East & Africa 13,854.51 8.38% 6.15% Petrochemical downstream; cement; industrial diversification


Total 165,311.42 100.00% 6.01% —


The regional structure is notably balanced by the standards of industrial instrumentation markets: no bloc exceeds 30% share, and the top two are separated by less than half a percentage point of global revenue. This balance is itself a strategic fact — it means no vendor can build a defensible global position from a single-region base, and it raises the value of service and application coverage across all five blocs. The growth ranking (Asia-Pacific 6.82% > MEA 6.15% > Europe 5.98% > North America 5.54% > South America 5.07%) inverts the size ranking almost exactly for the two mature blocs, confirming a classic maturity gradient where installed-base depth trades off against growth rate.

Competitive Benchmarking

The Global Online Particle Size Market is moderately concentrated. The estimated Herfindahl-Hirschman Index, computed from the disclosed share distribution, falls in the range of approximately 1,030 to 1,100 — above the unconcentrated threshold but well below the level associated with dominant-firm structures. The top three vendors (Malvern Panalytical, HORIBA, Anton Paar) hold a combined 44.5%, and the top five reach 63.4%, leaving a competitive fringe of specialist and regional suppliers grouped at 9.0%. Competition is fought less on instrument specification than on three adjacent dimensions: breadth of technique portfolio (which determines eligibility for multi-technique workflow contracts), depth of application and method support (which determines the total cost of ownership for the customer), and global service density (which is decisive in the greenfield-heavy Asia-Pacific and MEA blocs). The January 2026 Creoptix acquisition and HORIBA's May 2025 pharmaceutical workflow expansion are both plays for the first of these dimensions.

Company Est. Revenue Share Key Offerings Strategic Positioning
Malvern Panalytical Ltd 18.5% Laser diffraction, dynamic light scattering, image analysis, X-ray and materials characterisation platforms Clear market leader; pursuing multi-technique consolidation via the Creoptix acquisition (Jan 2026); AI-enabled flagship platform (Mastersizer 3000+)
HORIBA Ltd 14.2% Particle characterisation, spectroscopy, process and environmental monitoring instruments Strong number two with an integrated discovery-to-manufacturing pharmaceutical portfolio (May 2025); deep Asia-Pacific service base
Anton Paar GmbH 11.8% Particle characterisation, rheometry, density and concentration measurement Premium engineering positioning; strength in European specialty chemicals, pharma and materials
Shimadzu Corporation 10.5% Laser diffraction and analytical instrumentation across chromatography, spectroscopy and testing Broad analytical-instrument franchise; leverages cross-selling into pharmaceutical and materials laboratories
Micromeritics Instrument Corporation 8.4% Particle size, surface area, porosity and density characterisation Specialist in powder and porous-material characterisation; strong catalysis, pharma and battery-materials niches
TSI Incorporated 7.6% Aerosol and airborne particle measurement, respiratory and environmental instrumentation Differentiated in aerosol and inhaled-product applications; adjacency to air quality and filtration testing
Sympatec GmbH 6.2% Laser diffraction, dynamic image analysis, and in-line/on-line process systems Focused specialist in industrial online measurement — direct exposure to the 8.09% CAGR system-type segment
Bettersize Instruments Ltd 5.8% Laser diffraction, image analysis and powder characterisation instruments Cost-competitive challenger with strong Asia-Pacific position; benefits from greenfield price sensitivity
Brookhaven Instruments 4.3% Dynamic light scattering, zeta potential and nanoparticle characterisation Nanoscale specialist; leveraged to the nanotechnology demand driver
Microtrac Retsch GmbH ~3.7% (residual) Laser diffraction, dynamic image analysis, sieving and sample-preparation systems Only profiled company without an explicitly disclosed share; the 3.7% residual between the disclosed shares (96.3%) and 100% is attributed here. Unusual position spanning both sieving and optical techniques
Other Market Players 9.0% Regional and niche particle characterisation suppliers Fragmented fringe; primary source of price competition in cost-sensitive greenfield markets
Total 100.0% — —


Recent News & Developments

Malvern Panalytical Ltd (January 2026)

Malvern Panalytical strengthened its high-end analytical portfolio through the acquisition of Creoptix, adding capabilities in advanced measurement technologies with particular emphasis on biomolecular interaction analysis and high-sensitivity detection. The transaction is expected to complement the company's existing particle characterisation and materials analysis solutions, enabling more comprehensive multi-technique workflows across pharmaceuticals, biotechnology and advanced materials research. The market significance is twofold. First, it confirms that the competitive contest at the top of the market has moved from instrument specification to workflow breadth — a customer running formulation development wants size, stability and interaction data from a single validated vendor relationship. Second, it is a defensive as well as an offensive move: with an estimated 18.5% share and a top-three combined position of 44.5%, the leader consolidates capability adjacent to its core rather than acquiring share in the core itself, which is the pattern typical of a moderately concentrated market approaching the limits of horizontal consolidation [15].

HORIBA Ltd (May 2025)

HORIBA expanded its pharmaceutical instrument portfolio with integrated solutions spanning the complete workflow from drug discovery through to manufacturing, combining advanced particle characterisation, spectroscopy and process monitoring systems designed to strengthen quality control, support regulatory compliance and enable real-time analysis in both laboratory and production environments. This development targets the largest and fastest-growing vertical in the study — pharmaceutical, at USD 45,173.01 Million and 6.57% CAGR — and it does so specifically at the laboratory-to-production boundary that defines the market's central structural transition. The explicit inclusion of production-environment real-time analysis places the offering directly in the Industrial Online Systems segment growing at 8.09% CAGR. For the number-two vendor at 14.2% share, building a continuous measurement chain from discovery to commercial supply is a credible route to displacing incumbents at the point where a customer standardises methods across development and manufacturing [16].

Malvern Panalytical Ltd (April 2024)

Malvern Panalytical introduced the Mastersizer 3000+ platform, incorporating AI-enabled features to improve particle size measurement accuracy and automation — a development characterised in the record as reflecting the broader shift toward intelligent and digitalised particle characterisation systems. Its commercial importance lies in the restraint it attacks. Technical complexity and expertise requirements carry an assigned 28% drag on market growth, and that barrier is what confines a majority of revenue to the centralised laboratory (54.32% of 2025 value, growing at only 3.87%). Automating method selection and result validation moves capability from the specialist to the instrument, widening the addressable customer base to organisations without a dedicated particle scientist. The launch also set a competitive baseline: with the market leader shipping AI-enabled features in its flagship, intelligent automation becomes a specification expectation rather than a differentiator over the forecast period, and vendors in the 4–8% share band face a development requirement they must fund from a smaller revenue base [17].

Online Particle Size Market Report Scope

Parameter Detail
Market Scope Global Online Particle Size Market — instrumentation, systems and associated solutions for particle size measurement across laboratory and industrial online deployment
Study Period 2019–2035
CAGR Window 2026–2035
Base Year 2025
Market Size (2025) USD 165.31 Billion
Market Size (2035) USD 293.69 Billion
CAGR (2026–2035) 6.01%
Fastest Growing Region Europe (metadata register); Asia-Pacific at 6.82% per the sizing model — see Section 7 reconciliation note
Dominant Region North America (metadata register); Europe at USD 48,229.44 Mn per the sizing model — see Section 7 reconciliation note
Fastest Growing Segment — By Measurement Technique Image Analysis (7.52% CAGR)
Fastest Growing Segment — By System Type Industrial Online Systems (8.09% CAGR)
Fastest Growing Segment — By End-User Industry Pharmaceutical (6.57% CAGR)
Fastest Growing Segment — By Region Asia-Pacific (6.82% CAGR)
Dominant Segment — By Measurement Technique Laser Diffraction (USD 68,998.84 Mn; 41.74%)
Dominant Segment — By System Type Lab-Based Systems (USD 89,803.12 Mn; 54.32%)
Dominant Segment — By End-User Industry Pharmaceutical (USD 45,173.01 Mn; 27.33%)
Companies Profiled Malvern Panalytical Ltd; HORIBA Ltd; Anton Paar GmbH; Microtrac Retsch GmbH; Bettersize Instruments Ltd; Micromeritics Instrument Corporation; Shimadzu Corporation; TSI Incorporated; Sympatec GmbH; Brookhaven Instruments (10 companies)
Valuation Currency USD; segment and regional detail reported in USD Million, global headline restated in USD Billion
Segments Covered By Measurement Technique; By System Type; By End-User Industry; By Region
Regional Coverage North America; Europe; Asia-Pacific; South America; Middle East & Africa
Methodology Bottom-up segment build-up reconciled top-down against vendor revenue; primary interviews with OEMs and end users; secondary validation against standards bodies, regulatory agencies and industry statistics
Data Limitations Annual values for 2019–2023 and segment-level 2035 values were not present in the extracted dataset and have not been estimated; 2028, 2033 and 2034 global values are geometric interpolations between extracted anchors and are flagged in Section 3; country-level revenue splits were not available and country tables are qualitative

FAQs

How large is the Global Online Particle Size Market and how fast is it growing?
The Online Particle Size Market was valued at (USD 165.31 Billion) in 2025 and is forecast to reach (USD 293.69 Billion) by 2035, a CAGR of 6.01% over the 2026–2035 window. Growth is not uniform across the period: annual expansion troughs at 4.94% in 2027 before re-accelerating to a 6.38–6.49% band from 2031, reflecting a capital-equipment cycle in the heavy-industry verticals that drive online system adoption.
What is the most important structural shift underway in this market?
The migration from laboratory batch measurement to continuous industrial online measurement. Lab-Based Systems still hold 54.32% of 2025 revenue (USD 89,803.12 Million) but grow at only 3.87% CAGR, while Industrial Online Systems (USD 75,508.30 Million, 45.68%) compound at 8.09% — the highest CAGR of any segment in the study. On these trajectories, online systems overtake lab-based revenue during the early 2030s, which changes not just the product mix but the commercial model, since online systems are sold to operations against a payback case and carry substantially more service and integration revenue.
Which measurement technique should investors watch, and which is at risk?
Laser Diffraction is the commercial anchor at USD 68,998.84 Million (41.74% share) and 7.06% CAGR, while Image Analysis is the fastest growing at 7.52%, driven by demand for shape and morphology data rather than size alone. Sieving is the segment at risk: at 1.93% CAGR from a USD 31,269.96 Million base, it grows below inflation in most economies and is being structurally displaced by optical methods, held in place mainly by entrenched specifications rather than by technical merit.
Which end-user industry offers the best growth-adjusted exposure?
Pharmaceutical is the standout because it is both the largest vertical (USD 45,173.01 Million, 27.33% share) and the fastest growing (6.57% CAGR). Particle size in pharmaceutical manufacturing governs bioavailability, deposition and aggregation risk, which places it inside the regulatory filing rather than in discretionary process improvement — making demand less sensitive to capital cycles than in mining (5.38%) or cement (5.32%). Both Malvern Panalytical and HORIBA have directed their most recent strategic moves at this vertical.
Which region grows fastest, and why does the report metadata differ from the sizing model?
The sizing model shows Asia-Pacific Online Particle Size Market with the highest forecast CAGR at 6.82% from a USD 40,669.12 Million base, ahead of the Middle East & Africa at 6.15% and Europe at 5.98%; it also shows Europe marginally largest in 2025 at USD 48,229.44 Million versus North America's USD 47,621.27 Million. The report metadata register instead designates Europe as fastest growing and North America as dominant. Both are reported in Section 7; the two mature blocs are separated by only 0.37% of the global market and are best treated as co-leading, while Asia-Pacific is the unambiguous growth leader.
How concentrated is the competitive landscape, and is it likely to consolidate further?
The Online Particle Size Market is moderately concentrated, with an estimated HHI of roughly 1,030–1,100, a top-three share of 44.5% and a top-five share of 63.4%, led by Malvern Panalytical at 18.5% and HORIBA at 14.2%. Further consolidation is likely to be adjacent rather than horizontal — the January 2026 Creoptix acquisition added capability next to the core rather than share within it — because customers are increasingly buying multi-technique validated workflows. Offsetting this, Asia-Pacific's 6.82% growth creates a price-sensitive greenfield segment that sustains the 9.0% competitive fringe.
What is the single biggest barrier to faster market growth?
High initial investment costs carry the largest assigned drag at 30%, closely followed by technical complexity and expertise requirements at 28%. The capital barrier is most visible in South America, the slowest-growing bloc at 5.07% CAGR despite hosting world-scale mining operations that are technically ideal for online measurement. The expertise barrier is the more tractable of the two, since AI-enabled automation of the type introduced in the Mastersizer 3000+ transfers method knowledge into the instrument — which is why Section 6.1 identifies AI integration as the market's highest-value opportunity.
Where should a vendor allocate incremental investment over 2026–2030?
The data points to a two-part allocation: industrial online system capability (8.09% CAGR) and Asia-Pacific service and application coverage (6.82% CAGR), with pharmaceutical workflow integration as the highest-value vertical overlay (USD 45,173.01 Million at 6.57%). The corresponding disinvestment case is sieving-anchored product lines at 1.93% CAGR, and the corresponding risk is that lab-channel commercial organisations are poorly configured to sell online systems to operations buyers — a go-to-market transition that typically takes longer than the product transition it accompanies.                                                  
Author
Author Author Profile Chitranshi Jaiswal LinkedIn Team Lead - Research
Chitranshi is a Team Leader in the Chemicals & Materials (CnM) and Energy & Power (EnP) domains, with 6+ years of experience in market research. She leads and mentors teams to deliver cross-domain projects that equip clients with actionable insights and growth strategies. She is skilled in market estimation, forecasting, competitive benchmarking, and both primary & secondary research, enabling her to turn complex data into decision-ready insights. An engineer and MBA professional, she combines technical expertise with strategic acumen to solve dynamic market challenges. Chitranshi has successfully managed projects that support market entry, investment planning, and competitive positioning, while building strong client relationships. Certified in Advanced Excel & Power BI she leverages data-driven approaches to ensure accuracy, clarity, and impactful outcomes.
Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Global Magnesium Sulfate Market – Forecast till 2027
Case Study
Chemicals and Materials
Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.


















