Ceramics Market Summary
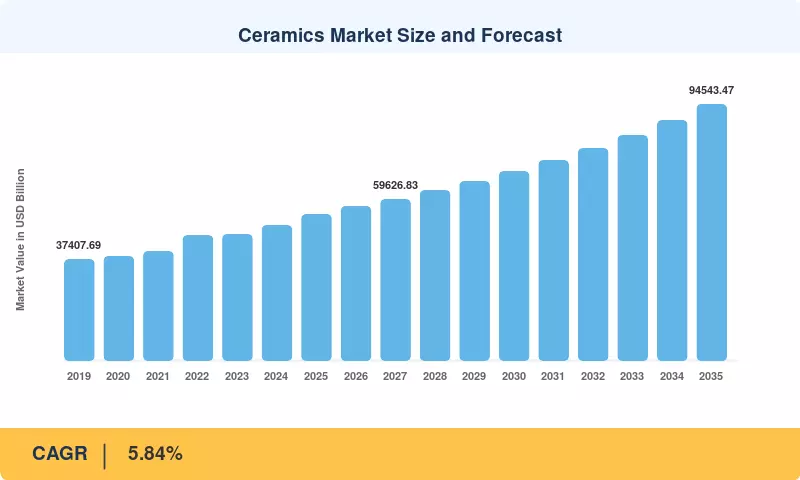
The global ceramics market was valued at USD 53,798.29 Million in 2025 and is projected to reach USD 94,543.47 Million by 2035, expanding at a compound annual growth rate of 5.84% over the 2026–2035 forecast window. The Ceramics Market size in the forecast year (2026) is estimated to be USD 56,703.26 Million, and the market is expected to grow by USD 37,840.21 Million in incremental revenue throughout the forecast period of nine years to reach the anticipated market size of USD 94,543.48 Million. Growth is structurally anchored in two demand engines identified in MRFR primary research. Growing demand from the electronics industry, where multilayer ceramic capacitors, substrates and packaging materials are scaling with AI datacenter and electric-vehicle build-out. Increasing applications in aerospace and defense, where ceramic matrix composites and armour-grade ceramics are displacing metallic assemblies. This interpretation is supported by the historical series: the market rose from USD 37,407.69 Million in 2019 to USD 49,703.28 Million in 2024, a 5.85% historical CAGR that is almost comparable to the forward prediction, suggesting a mature but sustainable demand base rather than a cyclical spike. The most important historical change was in 2022 (+14.90% y-o-y), when construction and refractory restocking resumed after the pandemic, followed by a flat 2023 (+0.46%) as stockpiles of tiles and sanitaryware were rectified.[3][7].
The material transition occurring is the change from volume-driven, clay-based ceramic bodies to designed technological ceramics with electrical, thermal and structural properties. Clay-based products will still generate the most revenue in 2025 at USD 31,449.32 million, or 58.46% of the global market, rising to USD 44,772.30 million by 2035. However, growth will be sluggish at just 3.60%, well below the market average, meaning their share will fall to around 47.4% by the end of the forecast. Titanate ceramics are the fastest-growing class of material, growing at 11.48% CAGR from USD 9,815.24 million to USD 29,406.51 million, nearly doubling in a decade and surpassing all other technical ceramic categories. Alumina ceramics (5.68% CAGR) and zirconia ceramics (5.33% CAGR) also beat the clay-based basis. This is supported by commercial activity from the leading players. For instance, in April 2026, KYOCERA Corporation developed a multilayer ceramic core substrate for advanced AI semiconductors, offering increased rigidity and improved circuit miniaturization for next-generation data center and ASIC packaging, and launched it at the ECTC 2026. Murata Manufacturing Co., Ltd. has started mass production of its DE5 series of automotive safety-certified lead-type disk ceramic capacitors in July 2026. The DE5 series has Y1 class certification and a higher rating and impulse withstand voltage than previous generations. Both developments are dead in the center of the titanate and alumina value pools, which are compounding at double and almost double the market rate. [2][4][9][11].
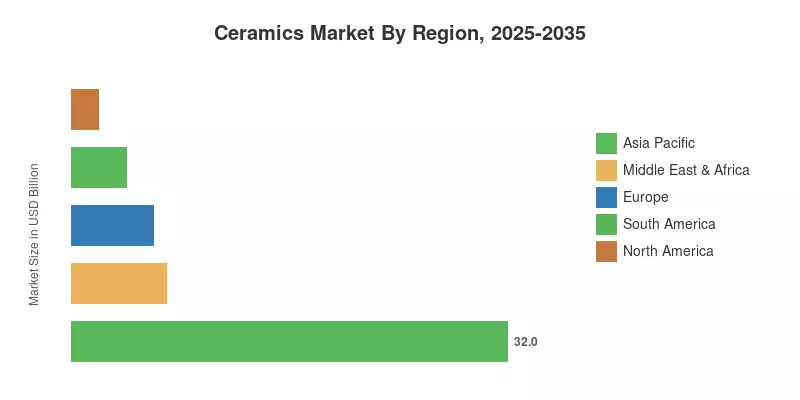
Asia Pacific is the largest region in the Ceramics Market, with sales of USD 32,595.37 million in 2025, accounting for a 60.59% share of global revenue, and will reach USD 56,165.37 million in 2035, growing at a CAGR of 5.64%. This growth rate is slightly below average, but the absolute dollar growth of USD 23,570.00 million is the largest among all regions. Middle East & Africa is the fastest-expanding region at 6.91% CAGR, going from USD 7,113.17 million to USD 13,815.55 million. This is due to GCC construction programs (6.98% CAGR) and South Africa (7.47% CAGR, the fastest single market after the United Kingdom). Middle East & Africa is also the second-largest market in 2025 with a share of 13.22%, marginally ahead of Europe at USD 6,245.83 million (11.61% share, 6.02% CAGR). North America is the smallest block at USD 2,889.53 million, but it is the second fastest at 6.41%. Looking forward, the center of gravity for the market remains in Asia Pacific volume-wise. At the same time, leadership in margins and growth shifts to technical-ceramic demand centers in Europe, North America and the Gulf, where electronics, defense, medical and energy-transition applications command considerably higher realized prices per ton.[5][6][12].
Key Report Takeaways
| Segment Dimension | Key Metric | Notes |
|---|---|---|
| Global Market | USD 53,798.29 Mn (2025) → USD 94,543.47 Mn (2035) | 5.84% CAGR over 2026–2035; 2025 is the base year |
| Global Market — Historical | USD 37,407.69 Mn (2019) → USD 49,703.28 Mn (2024) | 5.85% historical CAGR; peak YoY growth of 14.90% in 2022 |
| By Materials — Dominant | Clay-based: USD 31,449.32 Mn, 58.46% share (2025) | Grows to USD 44,772.30 Mn by 2035 at 3.60%; share compresses to ~47.4% |
| By Materials — Fastest Growing | Titanate ceramics: 11.48% CAGR | USD 9,815.24 Mn → USD 29,406.51 Mn; the single fastest sub-segment in the report |
| By Application — Dominant | Ceramic Tiles: USD 24,905.42 Mn, 46.29% share (2025) | Grows to USD 40,929.38 Mn at 5.14%; tied to residential and commercial construction cycles |
| By Application — Fastest Growing | Ceramic matrix composites (CMCs): 7.14% CAGR | USD 9,465.18 Mn → USD 18,808.41 Mn; second-largest application by 2035 |
| By Application — Secondary Growth | Ceramic filters: 6.82% CAGR | USD 4,414.15 Mn → USD 8,505.79 Mn on emissions and water-treatment mandates |
| By End-use — Dominant | Building & Construction: USD 29,489.28 Mn, 54.81% share (2025) | Grows to USD 49,741.03 Mn at 5.41%; remains the majority end-use throughout the forecast |
| By End-use — Fastest Growing | Electrical & Electronics: 7.16% CAGR | USD 5,280.71 Mn → USD 10,511.55 Mn; share rises from 9.82% to ~11.1% |
| By End-use — Defence | Defence & Security: USD 5,681.02 Mn (2025), 6.34% CAGR | Reaches USD 10,463.36 Mn by 2035; second-largest non-construction end-use |
| Regional — Dominant | Asia Pacific: USD 32,595.37 Mn, 60.59% share (2025) | Largest absolute gain of any region: +USD 23,570.00 Mn by 2035 |
| Regional — Fastest Growing | Middle East & Africa: 6.91% CAGR | USD 7,113.17 Mn → USD 13,815.55 Mn; overtakes Europe in absolute size |
| Country — Fastest Growing | United Kingdom: 7.81% CAGR | USD 456.45 Mn → USD 965.63 Mn; fastest single national market in the model |
| Country — Largest | China: USD 15,036.40 Mn (2025) | 27.95% of the global market alone; grows to USD 25,170.33 Mn at 5.33% |
| Competitive Structure | Top 7 named players hold 7.0% combined share | "Others" retains 93.0% — a highly fragmented, regionally clustered market |
Market Size and Forecast (2019–2035)
MRFR sizes the global ceramics market using a hybrid bottom-up and top-down methodology. The bottom-up build aggregates verified shipment and revenue data at the country level across five regional blocs and 30+ national markets, cross-referencing producer association statistics, customs and trade flow data, and audited financial disclosures from the principal manufacturers. These are reconciled against a top-down view derived from downstream consumption indicators — construction floor-space additions, electronics production indices, vehicle output, refractory intensity per tonne of steel and cement, and defence procurement budgets. The 2025 base year is triangulated against primary interviews with manufacturers, distributors and specifying engineers. Forecast years apply application-specific demand elasticities against macro drivers, with technical-ceramic segments modelled on installed-capacity and design-win pipelines rather than on GDP proxies. All values are stated in USD million at constant 2025 exchange rates, so the projections exclude currency translation effects.[3][13]




 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA



