Hot Dip Galvanized Steel Wire Market Summary
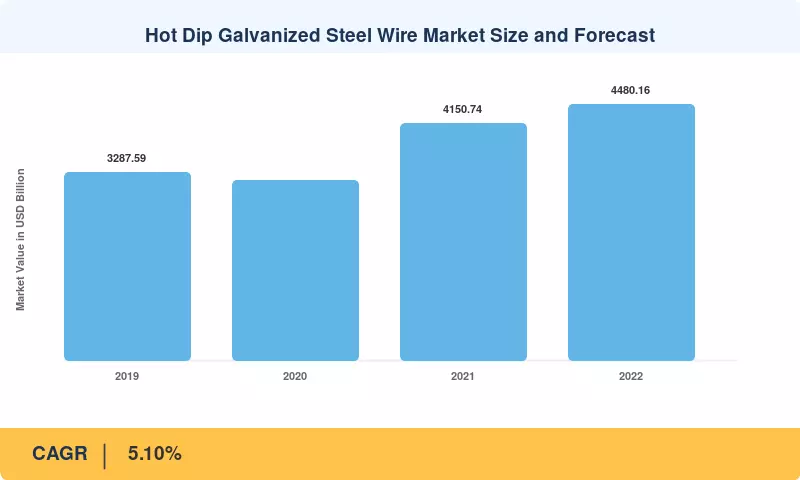
The global hot-dip galvanized steel wire market was valued at USD 3,483.76 Million (USD 3.48 Billion) in 2025, the base year of this study, and is projected to reach USD 6,030.13 Million (USD 6.03 Billion) by 2035, expanding at a compound annual growth rate of 5.10% over the 2026–2035 forecast window. The forecast period opens from a base of USD 3,869.55 Million in 2026, a step-up of 11.07% over the 2025 trough that reflects the normalisation of zinc and steel billet input costs after three consecutive years of contraction between 2023 and 2025. Two structural forces underpin the ten-year trajectory. The first is a robust infrastructure and construction boom, which sustains volume demand for galvanized fencing, mesh reinforcement, armouring wire, guardrail cable and pre-stressing strand across both mature and emerging economies. The second is a durable shift toward corrosion-resistant materials, driven by lifecycle-cost accounting in public procurement, longer asset-design lives for bridges, transmission networks and coastal structures, and tightening maintenance budgets that reward first-cost premiums for zinc-coated product. The historical series makes the cyclicality of this market plain: revenue peaked at USD 4,480.16 Million in 2022 before falling to USD 3,755.17 Million in 2023 and USD 3,543.47 Million in 2024, a correction driven overwhelmingly by input pricing rather than by underlying tonnage demand [1][3][7].
The most consequential product transition inside the market is the migration from light-gauge zinc coatings toward heavy-coating and high-tensile specifications. Heavy Coating is the largest coating class at USD 1,204.23 Million in 2025 (34.57% of global revenue) and is also the fastest-growing at 5.40% CAGR, edging ahead of Light Coating at USD 1,200.84 Million (34.47%) growing at 4.60%. The same pattern repeats on the metallurgical axis: High Tensile Steel Wire is the single largest tensile-strength segment at USD 900.33 Million (25.84%), while High Carbon Steel Wire is the fastest-growing at 5.40% from a 2025 base of USD 408.67 Million (11.73%). The commercial logic is consistent — buyers are trading up on coating mass and tensile grade to extend service intervals in aggressive environments, and producers are consolidating capacity around the higher-margin end of that mix. Corporate activity confirms the direction. In August 2025, Tata Steel's indirect subsidiary The Siam Industrial Wire Company acquired the residual 40% stake in TSN Wires from Nichia Steel Works for a nominal THB 100, converting TSN Wires into a wholly owned subsidiary and streamlining its South-East Asia wire operations. In January 2025, N.V. Bekaert agreed to divest its Steel Wire Solutions businesses in Costa Rica, Ecuador and Venezuela to Grupo AG for an enterprise value of approximately USD 73 Million, explicitly to reduce exposure to volatile markets and concentrate on higher-growth, higher-margin segments [11][12].
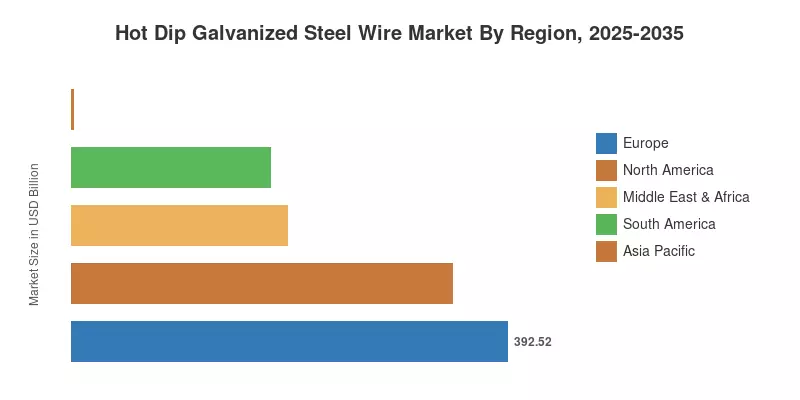
Regionally, the hot-dip galvanized steel wire market is heavily concentrated. Asia Pacific accounts for USD 2,373.98 Million in 2025, or 68.14% of global revenue, and is simultaneously the fastest-growing region at a 5.30% CAGR through 2035 — an unusual combination of scale and momentum that reflects the region's integrated position as both the world's largest wire-rod producer and its largest construction market. Europe is the second-largest region at USD 392.52 Million (11.27%) but the slowest-growing at 3.90%, constrained by mature construction volumes and carbon-cost pass-through on primary steelmaking. North America follows at USD 343.23 Million (9.85%) growing at 4.70%, with Middle East & Africa at USD 194.84 Million (5.59%) at 5.00% and South America at USD 179.20 Million (5.14%) at 4.90%. Over the forecast horizon, the centre of gravity shifts further east: on current model trajectories Asia Pacific extends its share while Europe's contracts, leaving global growth increasingly dependent on Asian infrastructure cycles and on the pace at which coating-mass upgrades penetrate high-volume, price-sensitive applications [1][4].
Key Report Takeaways
| Segment Dimension | Key Metric | Notes |
| Global Market | USD 3,483.76 Mn (2025) → USD 6,030.13 Mn (2035) | 5.10% CAGR over 2026–2035; base year is a cyclical trough |
| Global Market | USD 3,869.55 Mn (2026) | Forecast opens 11.07% above the 2025 base on input-cost normalisation |
| Region — Dominant | Asia Pacific, USD 2,373.98 Mn (68.14%) | Largest region by a factor of six over the next-largest |
| Region — Fastest Growing | Asia Pacific, 5.30% CAGR | Rare case where the dominant region is also the fastest-growing |
| Region — Slowest Growing | Europe, 3.90% CAGR | USD 392.52 Mn in 2025; mature demand, high carbon-cost exposure |
| Coating Thickness — Dominant | Heavy Coating, USD 1,204.23 Mn (34.57%) | Marginally ahead of Light Coating at USD 1,200.84 Mn |
| Coating Thickness — Fastest Growing | Heavy Coating, 5.40% CAGR | 80 bps above the global average; lifecycle-cost driven |
| Tensile Strength — Dominant | High Tensile Steel Wire, USD 900.33 Mn (25.84%) | Anchored in pre-stressing, armouring and cable applications |
| Tensile Strength — Fastest Growing | High Carbon Steel Wire, 5.40% CAGR | USD 408.67 Mn base; fastest metallurgical grade |
| Tensile Strength — Slowest Growing | Mild Steel Wire, 4.70% CAGR | USD 277.70 Mn (7.97%); commoditised, price-led |
| Application — Dominant | Construction, USD 921.28 Mn (26.44%) | Largest single application across all dimensions |
| Application — Fastest Growing | Power & Utilities, 5.40% CAGR | USD 452.15 Mn base; grid build-out and ACSR/guy-wire demand |
| Application — Smallest | Marine, USD 95.53 Mn (2.74%) | Small base, 4.80% CAGR, highest coating-mass intensity |
| Competitive Structure | Top 5 players ≈ 27.8% of revenue | Highly fragmented; "Others" hold 72.2% |
| Competitive Structure | N.V. Bekaert leads at 7.8% | Followed by Tianjin Huayuan at 7.5% |
MARKET SIZE AND FORECAST (2019–2035)
MRFR's estimate for this hot-dip galvanized steel wire market is built bottom-up from wire-rod conversion volumes and zinc coating-mass intensity, then reconciled top-down against reported wire-division revenues for the ten profiled producers and against national trade statistics for HS 7217.20 (iron/non-alloy steel wire, zinc-plated or coated). Volume is estimated per application from construction put-in-place data, transmission and distribution capital expenditure, agricultural fencing replacement cycles and automotive spring/tyre-cord consumption. Realised revenue is then derived by applying weighted average selling prices that track LME zinc settlement and regional wire-rod benchmarks with a one-to-two quarter lag, which is the principal reason the historical series shows a sharp 2021–2022 revenue expansion and an equally sharp 2023–2025 contraction against comparatively stable underlying tonnage. Figures are stated in USD Million at prevailing exchange rates, with 2025 as the base year [1][3][8][14].



 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA


