Paints Inks Coatings Market Summary
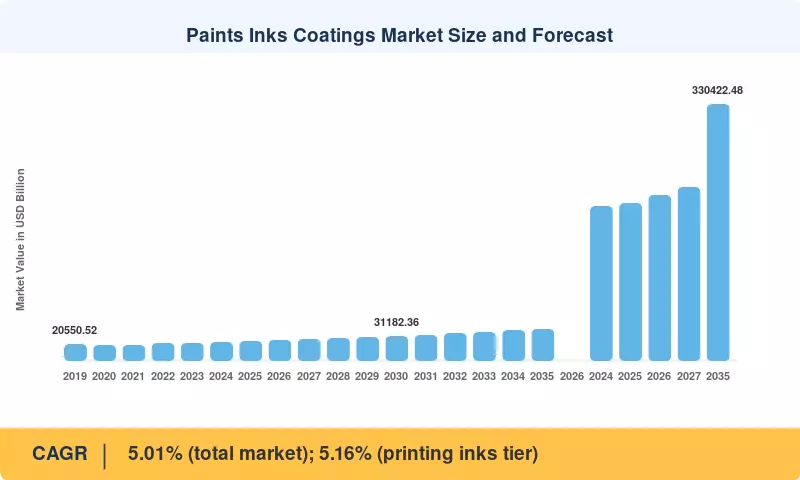
The global paints, inks and coatings market was valued at USD 203,222.18 million in 2025, advancing to USD 212,844.70 million in 2026 — the first projected year of the forecast window — and reaching USD 330,422.48 million by 2035, a compound annual growth rate of 5.01% across 2026–2035. This is a 2.44% elevation from the 2024 historical base of USD 198,376.84 million in the 2025 base year. The step into 2026 accelerates up to 4.74%, as construction pipelines released after a slow 2023-2024 industrial cycle start to convert into coating volumes. Two structural drivers explain almost all of the modeled acceleration. Urbanization and building expansion are the major drivers, driving the architectural end-use segment, which alone accounts for USD 83,938.53 million, or 41.30% of the total market value in 2025. The second is automotive and EV manufacturing growth, supporting an automotive end-use block valued at USD 40,986.97 million in 2025 and forecast to reach USD 67,277.94 million by 2035 at a 5.11% CAGR, as electrified platforms alter specifications to low-temperature-cure, lightweight-substrate and battery-enclosure coating systems, which command higher value per vehicle than conventional bodyshop finishes. Both are challenged by the volatility in raw material prices for titanium dioxide, epoxy and acrylic monomer and solvent feedstocks, which takes out about 60-80 basis points from the feasible CAGR compared to an unconstrained demand path.
The defining technology transition is moving away from solvent-borne chemistry to compliant systems. Water-borne technology is already the largest technology segment at USD 87,489.14 million in 2025 – 43.05% of total value – rising to USD 139,598.67 million by 2035. Powder coating is the fastest-growing technology at a 5.85% CAGR, expanding from USD 41,488.92 million to USD 73,085.78 million and taking share from solvent-borne systems, which grow at only 4.28% and slip from 14.98% to 13.99% of the mix. The resin image tells the same story: acrylic remains on top with USD 74,100.72 million (36.46% share) on the back of architectural and waterborne formulation, while epoxy is the fastest-growing resin at 7.37% CAGR, doubling from USD 13,502.33 million to USD 27,389.42 million on protective, marine and infrastructure demand. Commercial evidence is very close to the model. With the November 2025 launch of Hempafire Optima 515, a waterborne intumescent that delivers certified fire ratings to 150 minutes under BS 476 at reduced dry film thickness and very low VOC, Hempel is making the kind of specification-led substitute that lifts waterborne value without lifting volume. Jotun’s August 2026 Jotachar 1709 XT, an all-climate UL1709 intumescent for oil and gas, shows the same economics in protective coatings, where decreased material consumption per protected square meter is presented as a total installed cost argument rather than a pricing argument. UV-cured inks are the fastest-growing type in printing inks at 7.16% CAGR (USD 3,648.22 million to USD 7,236.25 million), while solvent-based inks still dominate at USD 7,199.39 million but with a CAGR of only 3.97% – a gap confirmed by DIC Corporation’s May 2026 global launch of PVC-free SHIOLESS gravure ink and by Siegwerk’s June 2026 acquisition of Hi-Tech Inks.
Key Report Takeaways
| Segment Dimension | Key Metric | Notes |
|---|---|---|
| Total Market | USD 203,222.18 Mn (2025) → USD 330,422.48 Mn (2035); CAGR 5.01% | Base year 2025; forecast window 2026–2035 |
| Printing Inks Tier | USD 24,338.93 Mn (2025) → USD 40,114.67 Mn (2035); CAGR 5.16% | 11.98% of total market value in 2025, rising to 12.14% |
| By Resin Types — Dominant | Acrylic: USD 74,100.72 Mn (2025), 36.46% share | Anchored in architectural and water-borne formulation [3] |
| By Resin Types — Fastest | Epoxy: 7.37% CAGR (USD 13,502.33 Mn → USD 27,389.42 Mn) | Protective, marine, and infrastructure pull [4] |
| By Technology — Dominant | Water-borne: USD 87,489.14 Mn (2025), 43.05% share | VOC regulation converts compliance into value [5] |
| By Technology — Fastest | Powder Coating: 5.85% CAGR (USD 41,488.92 Mn → USD 73,085.78 Mn) | Near-zero VOC, high transfer efficiency, industrial substrates [5] |
| By End-use — Dominant | Architectural: USD 83,938.53 Mn (2025), 41.30% share | Direct exposure to urbanization and construction cycle [6] |
| By End-use — Fastest | Marine: 6.26% CAGR (USD 7,949.07 Mn → USD 14,566.81 Mn) | Highest-growth named segment; "Others" grows 6.61% [7] |
| By Types (Inks) — Dominant | Solvent-based Inks: USD 7,199.39 Mn (2025), 29.58% share | Largest but slowest at 3.97% CAGR — share erodes to 26.47% [8] |
| By Types (Inks) — Fastest | UV-cured Inks: 7.16% CAGR (USD 3,648.22 Mn → USD 7,236.25 Mn) | Fastest-growing segment anywhere in the report [8] |
| By Application (Inks) — Dominant | Packaging: USD 10,651.34 Mn (2025), 43.76% share | Grows 5.46% to USD 18,064.79 Mn [9] |
| By Application (Inks) — Fastest | Publication: 6.45% CAGR (USD 1,849.88 Mn → USD 3,446.75 Mn) | Smallest base (7.60% share) amplifies growth rate [9] |
| By Process (Inks) — Dominant & Fastest | Digital Printing: USD 9,020.74 Mn (2025), 37.06% share, 5.71% CAGR | Only segment leading in both size and growth [10] |
| Regional — Largest & Fastest | Asia Pacific: USD 10,614.15 Mn (2025), 43.61% share, 5.46% CAGR | China USD 5,181.86 Mn; India USD 2,818.99 Mn at 5.99% [11] |
| Country — Fastest | United Kingdom: 7.05% CAGR (USD 485.42 Mn → USD 957.23 Mn) | Highest country-level CAGR in the model [12] |
| Competitive Structure | Top six players ≈ 34% combined share; estimated HHI 300–450 | Unconcentrated; 66% held outside the named top six |
MARKET SIZE AND FORECAST (2019–2035)
MRFR sizes this market through a dual bottom-up and top-down reconciliation. The bottom-up build starts from shipment and consumption data at the resin, technology and end-use level, cross-checked against reported segment revenue in the annual filings of the profiled manufacturers. The top-down check applies coatings-intensity ratios to construction floor-space completions, vehicle production units and packaging substrate output, sourced from national statistical agencies and industry associations. Historical years (2019–2024) are reconciled to reported and association-published data; 2025 is the base year against which all shares are calculated; 2026–2035 are modelled forecasts driven by macro-demand elasticities, announced capacity, regulatory phase-in schedules and observed price-mix behaviour. All values are stated in nominal USD at prevailing average annual exchange rates. The table below presents the full time series at the printing inks tier, the only tier for which a complete 2019–2035 annual series is resolved in the model; total-market anchor values follow immediately after.




 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA



