Stolen Vehicle Recovery Market Summary
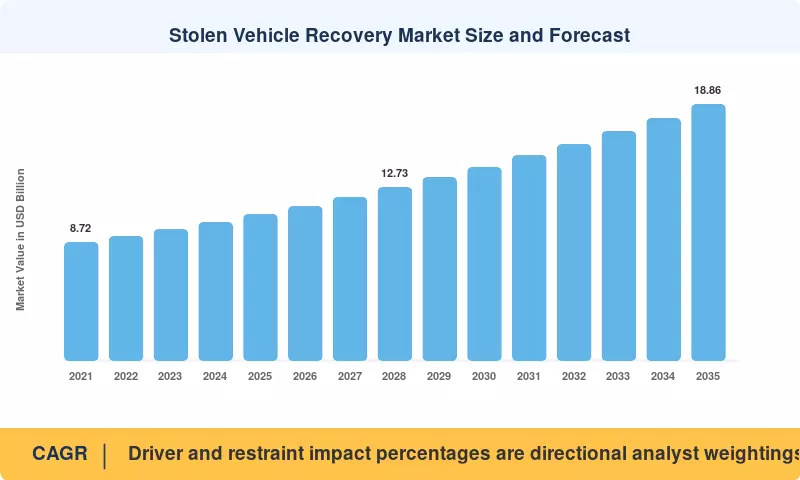
The Stolen Vehicle Recovery Market was valued at USD 10.79 Billion in 2025 and opens the forecast horizon at USD 11.37 Billion in 2026, climbing to USD 18.86 Billion by 2035 at a 5.78% CAGR. Two catalysts anchor that trajectory. Europe's General Safety Regulation II, mandatory for all new type approvals from July 2024, effectively hard-wires telematics into every vehicle sold across the bloc [4]. In parallel, coordinated automaker–police recovery programs in the United States have trimmed reported thefts by roughly 17% year over year, proving that spend on countermeasures converts into measurable outcomes [1].
Hardware is where the transformation bites hardest. Standalone radio-frequency beacons and 2G-tethered aftermarket boxes — the backbone of the 2010s — are giving way to multi-constellation GNSS modules paired with LTE-M and NB-IoT radios that cost a fraction of legacy bills of materials. Carriers retired more than 40 commercial 2G and 3G networks between 2022 and 2025, stranding an installed base that must be replaced rather than repaired, and OEM embedded stolen vehicle tracking now ships as a standard trim feature rather than a dealer upsell [7][12]. Insurers have underwritten the shift, with telematics-linked premium discounts reaching 15–25% in several North American and UK books [9].
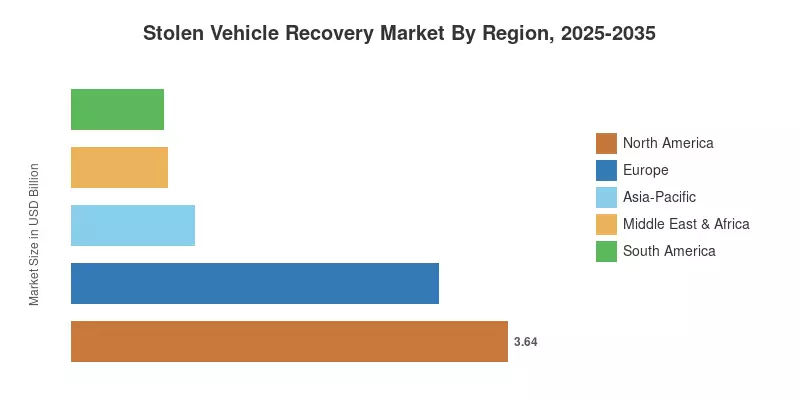
Geographically, North America commands 33.7% of the Stolen Vehicle Recovery Market on the strength of dense law-enforcement integration and mature subscription channels. Asia-Pacific grows fastest at a 9.5% CAGR through 2035, propelled by India's AIS-140 tracking mandate and China's fleet-digitization push [13][16]. Europe holds second position, where regulatory compulsion rather than consumer choice drives attach rates. Expect the competitive centre of gravity to migrate from device margins toward recurring data and recovery-service revenue over the coming decade.
Key Report Takeaways
• By Technology
- GPS/GNSS platforms held 57.8% of Stolen Vehicle Recovery Market revenue in 2025, reflecting entrenched multi-constellation receiver economics.
- LoRa/NB-IoT is the fastest-expanding technology cohort at a 10.0% CAGR through 2035.
- Cellular (LTE/5G) connectivity generated USD 2.33 Billion in 2025 as carriers repositioned IoT tariffs.
• By Security Solution
- Tracking and recovery devices accounted for 44.1% of solution revenue in 2025.
- Immobilizers advanced at an 8.9% CAGR, the quickest among security solution categories.
• By End user
- Rental and leasing operators post a 7.8% CAGR as residual-value protection tightens.
• By Region
- North America led the Stolen Vehicle Recovery Market with 33.7% share in 2025.
- Asia-Pacific is set to compound at 9.5% annually through 2035.
- Europe contributed USD 3.06 Billion in 2025 under General Safety Regulation II compulsion.
Market Size and Forecast (2021–2035)
Figures below reconcile bottom-up device shipment tallies from tier-one telematics suppliers with top-down subscription revenue disclosed in operator filings, then cross-check both against national theft statistics published by the NICB, ONS, and Europol [1][2][3]. Currency effects are normalised to constant 2025 US dollars. The Stolen Vehicle Recovery Market series reflects hardware, installation, and recurring service revenue combined.