North America Pumps Market Summary
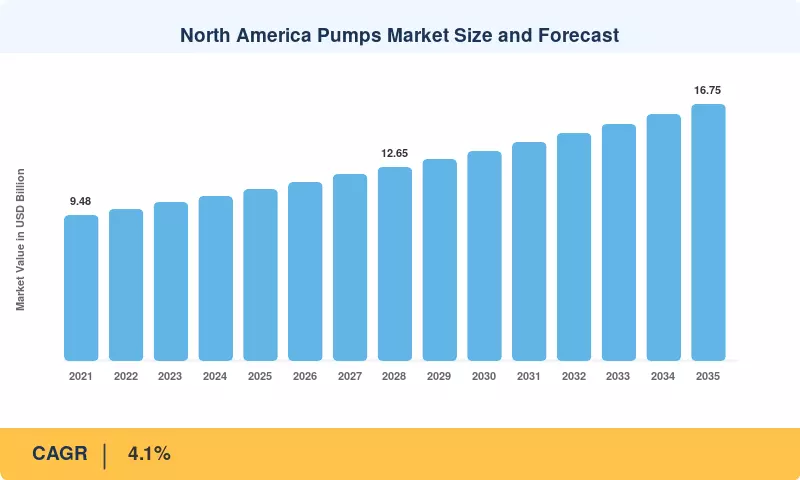
The North America Pumps Market was valued at USD 11.21 Billion in 2025. It is projected to grow from USD 11.67 Billion in 2026 to USD 16.75 Billion by 2035, a CAGR of 4.1% over 2026–2035. Two catalysts set the pace. The Infrastructure Investment and Jobs Act directs more than USD 50 billion to drinking water and wastewater programs administered by the EPA [1]. The April 2024 national PFAS drinking water standard also requires thousands of utilities to add treatment stages, and those stages depend on new high-pressure pumping [2].
Technology change is happening at the motor shaft and in the control cabinet. Fixed-speed, throttled installations are giving way to variable-frequency drives, electronically commutated motors and pumps fitted with sensors that report vibration, seal and bearing condition. The U.S. Department of Energy estimates that pumping systems account for roughly 25% of motor-driven energy use in US manufacturing [3]. Its circulator pump efficiency standard, finalized in 2024, pushes commercial buildings toward ECM designs [4]. As a result, buyers now compare bids on wire-to-water efficiency and lifecycle cost rather than on purchase price alone.
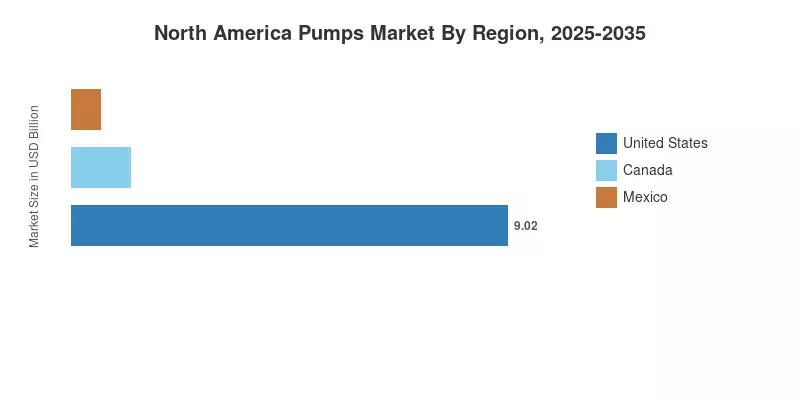
Geographically, the United States holds 80.5% of demand. Municipal upgrades, shale and LNG midstream activity, and a large installed base in chemicals support that lead. Mexico is the fastest-growing country at a 5.3% CAGR, as nearshored manufacturing and the federal water plan lift orders . Canada ranks second at USD 1.23 billion in 2025, led by Ontario's municipal systems and Alberta's oil sands. Over the next decade, suppliers that combine service networks, digital monitoring and local assembly are best placed to win replacement and retrofit business across the North America Pumps Market.
Key Report Takeaways
• By Pump Type
- Centrifugal designs hold 57.0% of the North America Pumps Market, anchored by municipal end-suction and split-case installations
- Positive-Displacement pumps generated USD 4.82 Billion in 2025, concentrated in metering, viscous and shear-sensitive duties
• By Drive Technology
- Electric Motor drives account for 66.5% of revenue as variable-frequency drive adoption spreads
- Solar/Renewable drives post the fastest growth at a 6.1% CAGR, supported by USDA REAP grants for irrigation [18]
• By Position
- Surface pumps hold 55.4% of revenue, reflecting the depth of the municipal and industrial installed base
- Submersible units expand at a 6.7% CAGR, the fastest rate of any segment in the North America Pumps Market, driven by mining dewatering and deeper wells
• By Application
- Water and Wastewater is both the largest and the fastest-growing application, advancing at a 5.4% CAGR
- Chemical and Petrochemical holds a 16.5% share, driven by API 610 replacements and emissions compliance
- HVAC and Building Services reached USD 1.35 Billion in 2025 as ECM circulators replace legacy units
• By Region
- The United States commands 80.5% of regional revenue
- Canada generated USD 1.23 Billion in 2025
- Mexico grows at a 5.3% CAGR, the fastest in the region
Market Size and Forecast (2021–2035)
Market Research Future built the historical series for the North America Pumps Market from manufacturer revenue disclosures, US Census Bureau shipment data, USITC trade statistics [16] and interviews with distributors and utility engineers. Forecast values come from a bottom-up model by application and country, cross-checked against the published capital plans of water utilities, LNG developers and industrial operators. All values are nominal USD Billion at factory-gate prices.



 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA


