In Memory Analytics Market (2026 – 2035)

In Memory Analytics Market Size, Share and Research Report By Deployment (On-Premise and Cloud), By End-User Industry (BFSI, Retail, IT and Telecommunications, Manufacturing, Government and Public Sector, and Other End-User Industries), And By Region (North America, Europe, Asia-Pacific, And Rest Of The World) – Industry Forecast Till 2035
ID: MRFR/ICT/28164-HCR 100 Pages Nirmit Biswas, Aarti Dhapte Last Updated: October 06, 2026
In Memory Analytics Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)17.1%
2025 Market SizeUSD 3.78 Billion
2035 Market SizeUSD 18.33 Billion
Key Players
SAP SE
Oracle Corporation
Microsoft Corporation
IBM Corporation
Amazon Web Services
SAS Institute
Opportunities
  • Memory Pooling Lowers the Cost of Large Workloads
  • Instant-Payment Analytics in Emerging Markets
  • Data Monetization under the EU Data Act

In Memory Analytics Market Summary

The In-Memory Analytics Market was valued at USD 3.78 Billion in 2025 and is forecast to reach USD 4.43 Billion in 2026, expanding to USD 18.33 Billion by 2035 at a CAGR of 17.1% over 2026–2035. Two regulatory catalysts are pulling budgets forward. The EU Data Act became applicable in September 2025, obliging connected-product makers to share usage data on request [5], and the Digital Operational Resilience Act (DORA) has required EU financial entities to monitor and report ICT risk continuously since January 2025 [6]. Both rules reward platforms that can query live operational data in seconds rather than hours.

Enterprises are retiring disk-bound data warehouses, nightly batch ETL jobs, and pre-aggregated OLAP cubes in favor of columnar engines that hold working datasets in DRAM and run transactional and analytical workloads on a single copy of the data. This shift toward in-memory computing rides on the cloud. expects worldwide public cloud end-user spending to reach USD 723.4 Billion in 2025 , and most new analytical deployments now land on managed services billed by consumption rather than on dedicated high-memory servers.

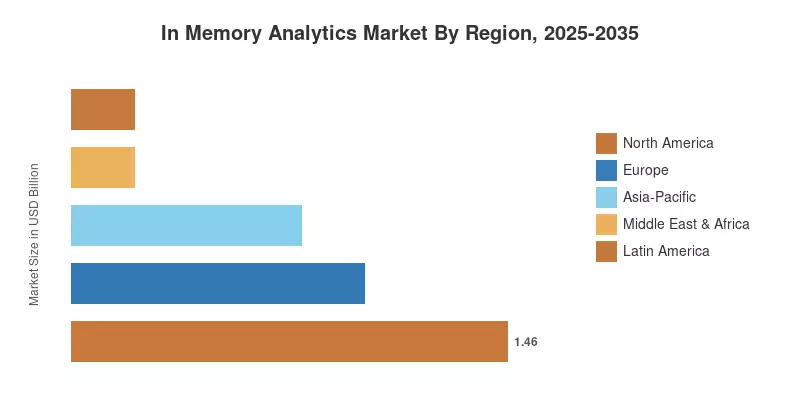
North America holds the largest position with a 38.5% share in 2025, driven by early cloud adoption and heavy BFSI spending. Asia-Pacific is the fastest-growing region at a 20.4% CAGR, powered by instant-payment volumes in India and national AI programs across China, Japan, and ASEAN. Europe ranks second, where data-sharing and resilience mandates are converting compliance obligations into analytics projects. Over the next decade, competitive advantage will shift toward vendors that pair memory-resident speed with governance, cost control, and AI-ready data access.

Key Report Takeaways

• By Deployment

  • On-Premise installations hold 54.0% of the In-Memory Analytics Market in 2025, reflecting banks, insurers, and public agencies that keep sensitive data inside their own data centers
  • Cloud is the fastest-growing deployment mode at a 20.6% CAGR through 2035, as consumption pricing removes the upfront DRAM investment that once deterred mid-sized buyers

• By End-user Industry

  • BFSI is the largest end-user industry with a 27.5% share, using memory-resident engines for fraud scoring, intraday risk, and instant payments
  • IT and Telecommunications generated USD 0.73 Billion in 2025, led by network assurance and subscriber analytics
  • Retail is the fastest-growing industry at a 19.4% CAGR, supported by dynamic pricing and cross-channel inventory visibility

• By Region

  • North America commands a 38.5% share of the In-Memory Analytics Market, anchored by the United States
  • Asia-Pacific posts the highest regional CAGR at 20.4%
  • Europe accounted for USD 0.98 Billion in 2025, with Germany and the United Kingdom as anchor markets

Market Size and Forecast (2021–2035)

Estimates for the In-Memory Analytics Market combine bottom-up mapping of vendor revenue across software licences, subscriptions, and managed services with top-down validation against enterprise analytics and cloud spending data . Historical values for 2021–2024 draw on company filings and interviews with platform vendors, system integrators, and enterprise buyers; 2025 serves as the base year, and 2026–2035 figures reflect scenario-weighted forecasting. Growth spiked in 2023, when generative AI pilots triggered a wave of data-platform modernization, before normalizing in 2024 as buyers shifted from experimentation to production budgets and tightened cloud cost controls.
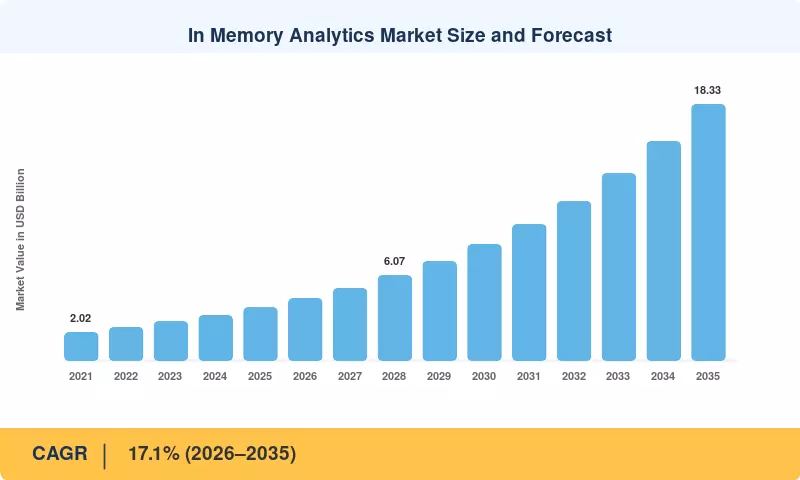
In Memory Analytics Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Data volume growth from connected devices +3.4% Global Long-term
Real-time fraud detection and instant payments +2.9% North America, Asia-Pacific, Europe Short-term
Cloud migration and consumption pricing +2.6% Global Medium-term
Generative AI and HTAP workloads +2.3% North America, Asia-Pacific Medium-term
Memory architecture advances (CXL) +1.7% North America, East Asia Long-term
Data-sharing and resilience regulation +1.4% Europe Short-term
National AI programs in emerging economies +1.5% Asia-Pacific, Latin America, Middle East & Africa Medium-term


Data Volume Growth from Connected Devices

Cisco predicted 1,105 million linked wearable devices by 2022 [2], while Seagate predicted the global datasphere will reach 175 zettabytes by 2025 [1]. Disk-based staging becomes a bottleneck because sensor feeds, clickstreams, and machine logs arrive regularly and lose value in a matter of minutes. Memory-resident engines allow operators to take action while an event is still happening by ingesting and querying these streams on a single platform. Globally applicable, the driver gets stronger as 5G and edge deployments increase the number of data sources.


Real-Time Fraud Detection and Instant Payments

According to the Federal Trade Commission, U.S. customers reported fraud losses of USD 12.5 billion in 2024, a 25% increase over the previous year [10]. In a single month in 2025, the UPI network in India handled over 18 billion transactions [9]. Banks are forced to use memory-resident feature stores and scoring engines because fraud models must score every payment in milliseconds before settlement. This is the fastest-converting driver due to its short payback periods, with expenditure noticeable within two years.


Cloud Migration and Consumption Pricing

Managed in-memory services convert a large capital outlay on high-capacity servers into metered spending, bringing mid-sized enterprises into the buyer pool. According to projections that public cloud end-user spending will climb roughly 21% in 2025 to USD 723.4 Billion , this shows where new analytical workloads are being provisioned. Elastic scaling also lets buyers size memory for quarter-end peaks without paying for idle capacity, a cost profile that on-premises clusters cannot match.

Generative AI and HTAP Workloads

expects worldwide generative AI spending to reach USD 644 Billion in 2025 . Retrieval-augmented generation, vector search, and AI agents all need fresh operational data served at low latency, and hybrid transactional/analytical processing (HTAP) removes the delay of copying data between systems. Oracle's Database 23ai, released in May 2024, added native AI Vector Search to its converged engine [19], turning existing estates into AI data platforms. Impact builds steadily over the next two to four years.

Memory Architecture Advances

The Compute Express Link (CXL) 3.1 specification, released in November 2023, enables memory pooling and sharing across servers [12], cutting the stranded DRAM that inflates deployment costs. The U.S. CHIPS and Science Act allocates USD 52.7 Billion to domestic semiconductor manufacturing and research [7], supporting memory supply resilience. As CXL-attached memory expanders reach volume, buyers can hold larger datasets in memory at a lower cost per gigabyte, extending the economic case to workloads previously left on disk.

Data-Sharing and Resilience Regulation

Regulation (EU) 2023/2854, the Data Act, applies from 12 September 2025 and grants users the right to access data generated by connected products [5]. DORA, in force for 20 types of financial entities since 17 January 2025, requires continuous ICT incident monitoring and reporting [6]. Both rules demand fast, auditable access to operational data. Compliance teams are increasingly funding analytics modernization from regulatory budgets, accelerating purchases that might otherwise slip into later years.

National AI Programs in Emerging Economies

India approved its IndiaAI Mission in March 2024 with an outlay of INR 10,371.92 crore, roughly USD 1.25 Billion [8], while Brazil launched its AI Plan (PBIA) in July 2024 with planned investment of BRL 23 billion [25]. These programs fund compute infrastructure, public data platforms, and workforce skills, widening the base of organizations able to deploy memory-resident analytics. The effect is strongest across Asia-Pacific, Latin America, and the Middle East.

Restraints Impact Analysis


Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
High memory cost and DRAM price volatility −1.7% Global Short-term
Persistent-memory roadmap disruption −0.8% Global Medium-term
Shortage of data engineering skills −1.3% Global Medium-term
Privacy and data-sovereignty compliance costs −1.1% Europe, Asia-Pacific Short-term
Data center power constraints −0.9% North America, Europe Long-term


High Memory Cost and DRAM Price Volatility

For large clusters, memory accounts for the majority of the hardware cost because DRAM is still significantly more expensive per gigabyte than NAND flash. As manufacturers shifted capacity toward high-bandwidth memory for AI accelerators, TrendForce observed double-digit quarterly rises in traditional DRAM contract pricing throughout portions of 2024 [14]. Price fluctuations can cause expansion projects to stall mid-cycle and complicate multi-year planning for on-premises buyers.


Persistent-Memory Roadmap Disruption

In July 2022, Intel stated that its Optane persistent-memory business would wind down [13], eliminating the most commonly used layer between DRAM and flash. Database providers had to re-engineer around CXL, which is still in its infancy, because their engines had been designed for quicker restarts and greater capacity on Optane. In the medium term, buyers have fewer affordable options for very big memory-resident datasets.


Shortage of Data Engineering Skills

Estimates that IT skills shortages could cost organizations up to USD 5.5 trillion by 2026 through delays, quality problems, and lost revenue . Memory-resident platforms demand expertise in data modeling, partitioning, and memory sizing that many enterprises lack. Limited awareness of the technology among small and mid-sized firms compounds the problem, particularly in Latin America and Africa.

Privacy and Data-Sovereignty Compliance Costs

Ireland's Data Protection Commission fined Meta EUR 1.2 billion in May 2023 over EU–US data transfers [16], and India's Digital Personal Data Protection Act 2023 allows penalties up to INR 250 crore per violation category [17]. Holding personal data in memory across regions raises residency and encryption obligations, forcing duplicated infrastructure and longer procurement cycles for multinational buyers.

Data Center Power Constraints

The IEA estimates that data centres consumed about 415 TWh of electricity in 2024 and projects demand to reach roughly 945 TWh by 2030 [11]. Memory-dense servers draw continuous power, and grid connection queues in hubs such as Northern Virginia, Dublin, and Amsterdam are delaying new capacity. Power ceilings can cap how much memory operators add at specific sites.

In Memory Analytics Market Opportunities

Memory Pooling Lowers the Cost of Large Workloads

CXL-based memory pooling lets operators share DRAM across servers instead of overprovisioning each node, a direct answer to the cost restraint described in Section 5.1. Vendors that certify their engines on CXL-attached memory tiers early can win workloads currently parked in disk-based warehouses because they were too large to justify full DRAM residency [12]. Expect the earliest commercial traction among hyperscalers and large banks.

Instant-Payment Analytics in Emerging Markets

India's UPI, Brazil's Pix, and Saudi Arabia's instant-payment rails generate billions of transactions that need fraud screening, credit decisioning, and merchant analytics in milliseconds [9]. Local banks and fintechs often lack mature platforms, creating a sizeable gap for cloud-delivered real-time data analytics priced for high volume and low ticket size. Vendors with local cloud regions and regional language support will be best placed to capture this growth in the In-Memory Analytics Market.

Data Monetization under the EU Data Act

The Data Act's access and sharing rights [5] are spawning data-exchange services, usage-based insurance products, and aftermarket maintenance offerings built on connected-product data. Memory-resident platforms that can meter, anonymize, and serve shared datasets on demand open a data-as-a-service revenue line for manufacturers and platform vendors alike. This new business model could become one of the more distinctive revenue pools in the In-Memory Analytics Market across Europe.

Edge Analytics for Smart Manufacturing

Factories running predictive maintenance and quality inspection need analytics close to the production line, where cloud round-trips are too slow. Compact memory-resident engines deployed on edge servers can process machine telemetry locally and send only aggregates upstream, reducing bandwidth and latency. Programs such as Germany's Industrie 4.0 initiatives and Japan's semiconductor and AI support framework [24] are funding exactly this kind of plant modernization.

Memory Services for AI Agents

AI agents need persistent, low-latency context stores that combine vector, key-value, and relational data. Vendors that package these as metered services, priced per agent session or per retrieval, can tap generative AI budgets rather than traditional analytics budgets . The model favors cloud-native providers and specialist in-memory databases with strong developer ecosystems.

In Memory Analytics Market Future Outlook

Autonomous Analytics and AI Agents

Analytics is moving from dashboards that people read to agents that act. 's forecast of USD 644 Billion in generative AI spending for 2025 signals where enterprise budgets are heading, and agents that approve credit, reroute shipments, or reprice products need consistent, up-to-the-second context. Memory-resident platforms are positioned to become the operational memory layer for these systems, with governance, lineage, and access controls becoming as important as raw speed.

Platform Consolidation and Consumption Economics

Consolidation is redrawing the competitive map. Microsoft made Fabric generally available in November 2023 [20], IBM completed its purchase of StreamSets and webMethods in July 2024 [21], and Salesforce agreed in May 2025 to acquire Informatica for about USD 8 Billion [22]. Buyers increasingly prefer unified platforms priced by consumption, which pressures standalone vendors in the In-Memory Analytics Market to partner, specialize, or sell.

The Memory Hierarchy Supercycle

AI accelerators have turned memory into a strategic resource. High-bandwidth memory, CXL expanders, and pooled architectures [12] are redefining how much data a server can hold close to compute. Public funding, including the USD 52.7 Billion CHIPS and Science Act [7] and Japan's AI and semiconductor framework [24], is expanding supply, which should ease DRAM cost pressure in the second half of the forecast period and broaden the economic case for memory residency.

Energy Efficiency and Sustainability Reporting

Data-centre electricity demand is on course to roughly double by 2030, according to the IEA [11], making power efficiency a purchasing criterion. Memory-resident engines can reduce energy per query by avoiding repeated disk reads, a claim vendors will need to document as the EU's Corporate Sustainability Reporting Directive pushes large buyers to disclose Scope 3 emissions from IT services. Energy-per-query metrics are likely to appear in procurement scorecards before 2030.

Regional Market Share Analysis

Region Key Metric (2025) Primary Investment Themes
North America 38.5% share BFSI fraud analytics, cloud data platforms, AI workloads
Europe USD 0.98 Billion Data Act compliance, DORA resilience, sovereign cloud
Asia-Pacific 20.4% CAGR (2026–2035) Instant payments, national AI programs, manufacturing analytics
Latin America 5.5% share Pix-driven banking analytics, retail modernization
Middle East & Africa USD 0.21 Billion National data strategies, smart government, telecom analytics
Total USD 3.78 Billion —

Regional demand in the In-Memory Analytics Market tracks cloud maturity, payment digitization, and regulatory pressure. North America leads on installed base, Europe on regulation-driven modernization, and Asia-Pacific on growth momentum.


North America

Country Key Metric Key Driver
US 84.0% share of region Hyperscaler ecosystem, BFSI and retail analytics
Canada 17.8% CAGR (2026–2035) Consumer-driven banking framework
Mexico USD 0.08 Billion Nearshoring-led manufacturing analytics


The United States anchors the North American In-Memory Analytics Market, with the deepest pool of cloud providers, platform vendors, and data-intensive financial institutions. The Federal Reserve's FedNow instant-payment service, launched in July 2023, is extending real-time fraud screening beyond the largest banks to community lenders. Canada's consumer-driven banking framework, outlined in Budget 2024, will require secure, fast data access across institutions. In Mexico, nearshoring investment in automotive and electronics plants is creating demand for production-line analytics.

Europe

Country Key Metric Key Driver
Germany 23.5% share of region Industrie 4.0 and automotive analytics
UK USD 0.20 Billion Financial services and Data (Use and Access) Act 2025
France 16.9% CAGR (2026–2035) SecNumCloud sovereign cloud adoption
Italy 8.5% share of region Banking modernization
Spain USD 0.06 Billion Retail and tourism analytics
Nordic Countries 18.6% CAGR (2026–2035) Cloud-first public sector
Russia 3.0% share of region Domestic software substitution
Rest of Europe USD 0.15 Billion EU digital funding programs


European demand in the In-Memory Analytics Market is shaped more by regulation than by any other factor. DORA [6] and the Data Act [5] both require fast, auditable access to operational data, and banks across Germany, Italy, and the Nordics are modernizing risk platforms accordingly. France's SecNumCloud certification steers public and critical-sector buyers toward sovereign-hosted services. The UK's Data (Use and Access) Act 2025 extends smart-data schemes beyond open banking. Russia continues to replace departed Western platforms with domestic alternatives, limiting its addressable share for global vendors.

Asia-Pacific

Country Key Metric Key Driver
China 36.0% share of region East Data, West Computing infrastructure program
India 23.8% CAGR (2026–2035) UPI transaction growth, IndiaAI Mission
Japan USD 0.17 Billion AI and semiconductor support framework
South Korea 8.0% share of region Telecom and electronics analytics
ASEAN 22.1% CAGR (2026–2035) Digital banking licences, e-commerce growth
Rest of Asia-Pacific USD 0.08 Billion Cloud region expansion


Asia-Pacific is the fastest-growing region in the In-Memory Analytics Market. China's East Data, West Computing program links eight national computing hubs with ten data-center clusters, expanding domestic capacity for memory-intensive workloads. India combines record UPI volumes [9] with the IndiaAI Mission [8], while the DPDP Act [17] encourages in-country deployments. Japan's framework of roughly JPY 10 trillion in AI and semiconductor support through 2030 [24] underwrites enterprise modernization. Digital-bank licensing across Singapore, Malaysia, and the Philippines is adding a new cohort of cloud-native buyers in ASEAN.

Latin America

Country Key Metric Key Driver
Brazil 46.0% share of region Pix instant payments, Brazilian AI Plan
Argentina 15.9% CAGR (2026–2035) Fintech expansion
Rest of Latin America USD 0.08 Billion Retail and telecom modernization


Brazil dominates the Latin American In-Memory Analytics Market, driven by the Central Bank's Pix instant-payment system and the BRL 23 billion Brazilian AI Plan [25]. Banks and retailers use memory-resident analytics for real-time credit, fraud, and promotion decisions, and Brazil's LGPD privacy law favors locally hosted cloud regions. Argentina's fintech sector is growing quickly despite macroeconomic volatility, while Colombia, Chile, and Peru account for most of the remaining regional demand.

Middle East & Africa

Country Key Metric Key Driver
Saudi Arabia 21.5% CAGR (2026–2035) Vision 2030 and national data strategy
UAE 24.0% share of region National AI Strategy 2031, smart government
South Africa USD 0.04 Billion Banking and telecom analytics
Egypt 18.2% CAGR (2026–2035) Digital Egypt program
Rest of MEA 22.0% share of region Mobile money and telecom growth


Gulf states lead the Middle East & Africa in the Memory Analytics Market. Saudi Arabia's Vision 2030 and the national data and AI strategy managed by SDAIA are funding government data platforms and new hyperscale cloud regions. The UAE's National AI Strategy 2031 supports smart-government and smart-city analytics in Dubai and Abu Dhabi. South Africa's banks and telecom operators remain the largest buyers south of the Sahara, while mobile-money growth across East and West Africa is creating early demand for transaction analytics.

In Memory Analytics Market By Region, 2025-2035

In Memory Analytics Market Segmentation


By Deployment

Segment Key Metric Primary Demand Driver
On-Premise 54.0% share (2025) Data sovereignty and latency control in BFSI and government
Cloud 20.6% CAGR (2026–2035) Consumption pricing and managed services


On-Premise deployment leads with a 54.0% share, reflecting decades of investment in high-memory servers by banks, insurers, and public agencies that must keep regulated data under direct control. Cloud deployment is the fastest-growing mode at a 20.6% CAGR, as managed services eliminate upfront DRAM purchases and allow capacity to scale with demand. Hybrid patterns, with sensitive data on-premises and burst workloads in the cloud, are becoming the default architecture across the In-Memory Analytics Market.

By End-user Industry

Segment Key Metric Primary Demand Driver
BFSI 27.5% share (2025) Fraud scoring, intraday risk, instant payments
Retail 19.4% CAGR (2026–2035) Dynamic pricing and omnichannel inventory
IT and Telecommunications USD 0.73 Billion (2025) Network assurance and subscriber analytics
Manufacturing 13.0% share (2025) Predictive maintenance and quality analytics
Government and Public Sector 16.2% CAGR (2026–2035) Smart government and tax analytics
Other End-user Industries USD 0.53 Billion (2025) Healthcare, energy, and logistics use cases


BFSI is the largest end-user industry with a 27.5% share, as millisecond fraud scoring and DORA-driven risk monitoring make memory residency a necessity rather than an upgrade. Retail is the fastest-growing industry at a 19.4% CAGR, where dynamic pricing and real-time inventory visibility across stores and e-commerce channels deliver measurable margin gains. IT and Telecommunications, Manufacturing, and Government and Public Sector form a strong middle tier, each tied to network, factory, or citizen-service modernization.

Competitive Benchmarking

Competition in the In-Memory Analytics Market is moderately fragmented. Market Research Future estimates an HHI of roughly 750–850 and a combined top-five share of about 45–55%, indicating low concentration. Large platform vendors compete on installed base and ecosystem breadth, hyperscalers on managed-service convenience, and specialists on raw performance and price.

Company Est. Revenue Share Range Key Offerings for In-Memory Analytics Market Strategic Positioning
SAP SE ~14–18% SAP HANA Cloud, SAP Datasphere, SAP Business Data Cloud Installed-base leader tying analytics to ERP data
Oracle Corporation ~10–13% Oracle Database In-Memory, HeatWave, Oracle Database 23ai Converged database with embedded vector search
Microsoft Corporation ~8–11% Microsoft Fabric, Power BI, SQL Server In-Memory OLTP Unified SaaS analytics bundled with Azure
IBM Corporation ~5–8% Db2 BLU Acceleration, watsonx.Data, Cognos Analytics Hybrid-cloud governance for regulated industries
Amazon Web Services ~5–8% Amazon MemoryDB, Amazon ElastiCache, Amazon Redshift Hyperscale managed services with consumption pricing
SAS Institute ~4–6% SAS Viya with Cloud Analytic Services engine Advanced analytics and model risk management
Teradata ~3–5% Teradata VantageCloud Enterprise-scale hybrid analytics
Strategy (formerly MicroStrategy) ~2–4% Strategy One, in-memory intelligent cubes Semantic layer and AI-assisted BI
Qlik ~2–4% Qlik Sense associative engine, Qlik Talend Cloud Associative analytics plus data integration
Software AG ~1–3% Terracotta, Adabas In-memory data management for core systems
Exasol ~1–2% Exasol Analytics Engine High-performance MPP analytics database
Kognitio ~0.5–1.5% Kognitio analytical platform Niche high-concurrency SQL analytics


Recent News & Developments

  • Microsoft (November 2023): Made Microsoft Fabric generally available, unifying data engineering, warehousing, and Power BI on one SaaS platform and raising the bar for integrated analytics stacks [20]
  • European Union (January 2024): The Data Act entered into force, with obligations applying from September 2025, creating new demand for systems that serve connected-product data on request [5]
  • Oracle (May 2024): Released Oracle Database 23ai with native AI Vector Search, merging AI retrieval with memory-optimized analytics in one engine [19]
  • IBM (July 2024): Completed its acquisition of StreamSets and webMethods from Software AG, strengthening real-time data integration for hybrid-cloud analytics [21]
  • SAP (February 2025): Launched SAP Business Data Cloud in partnership with Databricks, extending HANA-based analytics with open data-sharing for AI workloads [18]
  • Strategy (February 2025): MicroStrategy rebranded as Strategy, refocusing its BI portfolio on AI-assisted analytics and a universal semantic layer
  • Redis (May 2025): Released Redis 8 with an AGPL licensing option, reversing part of its 2024 move to source-available terms and reassuring open-source adopters [23]
  • Salesforce (May 2025): Agreed to acquire Informatica for about USD 8 Billion to strengthen data management beneath its analytics and AI agent offerings [22]

In Memory Analytics Market Report Scope

Parameter Details
Market Scope In-Memory Analytics Market software and services, segmented by Deployment, End-user Industry, and Geography
Study Period 2021–2035 (Historical: 2021–2024; Base Year: 2025; Forecast: 2026–2035)
CAGR 17.1% (2026–2035)
Market Size checkpoints USD 3.78 Billion (2025); USD 4.43 Billion (2026); USD 8.32 Billion (2030); USD 18.33 Billion (2035)
Fastest Growing Segments Cloud (Deployment); Retail (End-user Industry); Asia-Pacific (Region)
Companies Profiled SAP SE, Oracle, Microsoft, IBM, Amazon Web Services, SAS Institute, Teradata, Strategy, Qlik, Software AG, Exasol, Kognitio
Valuation Currency USD Billion
CAGR Driver Disclaimer Driver and restraint impacts are directional, overlapping estimates and are not additive to the headline CAGR

FAQs

How should buyers compare memory-resident platforms with disk-based cloud warehouses?
Benchmark concurrency and latency on your own production workload rather than vendor-published tests. Memory-resident engines win on sub-second queries over hot data, while disk-based warehouses stay cheaper for petabyte-scale history, so most enterprises run both in tiers.
What licensing risks should In-Memory Analytics Market buyers watch?
Open-source licence changes can reset total cost of ownership with little notice. Redis moved to source-available terms in March 2024, then restored an AGPL option with Redis 8 in May 2025 [23]. Contracts should fix pricing and include exit rights.
How does CXL change hardware planning for In Memory Analytics Market deployments?
CXL lets servers draw on pooled memory across a rack, so capacity no longer has to be sized node by node. Buyers can defer DRAM purchases and raise utilization, although database support for tiered memory is still uneven [12].
Which emerging use cases are drawing new In Memory Analytics Market investment?
Retrieval for AI agents, telecom network-slice assurance, and grid-edge telemetry are the newest demand pockets in the In-Memory Analytics Market. Each requires millisecond responses on constantly changing data, which batch pipelines cannot deliver.
What integration problems most often delay go-live?
Legacy ETL jobs, inconsistent master data, and missing change-data-capture feeds are the usual bottlenecks. Projects that begin with a governed semantic layer generally reach production faster than those migrating raw tables first.
How do data-residency rules shape architecture decisions?
Residency laws push deployments toward sovereign-cloud regions and locally held encryption keys. India's DPDP Act permits penalties up to INR 250 crore per breach category [17], so multinationals increasingly run separate memory-resident nodes inside each jurisdiction.
What metrics matter when evaluating vendors in the In-Memory Analytics Market for investment?
Net revenue retention and the share of consumption-based revenue best signal durable demand. Investors should also weigh dependence on hyperscaler marketplaces, which increasingly control how enterprises procure new data software.
Author
Author Author Profile Nirmit Biswas LinkedIn Senior Research Analyst
With 5+ years of expertise in Market Intelligence and Strategic Research, Nirmit Biswas specializes in ICT, Semiconductors, and BFSI. Backed by an MBA in Financial Services and a Computer Science foundation, Nirmit blends technical depth with business acumen. He has successfully led 100+ projects for global enterprises and startups, including Amazon, Cisco, L&T and Huawei, delivering market estimations, competitive benchmarking, and GTM strategies. His focus lies in transforming complex data into clear, actionable insights that drive growth, innovation, and investment decisions. Recognized for bridging engineering innovation with executive strategy, Nirmit helps businesses navigate dynamic markets with confidence.
Co-Author Co-Author Profile Aarti Dhapte LinkedIn AVP - Research
A consulting professional focused on helping businesses navigate complex markets through structured research and strategic insights. I partner with clients to solve high-impact business problems across market entry strategy, competitive intelligence, and opportunity assessment. Over the course of my experience, I have led and contributed to 100+ market research and consulting engagements, delivering insights across multiple industries and geographies, and supporting strategic decisions linked to $500M+ market opportunities. My core expertise lies in building robust market sizing, forecasting, and commercial models (top-down and bottom-up), alongside deep-dive competitive and industry analysis. I have played a key role in shaping go-to-market strategies, investment cases, and growth roadmaps, enabling clients to make confident, data-backed decisions in dynamic markets.
Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Global Diameter Signaling Market
Case Study
Information and Communications Technology
Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.



















