Hemorrhoids Treatment Market

Hemorrhoids Treatment Market research report, by Treatment type (drugs, non-surgical procedures, surgical procedures), Route of administration (oral, topical agents) Distribution channel (retail pharmacies) &Forecast till 2035
ID: MRFR/Pharma/5534-HCR 90 Pages Rahul Gotadki Last Updated: September 15, 2026
Hemorrhoids Treatment Market
Market Size
Forecast Period2025 - 2035
CAGR (2025 - 2035)6.83%
2024 Market Size$ 1,441.59 Million
2025 Market Size$ 1,556.57 Million
2035 Market Size$ 2,994.6 Million
Key Players
Companies such as Johnson & Johnson
Bayer AG
Medtronic
Stryker Corporation
Boston Scientific
Hollister Incorporated
Opportunities
  • Market Growth Projections
  • Growing Geriatric Population
  • Rising Prevalence of Hemorrhoids

Hemorrhoids Treatment Market Summary

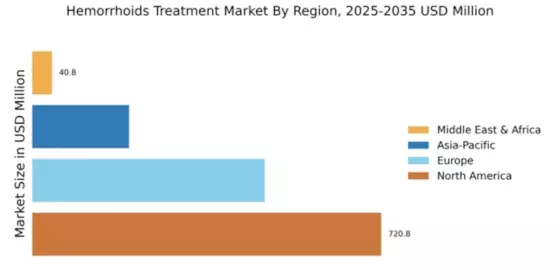
Global Hemorrhoids Treatment Market Size was valued at USD 1,441.59 Million in 2024 & the market is projected to grow from USD 1,556.57 Million in 2025 to USD 2,994.6 Million by 2035, registering a CAGR of 6.83% during the forecast period 2025–2035. North America led the market with over 50% share, generating around USD 720.8 Million in revenue.
 
The increasing prevalence of hemorrhoids driven by sedentary lifestyles, poor dietary habits, and aging populations is a major growth factor for the Hemorrhoids Treatment Market. Rising awareness of available treatment options and improved access to minimally invasive therapies are further supporting market expansion.
 
According to the World Health Organization (WHO), the global population aged 60 years and older is projected to increase from 1 billion in 2020 to 1.4 billion by 2030, significantly expanding the patient population susceptible to hemorrhoidal disorders and related gastrointestinal conditions.

Key Market Trends & Highlights

The Hemorrhoids Treatment Market is experiencing notable growth driven by increasing awareness and technological advancements.

  • North America dominates with over 50% share driven by advanced healthcare systems and strong adoption of innovative treatments.
  • Europe holds 33.30% share with USD 480 million market size supported by healthcare investment and patient-centered treatment approaches.
  • Aging population expected to exceed 1.6 billion by 2050 (UNFPA), significantly increasing demand for gastrointestinal and hemorrhoid treatments.
  • Technological advancements in minimally invasive procedures are improving patient outcomes and accelerating adoption of advanced hemorrhoids treatment solutions globally.

Market Size & Forecast

2024 Market Size 1441.59 (USD Million)
2035 Market Size 2994.6 (USD Million)
CAGR (2025 - 2035) 6.83%

Major Players

Companies such as Johnson & Johnson (US), Bayer AG (DE), Medtronic (US), Stryker Corporation (US), Boston Scientific (US), Hollister Incorporated (US), Coloplast A/S (DK), Smith & Nephew (GB), 3M Company (US) are some of the major participants in the global market.

Hemorrhoids Treatment Market Drivers

Market Growth Projections

The Global Hemorrhoids Treatment Market is poised for substantial growth, with projections indicating a market value of 8.9 USD Billion in 2024 and an anticipated increase to 11.6 USD Billion by 2035. 
 
  • According to the World Bank, global health expenditure exceeds USD 9 trillion annually, reflecting sustained investment in healthcare services and treatment accessibility. Growing healthcare spending supports continued adoption of advanced hemorrhoid management solutions and encourages innovation across pharmaceutical and procedural treatment options.

Growing Geriatric Population

The aging population worldwide is a critical factor influencing the Global Hemorrhoids Treatment Market. Older adults are more susceptible to developing hemorrhoids due to factors such as decreased mobility and changes in dietary habits. 
 
  • According to IHME, global life expectancy has increased significantly over recent decades, contributing to a rapidly expanding elderly population. As age-related gastrointestinal disorders become more prevalent, demand for effective hemorrhoid treatment solutions is expected to increase steadily across healthcare systems.

Rising Prevalence of Hemorrhoids

The Global Hemorrhoids Treatment Market experiences growth driven by the increasing prevalence of hemorrhoids among the population. Factors such as sedentary lifestyles, poor dietary habits, and an aging population contribute to this rise. It is estimated that approximately 50% of adults will experience hemorrhoids by the age of 50. 
 
  • According to PubMed, hemorrhoids affect nearly 50% of individuals by the age of 50, highlighting a substantial patient population requiring medical management. This high prevalence continues to support demand for pharmaceutical products, minimally invasive procedures, and advanced treatment options.

Advancements in Treatment Options

Innovations in medical technology and treatment methodologies are propelling the Global Hemorrhoids Treatment Market forward. New minimally invasive procedures, such as rubber band ligation and infrared coagulation, offer patients effective alternatives to traditional surgical methods. 
 
  • According to PubMed, minimally invasive hemorrhoid procedures have demonstrated shorter recovery periods and reduced postoperative discomfort compared with traditional surgical interventions. These advancements are encouraging wider treatment adoption and improving patient outcomes across clinical settings.

Increased Awareness and Education

Heightened awareness regarding hemorrhoids and their treatment options is a significant driver for the Global Hemorrhoids Treatment Market. Public health campaigns and educational initiatives aim to destigmatize the condition, encouraging individuals to seek medical advice. This shift in perception is crucial, as many patients delay treatment due to embarrassment. 
 
  • According to the World Bank, internet usage exceeds 67% of the global population, increasing access to health information and educational resources. Greater awareness of symptoms, treatment options, and preventive measures is encouraging earlier intervention and supporting treatment market growth.

Regulatory Support and Reimbursement Policies

Supportive regulatory frameworks and favorable reimbursement policies are essential drivers for the Global Hemorrhoids Treatment Market. Governments and health organizations are increasingly recognizing the importance of treating hemorrhoids, leading to improved access to care. 
 
  • According to IHME, healthcare spending continues to rise globally as governments expand access to medical services and treatment coverage. Supportive reimbursement policies and healthcare investments are improving patient access to hemorrhoid treatments and encouraging adoption of innovative therapies.

Market Segment Insights

By Treatment Type: Topical Treatments (Largest) vs. Minimally Invasive Procedures (Fastest-Growing)

The market exhibits a diverse distribution of treatment types, with topical treatments holding the largest share in the Hemorrhoids Treatment Market at 44%. This segment remains a preferred choice among patients due to its ease of use and immediate effects. Conversely, minimally invasive procedures are capturing attention as the fastest-growing segment, driven by advancements in technology and patient preferences for less invasive options. Oral medications and surgical procedures also contribute to the market, yet their share is overshadowed by the prominence of topical solutions and the emerging trend of minimally invasive techniques.

Johnson & Johnson generated approximately USD 88.8 billion in annual revenue and continues supporting consumer healthcare innovations. The widespread availability, convenience, and affordability of topical therapies continue to make them the preferred treatment option for patients managing mild to moderate hemorrhoidal symptoms.

By Severity Level: Moderate (Largest) vs. Severe (Fastest-Growing)

The distribution of market share among severity levels reveals that moderate hemorrhoids treatment is the largest segment in the Hemorrhoids Treatment Market, with a 48% share. This is primarily due to the high prevalence of mild to moderate cases among the population, prompting a steady demand for effective treatment options. Conversely, the severe segment, although currently smaller, is gaining traction as awareness about effective treatments increases, particularly through minimally invasive procedures and advanced pharmacological solutions. Growth trends indicate that the mild and moderate segments are driven by a general rise in awareness and proactive health measures among patients, as well as the growing availability of over-the-counter remedies. The severe segment, recognized as the fastest-growing, is seeing an uptick due to a combination of factors including an aging population, the prevalent shift towards surgical interventions, and improvements in treatment options that make managing severe cases more feasible.

Bayer AG reported approximately EUR 47.6 billion in annual revenue, supported by a broad healthcare portfolio. The high prevalence of moderate hemorrhoidal conditions and growing awareness regarding early treatment continue to drive substantial demand for effective pharmaceutical and non-surgical management solutions.

By Patient Demographics: Adults (Largest) vs. Elderly (Fastest-Growing)

In the Hemorrhoids Treatment Market, adults represent the largest demographic segment, with a 58% share, accounting for the majority of diagnoses and treatment requirements.This population faces various lifestyle-induced conditions leading to hemorrhoids, with many seeking effective relief methods. On the other hand, the elderly demographic is emerging rapidly due to age-related health issues that increase susceptibility to hemorrhoids, thus driving their market share up significantly. The growth trends within these demographics show a robust increase in product innovations targeted at the elderly, as healthcare providers emphasize tailored treatment options. Additionally, rising awareness about gastrointestinal health and preventive care among older adults is contributing to this segment's burgeoning prominence. Meanwhile, the adult segment continues to be influenced by lifestyle changes, ensuring consistent demand for hemorrhoid treatments throughout this segment.

Adults (Dominant) vs. Elderly (Emerging)

The adult segment is positioned as the dominant force within the market, primarily due to lifestyle factors such as diet, sedentary behavior, and stress that contribute to the prevalence of hemorrhoidal issues in this demographic. Adults often seek medical advice for treatment, creating a steady demand for solutions ranging from over-the-counter products to surgical interventions. Conversely, the elderly segment is emerging as a significant player, influenced by the aging population's increasing health challenges. The susceptibility of older individuals to hemorrhoids, coupled with their growing reliance on healthcare services, enhances their importance in the market. Both segments necessitate differentiated marketing strategies that cater to their unique needs, propelling innovation across treatment options.

By Distribution Channel: Pharmacies (Largest) vs. Online Retail (Fastest-Growing)

In the Hemorrhoids Treatment Market, the distribution of treatment options across various channels shows that pharmacies dominate the landscape, accounting for a significant share of consumer purchases. Pharmacies are preferred by many due to their accessibility and the assurance of pharmaceutical guidance from qualified staff, which fosters consumer trust compared to other channels. Online retail, while initially slower to gain traction, has rapidly become a competitive alternative, particularly appealing to younger demographic segments who favor the convenience and discretion of online purchasing. The growth trends observed in this segment are driven by increasing digital penetration, with more consumers turning to online platforms for their health and wellness needs. Furthermore, the evolving landscape of e-commerce and changes in consumer behavior have made online retail a key player in the market, expected to outpace traditional methods. Hospitals and clinics also contribute to the distribution, but their roles are more focused on extensive care rather than continuous treatment, making them less prominent in this segment overall.

Pharmacies (Dominant) vs. Online Retail (Emerging)

Pharmacies are the dominant distribution channel in the market, largely because they offer a reliable and familiar purchasing experience for consumers. Many patients prefer visiting a pharmacy for advice on treatments, as pharmacists can provide tailored recommendations based on individual needs. In contrast, online retail has emerged as a significant challenger, gaining traction among tech-savvy consumers looking for privacy and convenience. Online platforms often offer wider selections and competitive pricing, appealing to those who may feel uncomfortable discussing their condition in person. As both channels evolve, pharmacies may maintain their stronghold through personalized service, while online retail continues to innovate with user-friendly experiences that cater to the growing demand for accessible health solutions.

Get more detailed insights about Hemorrhoids Treatment Market

Regional Insights

North America : Market Leader in Treatment

North America leads in the Hemorrhoids Treatment Market size, accounting for over 50% of the global revenue in 2024. The region's growth is driven by increasing awareness of treatment options, a rise in the aging population, and advancements in minimally invasive procedures. Regulatory support for innovative therapies further fuels market expansion, making it a hub for medical technology and healthcare innovation.

  • According to CDC data, approximately 129 million Americans live with at least one major chronic disease, increasing healthcare utilization and demand for gastrointestinal treatment services, including management solutions for hemorrhoidal conditions.

The competitive landscape in North America is robust, featuring key players such as Johnson & Johnson, Medtronic, and Boston Scientific. These companies are at the forefront of developing advanced treatment solutions, including surgical and non-surgical options. The U.S. remains the largest market, supported by a well-established healthcare infrastructure and a high prevalence of hemorrhoid cases, ensuring sustained demand for effective treatments.

  • GE Healthcare reported approximately USD 19.7 billion in annual revenue, reflecting continued investment in healthcare technologies and clinical innovation. Advanced healthcare infrastructure and strong medical technology adoption continue to support treatment accessibility and market growth across North America.

Europe : Emerging Market Dynamics

Europe Hemorrhoids Treatment Market size was valued at USD 480 million in 2024, making it the second-largest regional market with a 33.30% share, driven by increasing healthcare expenditure and a growing focus on patient-centered care. The region benefits from stringent regulatory frameworks that promote the adoption of innovative treatment options. Additionally, rising awareness about hemorrhoid conditions and available treatments is expected to boost demand across various European countries. 

  • According to the European Medicines Agency (EMA), the European Union serves a healthcare ecosystem supporting more than 448 million people under comprehensive regulatory frameworks. Strong emphasis on treatment quality, patient safety, and healthcare accessibility continues to encourage adoption of advanced hemorrhoid treatment options throughout Europe.

Leading countries in this market include Germany, France, and the UK, where healthcare systems are increasingly integrating advanced treatment modalities. Key players like Bayer AG and Coloplast A/S are actively involved in expanding their product portfolios to cater to the growing demand. The competitive landscape is characterized by collaborations and partnerships aimed at enhancing treatment efficacy and patient outcomes.

Asia-Pacific : Rapid Growth Potential

The Asia-Pacific region is experiencing significant growth in the hemorrhoids treatment market, projected to reach $200.0 million by 2025. Factors contributing to this growth include increasing urbanization, changing lifestyles, and a rising prevalence of hemorrhoid conditions. Additionally, government initiatives aimed at improving healthcare access and affordability are expected to drive demand for effective treatment options across the region.

Countries like China and India are leading the market, supported by a large population base and increasing healthcare investments. The competitive landscape features both local and international players, including Medtronic and Stryker Corporation, who are focusing on expanding their presence through innovative product offerings and strategic partnerships. This dynamic environment presents ample opportunities for growth and development in the region.

Middle East and Africa : Untapped Market Opportunities

The Middle East and Africa (MEA) region, with a market size of $40.79 million, is gradually emerging in the hemorrhoids treatment landscape. The growth is driven by increasing healthcare investments and a rising awareness of treatment options among the population. Additionally, government initiatives aimed at improving healthcare infrastructure are expected to enhance access to effective treatments, thereby boosting market growth.

Countries such as South Africa and the UAE are at the forefront of this emerging market, with a growing number of healthcare facilities offering specialized treatments. The competitive landscape is characterized by the presence of both local and international players, including Hollister Incorporated and Smith & Nephew, who are working to expand their market share through innovative solutions and strategic collaborations.
Hemorrhoids Treatment Market Regional Image

Key Players and Competitive Insights

The Hemorrhoids Treatment Market is characterized by a competitive landscape that is increasingly shaped by innovation, strategic partnerships, and a focus on patient-centric solutions. Key players such as Johnson & Johnson (US), Bayer AG (DE), and Medtronic (US) are actively pursuing strategies that enhance their market positioning. Johnson & Johnson (US) emphasizes innovation in minimally invasive surgical techniques, while Bayer AG (DE) focuses on expanding its product portfolio through strategic acquisitions. Medtronic (US) is leveraging its expertise in medical devices to develop advanced treatment options, thereby contributing to a dynamic competitive environment that prioritizes technological advancement and patient outcomes.
 
In terms of business tactics, companies are increasingly localizing manufacturing to reduce costs and enhance supply chain efficiency. The market structure appears moderately fragmented, with several players vying for market share. This fragmentation is influenced by the diverse range of treatment options available, from over-the-counter medications to surgical interventions. The collective influence of these key players fosters a competitive atmosphere where innovation and operational efficiency are paramount. 
 
In November 2025, Johnson & Johnson (US) announced the launch of a new line of minimally invasive hemorrhoid treatment devices, which is expected to significantly enhance patient recovery times and reduce hospital stays. This strategic move not only reinforces the company's commitment to innovation but also positions it favorably against competitors by addressing the growing demand for less invasive treatment options. The introduction of these devices could potentially reshape patient preferences and treatment protocols in the market. 
 
In October 2025, Bayer AG (DE) completed the acquisition of a leading digital health platform focused on gastrointestinal disorders, which includes hemorrhoid treatments. This acquisition is strategically important as it allows Bayer to integrate digital health solutions into its product offerings, thereby enhancing patient engagement and adherence to treatment regimens. The move signifies a broader trend towards digitalization in healthcare, which is likely to influence treatment outcomes and patient satisfaction. 
 
In September 2025, Medtronic (US) launched a new AI-driven analytics tool designed to optimize treatment plans for patients suffering from hemorrhoids. This tool utilizes machine learning algorithms to analyze patient data and recommend personalized treatment options. The introduction of AI in treatment planning reflects a significant shift towards data-driven healthcare solutions, which may improve clinical outcomes and operational efficiencies in the long run. 
 
As of December 2025, the competitive trends in the Hemorrhoids Treatment Market are increasingly defined by digitalization, sustainability, and the integration of advanced technologies such as AI. Strategic alliances among key players are shaping the landscape, fostering innovation and enhancing product offerings. The market appears to be transitioning from a focus on price-based competition to one that emphasizes technological advancement, supply chain reliability, and patient-centric solutions. This evolution suggests that companies that prioritize innovation and operational excellence are likely to gain a competitive edge in the future.

Key Companies in the Hemorrhoids Treatment Market include

Recent Industry Developments

  • New OTC/Self-Care Products: The stigma-busting start-up Norms Hemorrhoid Relief debuted in September 2025 with a line of maximum-strength, FDA-compliant OTC products (creams, sprays, wipes) aimed at normalizing the conversation around hemorrhoids and encouraging early treatment
  • Haleon plc (June 2025) completed the acquisition of the remaining equity in its China-based OTC joint venture, Tianjin TSKF Pharmaceutical Co. Ltd (TSKF).
  • Karo Healthcare (March 2024) acquired the global rights to the OTC hemorrhoid brand Proctosedyl from Bayer in Italy, strengthening its digestive health portfolio
  • In June 2020, developeration AB, the Swedish medical company, developed an innovative solution to tackle hemorrhoids less painfully. PexyEazy enables surgical treatment without the need for anaesthesia and within 40 % less time.
  • In February 2022, the State Scientific Centre of Coloproctology, Russian Federation did a clinical experiment on the use of a 1940 nm laser method to treat hemorrhoids, which will lead the future product pipeline expansion.
  • In January 2022, Cook Medical launched a medical device manufacturing facility in Indianapolis, which will cater to the need for external hemorrhoids treatment and hemorrhoids self-care initiatives.

Future Outlook

Hemorrhoids Treatment Market Future Outlook

The Hemorrhoids Treatment Market size is projected to reach USD 2994.6 Million by 2035, growing at a CAGR of 6.83%, driven by increasing awareness, innovative treatments, and rising healthcare expenditures.

New opportunities lie in:

  • Development of telehealth platforms for remote consultations and follow-ups. Investment in biodegradable hemorrhoid treatment products to meet eco-friendly demands. Expansion of over-the-counter product lines targeting specific demographics.

By 2035, the Hemorrhoids Treatment Market is expected to achieve substantial growth and innovation.

Market Segmentation

Hemorrhoids Treatment Market Severity Level Outlook

  • Mild
  • Moderate
  • Severe

Hemorrhoids Treatment Market Treatment Type Outlook

  • Topical Treatments
  • Oral Medications
  • Minimally Invasive Procedures
  • Surgical Procedures

Hemorrhoids Treatment Market Distribution Channel Outlook

  • Pharmacies
  • Online Retail
  • Hospitals
  • Clinics

Hemorrhoids Treatment Market Patient Demographics Outlook

  • Adults
  • Elderly
  • Pregnant Women
  • Children

Report Scope

MARKET SIZE 2024 1441.59(USD Million)
MARKET SIZE 2025 1556.57(USD Million)
MARKET SIZE 2035 2994.6(USD Million)
COMPOUND ANNUAL GROWTH RATE (CAGR) 6.83% (2025 - 2035)
REPORT COVERAGE Revenue Forecast, Competitive Landscape, Growth Factors, and Trends
BASE YEAR 2024
Market Forecast Period 2025 - 2035
Historical Data 2019 - 2024
Market Forecast Units USD Million
Key Companies Profiled Johnson & Johnson (US), Bayer AG (DE), Medtronic (US), Stryker Corporation (US), Boston Scientific (US), Hollister Incorporated (US), Coloplast A/S (DK), Smith & Nephew (GB), 3M Company (US)
Segments Covered Treatment Type, Severity Level, Patient Demographics, Distribution Channel
Key Market Opportunities Integration of telehealth services enhances access to the market solutions.
Key Market Dynamics Rising demand for minimally invasive procedures drives innovation and competition in the market.
Countries Covered North America, Europe, APAC, South America, MEA

Frequently Asked Questions

What is the projected market valuation of the Hemorrhoids Treatment Market by 2035?

The projected market valuation for the Hemorrhoids Treatment Market is 2994.6 USD Million by 2035.

What was the market valuation of the market in 2024?
The overall market valuation of the market was 1441.59 USD Million in 2024.
What is the expected CAGR for the Hemorrhoids Treatment Market during the forecast period 2025 - 2035?

The expected CAGR for the Hemorrhoids Treatment Market during the forecast period 2025 - 2035 is 6.83%.

Which treatment type segment had the highest valuation in 2024?

The Minimally Invasive Procedures segment had the highest valuation at 450.0 USD Million in 2024.

How do the valuations of oral medications compare to topical treatments in 2024?
In 2024, oral medications were valued at 250.0 USD Million, whereas topical treatments were valued at 300.0 USD Million.
What demographic segment is expected to have the highest market valuation by 2035?
The Adults demographic segment is expected to have the highest market valuation, projected at 1200.0 USD Million by 2035.
Which distribution channel is anticipated to dominate the Hemorrhoids Treatment Market by 2035?
Pharmacies are anticipated to dominate the Hemorrhoids Treatment Market, with a projected valuation of 1200.0 USD Million by 2035.
What was the valuation of surgical procedures in 2024?
The valuation of surgical procedures in 2024 was 441.59 USD Million.
Which key players are leading the Hemorrhoids Treatment Market?
Key players in the Hemorrhoids Treatment Market include Johnson & Johnson, Bayer AG, and Medtronic.
What is the projected valuation for the severe severity level segment by 2035?
The projected valuation for the severe severity level segment is 594.6 USD Million by 2035.
Author
Author Author Profile Rahul Gotadki LinkedIn Research Manager
He holds an experience of about 9+ years in Market Research and Business Consulting, working under the spectrum of Life Sciences and Healthcare domains. Rahul conceptualizes and implements a scalable business strategy and provides strategic leadership to the clients. His expertise lies in market estimation, competitive intelligence, pipeline analysis, customer assessment, etc.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of regulatory databases, peer-reviewed medical journals, clinical publications, and authoritative health organizations. Key sources included the US Food & Drug Administration (FDA), European Medicines Agency (EMA), Centers for Disease Control and Prevention (CDC), National Institutes of Health (NIH), National Center for Biotechnology Information (NCBI/PubMed), World Health Organization (WHO) Global Health Observatory, European Centre for Disease Prevention and Control (ECDC), Pan American Health Organization (PAHO), United Nations Population Fund (UNFPA), American Society of Colon and Rectal Surgeons (ASCRS), American Gastroenterological Association (AGA), Society for Surgery of the Alimentary Tract (SSAT), European Society of Coloproctology (ESCP), National Institute of Diabetes and Digestive and Kidney Diseases (NIDDK), Agency for Healthcare Research and Quality (AHRQ), EU Eurostat Health Database, OECD Health Statistics, and national health ministry reports from key markets (U.S. Department of Health & Human Services, NHS England, German Federal Ministry of Health, Japan Ministry of Health, Labour and Welfare). These sources were used to collect disease prevalence statistics, regulatory approval data, clinical safety studies, demographic trends, procedure volume analysis, and market landscape analysis for topical treatments, oral medications, minimally invasive procedures (rubber band ligation, sclerotherapy, infrared coagulation), and surgical interventions (hemorrhoidectomy, stapled hemorrhoidopexy).


Primary Research

Qualitative and quantitative insights were obtained by interviewing supply-side and demand-side stakeholders during the primary research process. The supply-side sources consisted of CEOs, VPs of Product Development, regulatory affairs chiefs, and commercial directors from hemorrhoid treatment device manufacturers, pharmaceutical companies, and medical device OEMs. Demand-side sources consist of procurement leads from hospitals, specialty clinics, and retail pharmacy chains, as well as board-certified colorectal surgeons, gastroenterologists, general surgeons, and medical directors of ambulatory surgical centers. Market segmentation was validated, product pipeline timelines were confirmed, and insights regarding clinical adoption patterns, pricing strategies, reimbursement dynamics, and patient preference shifts toward minimally invasive treatments were gathered through primary research.

Primary Respondent Breakdown:

By Designation: C-level Primaries (32%), Director Level (31%), Others (37%)

By Region: North America (38%), Europe (29%), Asia-Pacific (25%), Rest of World (8%)


Market Size Estimation

Global market valuation was derived through revenue mapping, procedure volume analysis, and pharmaceutical sales data. The methodology included:

Identification of 40+ key manufacturers across North America, Europe, Asia-Pacific, and Latin America

Product mapping across topical treatments (creams, ointments, suppositories), oral medications (venoactive drugs, analgesics), minimally invasive procedures (band ligators, sclerotherapy injectors, infrared coagulators), and surgical procedures (excisional hemorrhoidectomy, stapled hemorrhoidopexy)

Analysis of reported and modeled annual revenues specific to hemorrhoids treatment portfolios

Coverage of manufacturers representing 72-78% of global market share in 2024

Extrapolation using bottom-up (procedure volume × ASP by country, prescription volume × drug pricing by region) and top-down (manufacturer revenue validation, pharmaceutical sales data triangulation) approaches to derive segment-specific valuations for treatment types, severity levels, patient demographics, and distribution channels

Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.