Feed Phosphate Market (2026 - 2035)

Feed Phosphate Market Size, Share, Industry Trend & Analysis Research Report By Feed Type (Monocalcium Phosphate, Dicalcium Phosphate, Mono-Dicalcium Phosphate, Tricalcium Phosphate, Defluorinated Phosphate, Other Feed Types), By Livestock Type (Poultry, Swine, Cattle, Aquatic Animals, Other Livestock Types), By Region (North America, Europe, Asia-Pacific, South America, Middle East & Africa) - Forecast to 2035.
ID: MRFR/Agri/40219-HCR 128 Pages Snehal Singh, Harshita Gorde Last Updated: September 11, 2026
Feed Phosphate Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)6.4%
2025 Market SizeUSD 2.98 Billion
2035 Market SizeUSD 5.53 Billion
Key Players
OCP S.A.
PJSC PhosAgro
Yara International ASA
EuroChem Group AG
Nutrien Ltd.
Phosphea
Opportunities
  • Struvite and Manure-Ash Recovery
  • Emerging-Market Premix Localization
  • Digital Formulation Services and Data Monetization

Feed Phosphate Market Summary

The Feed Phosphate Market was valued at USD 2.98 billion in 2025 and opens the forecast window at USD 3.17 billion in 2026, climbing to USD 5.53 billion by 2035 at a 6.4% CAGR. Two catalysts anchor that trajectory. India's National Livestock Mission, with a budgeted outlay above USD 290 million, is pushing organized feed formulation into smallholder dairy and broiler clusters [1]. In parallel, the EU Fertilising Products Regulation 2019/1009 legitimized recovered phosphorus streams, opening a compliant secondary supply channel that simply did not exist commercially a decade ago [2].

Technology is rewriting the cost curve. Legacy wet-process defluorination lines — energy-hungry, fluorine-heavy, and calibrated for coarse dicalcium grades — are giving way to low-temperature acidulation and struvite recovery trains. The Mosaic Company, OCP S.A., and Prayon have collectively committed roughly USD 1.4 billion since 2023 to purification and defluorination retrofits [3][4]. Near-infrared inline sensors now trim over-dosing by 8–12% per tonne of finished feed, which compresses volume but lifts realized price per unit [5].

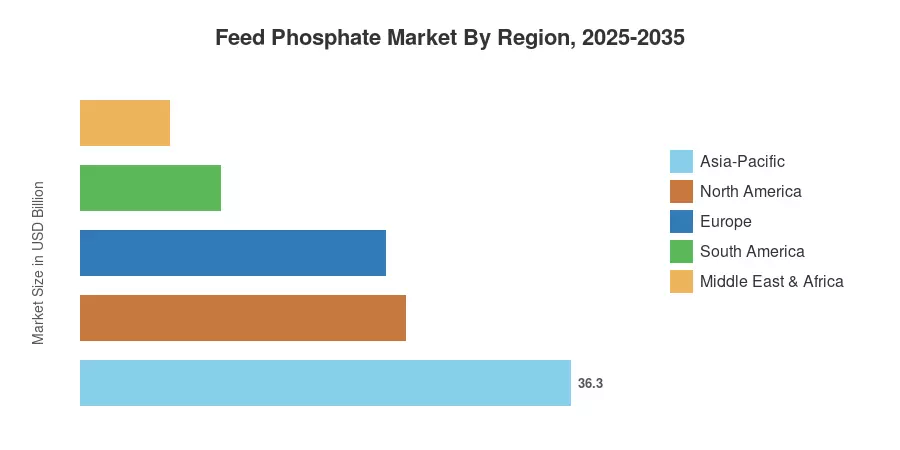
Regionally, Asia-Pacific holds 36.3% of global demand, Europe grows fastest at a 5.6% CAGR on circular-phosphorus mandates, and North America ranks second on 24.1% share supported by integrated poultry complexes. The Feed Phosphate Market is therefore shifting from a tonnage story to a bioavailability-and-carbon story.


Key Report Takeaways

• By Feed Type

  • Dicalcium phosphate commanded 39.0% of the Feed Phosphate Market in 2025, still the default macromineral carrier in compound feed.
  • Mono-dicalcium phosphate is projected to advance at a 6.5% CAGR through 2035 on superior phosphorus digestibility.
  • Defluorinated phosphate generated USD 0.19 billion in 2025, concentrated in ruminant premixes.

• By Livestock Type

  • Poultry absorbed 45.4% of demand in 2025, the single largest consuming category.
  • Swine applications delivered USD 0.80 billion in 2025 across China, the US, and Spain.
  • Aquatic animals post the fastest livestock CAGR at 5.8% to 2035.

• By Region

  • Asia-Pacific led the Feed Phosphate Market with a 36.3% share in 2025.
  • Europe expands at a 5.6% CAGR, the quickest of any region.
  • South America contributed USD 0.31 billion in 2025, led by Brazilian broiler integrators.


Market Size and Forecast (2021–2035)

Estimates in the Feed Phosphate Market blend bottom-up tonnage modeling from national compound-feed statistics with top-down triangulation against phosphate rock beneficiation output, customs trade flows, and audited producer disclosures. Historical values reflect realized transaction prices net of freight.
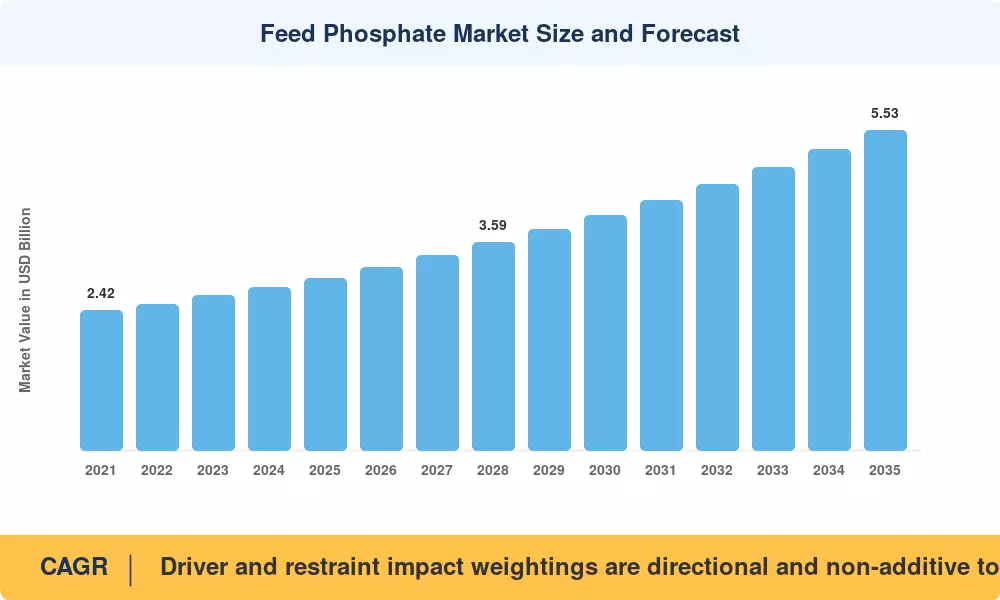
Feed Phosphate Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Animal protein demand in emerging economies 24 Asia-Pacific, South America Long-term (≥4 yr)
Consolidation into large integrated units 18 China, Brazil, US Medium-term (2–4 yr)
Circular phosphorus recovery mandates 15 Europe, North America Long-term (≥4 yr)
Shift to high-bioavailability grades 13 Global Medium-term (2–4 yr)
Aquaculture intensification 11 ASEAN, India, Norway Long-term (≥4 yr)
Antibiotic-growth-promoter phase-outs 10 EU, US, South Korea Short-term (≤2 yr)
Rock phosphate quality decline 9 MEA, North America Medium-term (2–4 yr)


Animal Protein Demand in Emerging Economies

OECD-FAO forecasts a 14% increase in meat consumption in lower-middle-income countries by 2033, with poultry being around half of the incremental volume [10]. Each extra ton of compound broiler feed draws 8-11 kg of inorganic phosphate into the chain. Compound feed capacity installed in India alone between 2022-2025 is 2.4 million tons [1].


Circular Phosphorus Recovery Mandates

Germany's amended Sewage Sludge Ordinance obliges plants above 50,000 population equivalents to recover phosphorus from 2032, and the European Sustainable Phosphorus Platform estimates recoverable volumes near 500,000 tonnes P annually across the bloc [2][16]. Feed-grade qualification remains the gating factor, yet three struvite plants secured EFSA-aligned dossiers in 2025.

Migration to High-Bioavailability Grades

Relative phosphorus availability (RP) of monocalcium and mono-dicalcium grades is 6–9 percentage points over conventional dicalcium, as shown by digestibility trials published by FEFANA [12]. This disparity has allowed nutritionists to lower inclusion rates and still get the performance, an economic rationale that has changed formulation defaults across Western European broiler farms.


Aquaculture Intensification

The FAO reported that aquaculture production of aquatic animal food surpassed that of catch fisheries in 2022, and that feed-based systems now account for 71% of farmed production [13]. Shrimp and tilapia diets are the most phosphate-intensive growth pocket as they have a larger phosphate inclusion than terrestrial species because of poor phytate hydrolysis.


Restraints Impact Analysis

Restraint ~% Drag on CAGR Geographic Relevance Impact Timeline
Phytase enzyme substitution 26 Global Short-term (≤2 yr)
Precision dosing reducing over-supplementation 19 Europe, North America Medium-term (2–4 yr)
Cadmium and fluorine contaminant limits 16 EU, Japan Medium-term (2–4 yr)
Energy-intensive defluorination economics 14 Europe, MEA Short-term (≤2 yr)
Rock phosphate export controls 12 China, Morocco Long-term (≥4 yr)


Phytase Enzyme Substitution

Sixth-generation phytases can release as much as 0.20% more accessible phosphorus at commercial levels, enabling formulators to take off 30-40% of inorganic inclusion from broiler diets [17]. The enzyme cost per ton of feed is currently below the displaced mineral cost in most markets, and the exchange is margin accretive, not just regulatory.


Contaminant Ceilings on Imported Grades

EU Regulation 2002/32/EC caps cadmium in feed phosphates at 60 mg/kg P₂O₅, a threshold that disqualifies several sedimentary rock sources without costly purification [18]. Japanese buyers still apply stricter internal specifications. Compliance capex of USD 40–70 million per line has pushed smaller producers toward tolling arrangements.

Defluorination Energy Economics

Calcination consumes 1.6–2.1 GJ per tonne of finished product, and European industrial gas prices remained above pre-2021 baselines through 2025 [19]. Producers responded by idling marginal capacity and importing finished dicalcium grades, compressing regional margins even as demand held.


Feed Phosphate Market Opportunities

Struvite and Manure-Ash Recovery

Wastewater-recovered struvite and sewage sludge ash are permitted only as agricultural fertilizers; EU feed regulations strictly prohibit municipal waste materials in animal feed, preventing EFSA feed-additive authorization despite low-carbon benefits.

Emerging-Market Premix Localization

Nigeria, Vietnam, and Egypt import most finished feed phosphates today. Localized blending hubs, sited near ports and backed by development-finance guarantees, could capture 15–20% landed-cost savings. The African Development Bank's feed and fodder facility earmarked USD 180 million toward such infrastructure in 2024 [20].

Digital Formulation Services and Data Monetization

Producers are packaging near-infrared assay data, digestibility coefficients, and dosing algorithms into subscription platforms sold alongside tonnage. Phosphea and Nutrien have both piloted per-tonne analytics fees, converting a commodity relationship into recurring revenue [21]. This shift matters most where phosphorus supplementation is already tightly optimized.

Aquafeed-Specific Grades

Water-stable, low-leaching phosphate formats command 12–18% price premiums in shrimp diets and remain under-supplied across ASEAN [13]. Regional capacity additions have lagged aquaculture output growth for four consecutive years.

Insect-Protein Co-Location

Black soldier fly frass carries organically bound phosphorus that blends into ruminant rations. Co-locating recovery capacity beside insect facilities shortens logistics and qualifies for EU circular-economy incentives [16].


Feed Phosphate Market Future Outlook

Algorithmic Dosing Becomes Default

By 2030, most tier-one feed mills will be controlled by artificial-intelligence formulation engines coupled with inline near-infrared tests. European broiler trials reduced phosphorus over-supply by 9-14% without loss of performance [5]. This results in moderated tonnage growth in the Feed Phosphate Market, and improved profit per ton – a trade now publicly preferred by most producers.


Carbon Accounting Reshapes Sourcing

Scope-3 reporting under CSRD forces feed buyers to itemize mineral inputs. Calcined defluorinated grades carry roughly 1.9 tonnes CO₂e per tonne of product versus under 0.8 for recovered struvite [16][19]. Expect dual-tier pricing to emerge by 2028, with certified low-carbon material trading at a visible premium.

Supply Chain Regionalization

Chinese export licensing and Red Sea freight disruption taught buyers the cost of single-source dependence. IFA anticipates regional self-sufficiency ratios improving across South America and Southeast Asia through targeted mid-scale plants rather than mega-projects [15].

Enzyme–Mineral Co-Optimization

Rather than competing outright, phytase and inorganic phosphate are converging into jointly optimized packages. Suppliers offering both will capture formulation control, and Rabobank expects bundled offerings to cover a third of Western compound feed volume by 2032 [11].


Regional Market Share Analysis

Region Share of Global Market (2025) Primary Investment Themes
Asia-Pacific 36.3% Aquafeed grades, compound feed capacity, import substitution
North America 24.1% Purification retrofits, integrator supply contracts
Europe 22.6% Circular recovery, contaminant compliance, low-carbon lines
South America 10.4% Broiler export complexes, port-side blending
Middle East & Africa 6.6% Rock beneficiation, downstream value capture
Total 100.0%

Regional concentration in the Feed Phosphate Market tracks livestock density more closely than phosphate rock endowment, which is why import-dependent Asia leads consumption while resource-rich Morocco remains primarily an exporter.


North America

Country Metric Key Driver
US 78.4% of regional share Vertically integrated poultry complexes
Canada USD 0.09 Billion Swine export processing in Manitoba
Mexico 6.1% CAGR Rising per-capita poultry consumption


The North American slice of the Feed Phosphate Market runs on contract structures rather than spot trade. USDA data show broiler production topping 9.5 billion metric tons of live weight in 2024, with integrators locking multi-year mineral supply to hedge input volatility [22]. Mosaic's Bartow purification investment targets precisely this contracted volume.

Europe

Country Metric Key Driver
Germany 21.8% of regional share Sewage sludge phosphorus recovery mandate
UK USD 0.08 Billion Poultry sector consolidation
France 15.4% of regional share Ruminant premix demand
Italy 5.4% CAGR Aquaculture and dairy formulation
Spain 17.2% of regional share Europe's largest swine herd
Nordic Countries 6.0% CAGR Salmon feed phosphate grades
Russia USD 0.06 Billion Domestic integrated producers
Rest of Europe 9.1% of regional share Central European feed milling


Europe grows fastest despite flat livestock numbers because value migrates upward. The bloc's Farm to Fork targets and the Fertilising Products Regulation together create a compliance premium for recovered and low-cadmium material [2]. Spanish and Danish swine producers, facing nitrate directive pressure, have adopted precision phosphorus supplementation faster than any other cohort [23].

Asia-Pacific

Country Metric Key Driver
China 41.6% of regional share World's largest swine and aquafeed complex
India 7.1% CAGR National Livestock Mission feed expansion
Japan USD 0.11 Billion High-specification imported grades
South Korea 6.8% of regional share Antibiotic-free poultry programs
ASEAN 18.3% of regional share Shrimp and tilapia aquafeed
Rest of Asia-Pacific USD 0.07 Billion Dairy expansion in Pakistan and Bangladesh


Asia-Pacific anchors the Feed Phosphate Market through sheer volume. China's Ministry of Agriculture and Rural Affairs set a 2025 target to cut soybean meal inclusion in compound feed below 13%, a reformulation that raises reliance on precisely dosed mineral inputs [24]. India's parallel push through cooperative dairy channels is smaller in tonnage but faster in percentage terms.

South America

Country Metric Key Driver
Brazil 71.3% of regional share World's top chicken meat exporter
Argentina USD 0.05 Billion Beef feedlot intensification
Rest of South America 5.9% CAGR Peruvian and Chilean aquaculture


Brazilian export competitiveness rests on feed conversion, and ABPA reports broiler exports exceeding 5.2 million tonnes in 2024 [25]. Domestic phosphate production from Araxá and Catalão covers part of demand, but feed-grade purity gaps still pull imports through Santos and Paranaguá.

Middle East & Africa

Country Metric Key Driver
Saudi Arabia 24.7% of regional share Ma'aden downstream integration
UAE USD 0.02 Billion Poultry self-sufficiency programs
South Africa 6.4% CAGR Commercial broiler recovery
Egypt 19.2% of regional share Tilapia aquaculture scale
Rest of MEA USD 0.05 Billion Morocco-linked regional trade


OCP's Jorf Lasfar platform gives the region an unmatched upstream position, yet only a minority of output is converted domestically into feed grades [4]. Saudi and Emirati food-security programs are the clearest route to closing that value-capture gap.


Feed Phosphate Market By Region, 2025-2035

Feed Phosphate Market Segmentation

Segmentation in the Feed Phosphate Market follows two commercially meaningful axes: the chemistry of the phosphate carrier and the species consuming it.

By Feed Type

Feed type is the sharpest determinant of price realization across the Feed Phosphate Market.

Segment Metric (2025) Primary Demand Driver
Monocalcium Phosphate USD 0.76 Billion High digestibility in monogastric diets
Dicalcium Phosphate 39.0% share Cost-efficient default carrier
Mono-Dicalcium Phosphate 6.5% CAGR Balanced solubility and handling
Tricalcium Phosphate 9.4% share Ruminant and pet nutrition
Defluorinated Phosphate 6.9% CAGR Cattle mineral blocks
Other Feed Types USD 0.11 Billion Specialty and organic-bound sources


Dicalcium phosphate retains scale because it remains the cheapest compliant route to available phosphorus, particularly across price-sensitive South Asian and African mills. Its share is eroding slowly, not collapsing. Mono-dicalcium grades grow fastest because they thread the needle between monocalcium's digestibility and dicalcium's handling stability, an advantage that matters when pelleting temperatures climb.

By Livestock Type

Species mix determines inclusion rates and therefore regional intensity across the Feed Phosphate Market.

Segment Metric (2025) Primary Demand Driver
Poultry 45.4% share Broiler cycle speed and skeletal load
Swine USD 0.80 Billion Chinese and European herd scale
Cattle 18.1% share Dairy productivity programs
Aquatic Animals 5.8% CAGR Shrimp and tilapia intensification
Other Livestock Types USD 0.08 Billion Equine, pet, and small ruminant


Poultry dominates for structural reasons: short cycles, rapid skeletal deposition, and near-universal use of formulated compound feed. Swine sits second and is the most exposed to phytase displacement, since pig diets tolerate enzyme-led reformulation with minimal performance risk. Aquatic species grow fastest, driven by intensification rather than inclusion-rate increases.


Competitive Benchmarking

Concentration in the Feed Phosphate Market is moderate. The estimated HHI sits near 1,050, with the top five suppliers holding roughly 46–52% of global revenue. Below that tier, the field fragments quickly into regional acidulators and tolling operators, which is why price discovery remains more local than a globally traded commodity would suggest.

Company Est. Revenue Share Range Key Offerings Strategic Positioning
The Mosaic Company ~12–15% Biofos MCP/DCP, Nexfos defluorinated Integrated US rock-to-feed platform
OCP S.A. ~10–13% Feed-grade MCP, DCP Lowest-cost upstream rock position
PJSC PhosAgro ~8–11% MCP, DCP, tricalcium grades Low-cadmium igneous rock advantage
Yara International ASA ~6–9% Feed phosphates, mineral premixes Nutrition-led European channel
EuroChem Group AG ~5–8% DCP, MDCP Vertically integrated CIS supply
Nutrien Ltd. ~4–7% Feed-grade phosphates Retail-linked North American reach
Phosphea (Groupe Roullier) ~3–6% High-bioavailability specialties Digestibility-focused positioning
J.R. Simplot Company ~3–5% Defluorinated phosphate Western US ruminant supply
Prayon S.A. ~2–4% Purified acid derivatives Purification technology licensor
Quimpac S.A. ~1–3% Regional DCP Andean market specialist
Fosfitalia Group ~1–3% Blended mineral products Mediterranean distribution


Recent News & Developments

Deal flow across the Feed Phosphate Market has skewed toward purification and recovery rather than greenfield tonnage.

  • The Mosaic Company (March 2024): Commissioned an expanded Nexfos defluorinated phosphate line in Florida, adding roughly 150,000 tonnes of ruminant-grade capacity and reducing reliance on third-party toll conversion [3].
  • OCP S.A. (September 2024): Announced a USD 320 million downstream program at Jorf Lasfar covering feed-grade purification, positioning Morocco to export finished rather than intermediate product [4].


  • PhosAgro (June 2024): Reported record feed phosphate shipments to Asian buyers, leveraging naturally low cadmium content to meet tightening import specifications [26].
  • Phosphea (November 2024): Launched a digestibility-indexed product line bundled with formulation analytics for European broiler integrators [21].
  • Yara International (April 2025): Signed a multi-year offtake with a Nordic salmon feed producer covering low-carbon phosphate grades certified under third-party verification [27].
  • China MARA (February 2025): Extended export licensing requirements on selected phosphate derivatives, sustaining tightness in Southeast Asian import markets [8].
  • EuroChem (August 2025): Completed debottlenecking at its Kazakhstan complex, lifting mono-dicalcium output for Central Asian and Chinese buyers [28].


Feed Phosphate Market Report Scope

Parameter Detail
Market Scope Global inorganic and recovered feed phosphates used in livestock nutrition
Study Period 2021–2035 (Historical 2021–2024; Base Year 2025; Forecast 2026–2035)
CAGR 6.4% (2026–2035)
Market Size Checkpoints USD 2.98 Billion (2025); USD 3.17 Billion (2026); USD 5.53 Billion (2035)
Fastest Growing Segments Mono-Dicalcium Phosphate (feed type); Aquatic Animals (livestock type); Europe (region)
Companies Profiled 11 major suppliers benchmarked across the Feed Phosphate Market
Valuation Currency USD Billion
CAGR Driver Disclaimer Driver and restraint impact weightings are directional and non-additive to the headline CAGR

FAQs

How should procurement teams structure contracts in the Feed Phosphate Market?
Index-linked contracts tied to phosphoric acid benchmarks reduce exposure better than fixed-price deals. Most integrators now blend a 60/40 contracted-to-spot split. Build in a cadmium specification clause with rejection rights [18].
What certifications should buyers verify before switching suppliers?
FAMI-QS and GMP+ FSA certifications are required for feed suppliers. However, "end-of-waste" status applies exclusively to fertilizers under Regulation (EU) 2019/1009, as recovered waste streams remain prohibited in animal feed.
Does the Feed Phosphate Market face substitution risk from organic phosphorus sources?
Partially. Insect frass and processed animal proteins supply bound phosphorus but lack the dosing precision inorganic grades offer. Expect complementary use rather than displacement through 2035 [16].
How do freight and logistics affect delivered cost?
Ocean freight and inland haulage typically represent 12–18% of delivered cost for import-dependent buyers. Port-side blending cuts that materially. Red Sea rerouting added roughly USD 22 per tonne for Asian buyers in 2024 [15].
What integration challenges arise when adopting recovered phosphates in the Feed Phosphate Market?
Particle size variability and inconsistent moisture disrupt existing dosing equipment. Mills often need recalibration and buffer silos. Pilot at 10% substitution before scaling [16].
Which competitive moves should buyers watch over the next three years?
Watch purification capacity announcements and enzyme-mineral bundling deals. Suppliers controlling both levers gain formulation influence. Consolidation among mid-tier regional acidulators is the likeliest structural shift in the Feed Phosphate Market [11].
Is vertical integration into phosphate rock worth it for large feed producers?
Rarely. Capital intensity and permitting timelines exceed a decade, while long-term offtake achieves most of the security benefit. Only producers exceeding 500,000 tonnes annual consumption should evaluate it [15].    
Author
Author Author Profile Snehal Singh LinkedIn Manager - Research
High acumen in analyzing complex macro & micro markets with more than 6 years of work experience in the field of market research. By implementing her analytical skills in forecasting and estimation into market research reports, she has expertise in Packaging, Construction, and Equipment domains. She handles a team size of 20-25 resources and ensures smooth running of the projects, associated marketing activities, and client servicing.
Co-Author Co-Author Profile Harshita Gorde LinkedIn Research Analyst
Harshita Post graduate MBA in Business Administration from Welingkar Institute, Mumbai and 5 years of experience in the field of product market research. As a Research Analyst, I have cross-domain experience in packaging, and industrial Automation & Equipment. I am currently looking after the research process of packaging, logistics & transportation, and industrial automation & equipment at Market Research Future Reports. My responsibilities at the organization involve handling syndicate and custom reports as well as responding to client inquiries, and organize, co-ordinate with a group of 5 to 6 persons to manage all workflows.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of regulatory databases, peer-reviewed agricultural journals, industry publications, and authoritative agricultural and chemical organizations. Key sources included the US Food & Drug Administration (FDA) Center for Veterinary Medicine, European Food Safety Authority (EFSA), Association of American Feed Control Officials (AAFCO), International Feed Industry Federation (IFIF), Food and Agriculture Organization of the United Nations (FAO), US Geological Survey (USGS) Mineral Commodity Summaries, European Chemicals Agency (ECHA), National Institutes of Health (NIH) - Office of Dietary Supplements, World Health Organization (WHO) Food Safety Programme, Organisation for Economic Co-operation and Development (OECD) Agricultural Outlook, US Department of Agriculture (USDA) Economic Research Service, EU Eurostat Agricultural Database, and national agricultural ministry reports from key markets including China, Brazil, and India. These sources were used to collect feed consumption statistics, regulatory approval data for feed additives, phosphate reserve data, clinical safety studies on animal nutrition, livestock production trends, and market landscape analysis for dicalcium phosphate, monocalcium phosphate, tricalcium phosphate, defluorinated phosphate, and other phosphate technologies.


Primary Research

In order to gather both qualitative and quantitative insights, supply-side and demand-side stakeholders were interviewed during the primary research process. CEOs, VPs of Manufacturing, heads of regulatory affairs, and commercial directors from feed phosphate producers, mining firms, and chemical processors were examples of supply-side sources. Chief nutritionists, feed formulators, procurement managers from commercial feed mills, livestock integrators, aquaculture enterprises, and agricultural cooperatives were examples of demand-side suppliers. Primary research obtained information on feed formulation adoption patterns, pricing tactics, raw material sourcing dynamics, and distribution channel evolution. It also verified production capacity expansion timetables and validated market segmentation.

Primary Respondent Breakdown:

By Designation: C-level Primaries (28%), Director Level (35%), Others (37%)

By Region: North America (32%), Europe (30%), Asia-Pacific (28%), Rest of World (10%)


Market Size Estimation

Global market valuation was derived through revenue mapping and consumption volume analysis. The methodology included:

Identification of 50+ key manufacturers and mining operations across North America, Europe, Asia-Pacific, Latin America, and Middle East & Africa

Product mapping across dicalcium phosphate, monocalcium phosphate, tricalcium phosphate, defluorinated phosphate, and other phosphate categories

Analysis of reported and modeled annual revenues specific to feed phosphate portfolios

Coverage of manufacturers representing 75-80% of global market share in 2024

Extrapolation using bottom-up (feed consumption volume × ASP by country/region) and top-down (manufacturer revenue validation) approaches to derive segment-specific valuations

Cross-verification with phosphate rock mining outputs, feed industry consumption reports, and import/export trade data from UN Comtrade and national customs databases

Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.
















