Europe Gas Generator Market Summary
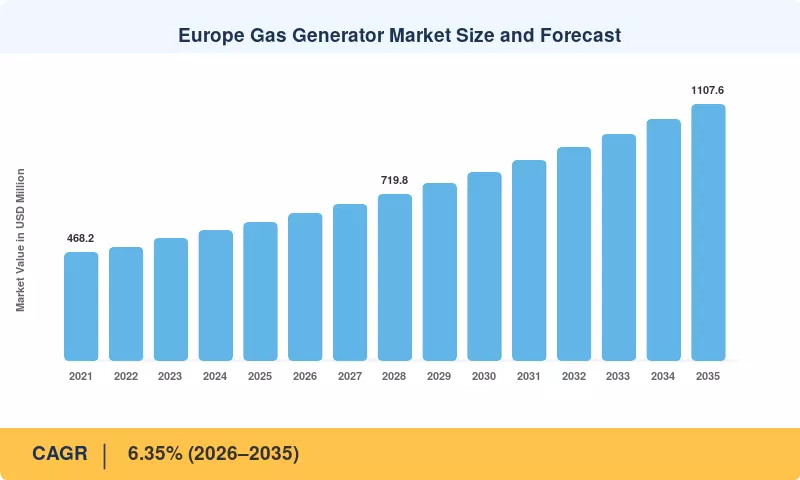
The Europe Gas Generator Market was valued at USD 598.4 Million in 2025 and is projected to reach USD 636.4 Million in 2026, expanding to USD 1,107.6 Million by 2035 at a CAGR of 6.35% over 2026–2035. Two policy levers anchor that trajectory. The Medium Combustion Plant Directive brings existing 1–5 MWth combustion units under binding NOx limits from January 2030 [2], and REPowerEU targets 35 bcm of annual biomethane production by 2030 [1], giving gas-fired sets a lower-carbon fuel pathway that diesel fleets cannot easily match.
Operators across the region are retiring diesel standby fleets in favor of lean-burn natural gas engines, dual-fuel units and hydrogen-ready designs with digital controllers and remote telemetry. The shift is not only about emissions. Gas engines can run for thousands of hours a year, which turns a sunk-cost emergency asset into a working plant that supplies heat, balancing services and peak shaving. Germany's February 2024 power plant strategy set out tenders for up to 10 GW of hydrogen-ready gas capacity [10], while REPowerEU mobilizes roughly €210 billion of additional energy investment through 2027 [1].
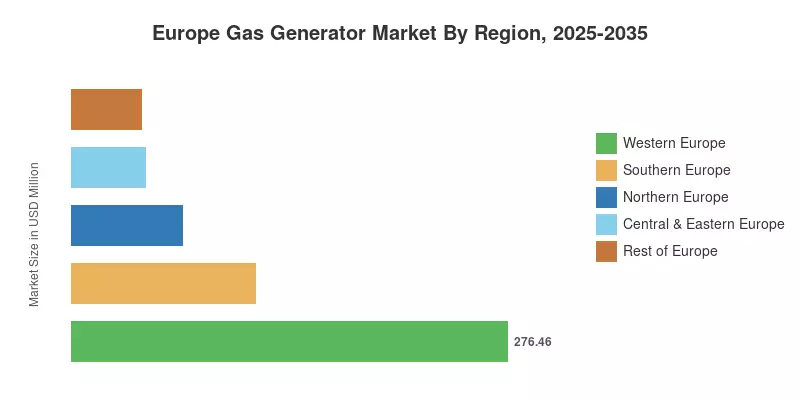
Western Europe holds the dominant position with a 46.2% share in 2025, led by Germany's industrial base and the Frankfurt data center cluster. Central & Eastern Europe is the fastest-growing region at a 7.8% CAGR as Poland and Romania replace coal and expand gas networks. Southern Europe ranks second with 19.5%, supported by Italian cogeneration and post-blackout resilience spending in Iberia. Over the next decade, the Europe Gas Generator Market will be shaped as much by grid flexibility needs as by classic outage protection.
Key Report Takeaways
• By Capacity
- Sets rated more than 375 kVA lead the Europe Gas Generator Market with a 44.7% share in 2025, anchored in data center, utility and heavy-industry duty
- The 75 - 375 kVA class generated USD 220.8 Million in 2025, serving hospitals, retail parks and telecom hubs
- Units rated less than 75 kVA are set to expand at a 7.1% CAGR through 2035 as home and small-business standby adoption rises
• By End User
- Industrial buyers account for a 47.6% share, driven by cogeneration and continuous-process protection
- Commercial demand reached USD 213.0 Million in 2025, led by healthcare, logistics and data facilities
- Residential is the fastest-growing end user in the Europe Gas Generator Market at a 7.4% CAGR
• By Region
- Western Europe commands a 46.2% share, with Germany, the United Kingdom and France as core demand centers
- Central & Eastern Europe posts the fastest growth at a 7.8% CAGR on the back of coal exit programs
- Germany holds 41.8% of Western European revenue, the largest single-country position in the region
Market Size and Forecast (2021–2035)
Figures for the Europe Gas Generator Market combine shipment data from manufacturers, distributor interviews, company disclosures [19][20][21][22], and energy statistics from the IEA, ENTSO-E and Eurostat [5][7][8]. Historical values are reconciled against reported regional revenue of leading suppliers, while forecasts reflect announced policy deadlines, data center pipelines and gas price expectations. All values are expressed in USD Million at constant 2025 exchange rates.


 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA


