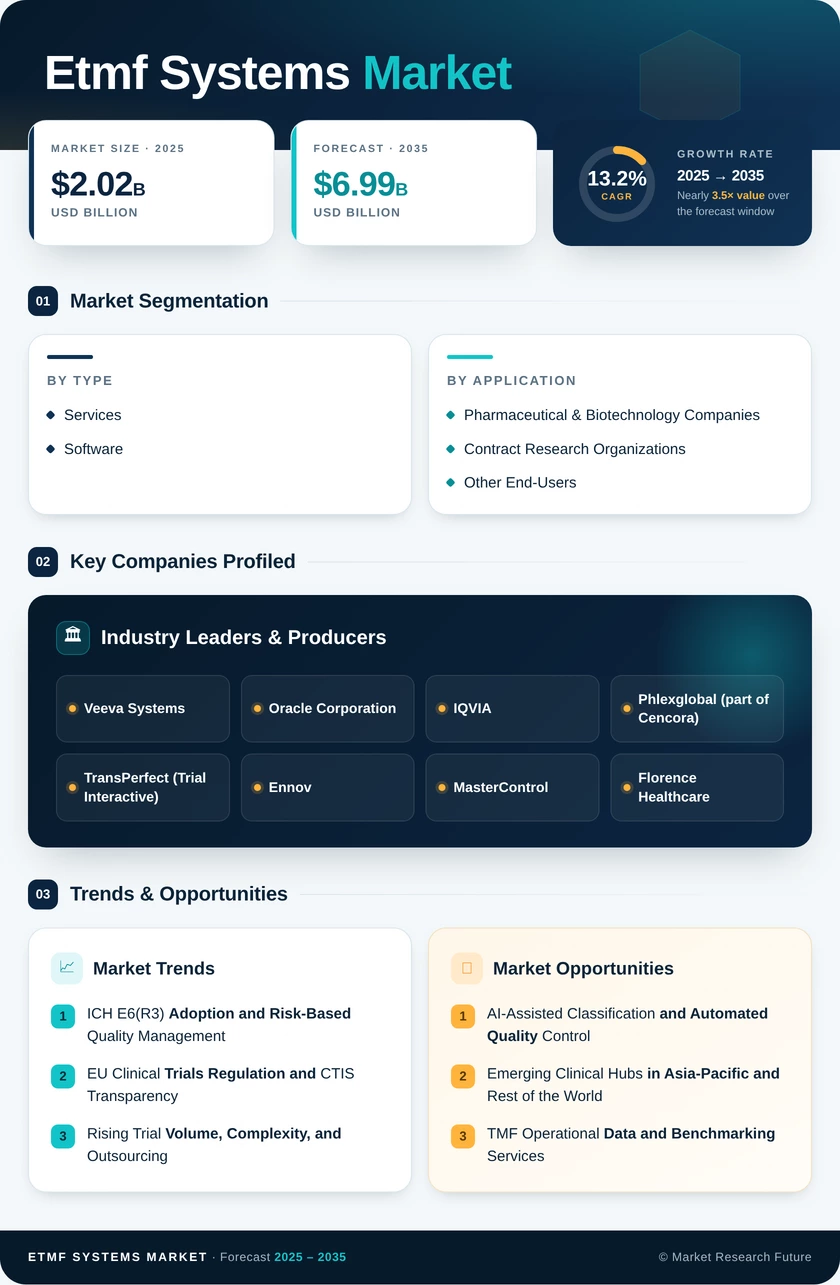
Segmentation Quick Reference
| Dimension | Sub-Segments | Dominant Segment | Fastest Growing Segment |
|---|---|---|---|
| By Product Type | Services, Software | Software — 62.4% share (2025) | Services — 14.6% CAGR (2026–2035) |
| By End-User | Pharmaceutical & Biotechnology Companies, Contract Research Organizations, Other End-Users | Pharmaceutical & Biotechnology Companies — 55.3% share (2025) | Contract Research Organizations — 15.1% CAGR (2026–2035) |
| By Region | North America, Europe, Asia-Pacific, Rest of the World | North America — 44.6% share (2025) | Asia-Pacific — 16.1% CAGR (2026–2035) |
Market Segmentation Overview
By Product Type
| Sub-Segment | Key Trend |
|---|---|
| Services | Outsourced migration, periodic TMF quality review, and fully managed filing bundled with licenses |
| Software | Validated multi-tenant cloud subscriptions sold as modules within unified clinical suites |
Software leads because every sponsor and CRO needs a validated system of record that satisfies Part 11 and EMA computerised-system expectations, and subscriptions spread that cost across a study portfolio. Services grow fastest as sponsors short on in-house TMF specialists pay for legacy migration, pre-inspection quality reviews, and managed filing. Vendors that attach expert review teams to their platforms turn one-off projects into recurring revenue.
By End-User
| Sub-Segment | Key Trend |
|---|---|
| Pharmaceutical & Biotechnology Companies | Consolidation onto enterprise platforms with sponsor-owned oversight dashboards |
| Contract Research Organizations | Multi-sponsor instances and contractual obligations to work inside sponsor systems |
| Other End-Users | Lightweight configurations for investigator-initiated and device studies |
Pharmaceutical & Biotechnology Companies lead because ICH E6(R3) keeps ultimate responsibility for the master file with the sponsor, even when trial execution is outsourced. Contract Research Organizations grow fastest as outsourcing deepens and sponsors demand inspection-ready files from their CRO partners, driving investment in segregated multi-sponsor environments. Other End-Users, such as academic centers, adopt simpler, lower-cost configurations sized for smaller study portfolios.


 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA