Commercial Vehicle Financing Market (2026 - 2035)

Commercial Vehicle Financing Market Research Report By Provider Type (Banks, Captive Finance Arms, NBFCs, Credit Unions), By Financing Type (Loans, Finance Lease, Operating Lease, Credit Line), By Vehicle Condition (New, Used), By Vehicle Type (LCV, Medium/Heavy Trucks, Buses, Special-Purpose), By Channel (Direct, Online Aggregators, Broker-Assisted) - Forecast to 2035
ID: MRFR/AT/33253-HCR 100 Pages Abbas Raut, Swapnil Palwe Last Updated: October 03, 2026
Commercial Vehicle Financing Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)6.40%
2025 Market SizeUSD 122.5 Billion
2035 Market SizeUSD 228.6 Billion
Key Players
Daimler Truck Financial Services
Volvo Financial Services
PACCAR Financial
Toyota Financial Services
Wells Fargo Equipment Finance
Ally Financial
Opportunities
  • Underpenetrated Emerging Markets in Africa and ASEAN
  • Telematics Data Monetization and Usage-Based Contracts
  • Battery-as-a-Service and Split-Asset Financing

Commercial Vehicle Financing Market Summary

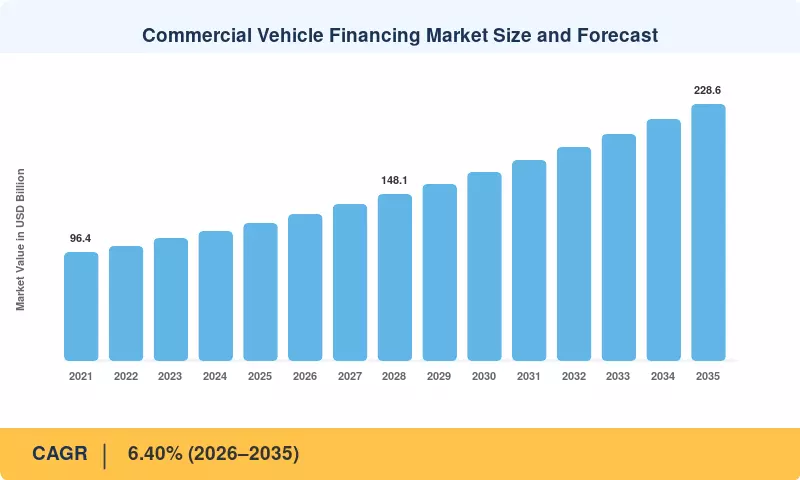
The Commercial Vehicle Financing Market was valued at USD 122.5 billion in 2025 and is projected to reach USD 130.8 billion in 2026, then expand at a CAGR of 6.40% to USD 228.6 billion by 2035. Two policy catalysts anchor this trajectory. The European Union's revised heavy-duty CO2 regulation requires a 45% emissions cut for new trucks by 2030 [3], and India's PM E-DRIVE scheme commits ₹10,900 crore (about USD 1.3 billion) to electric buses, trucks and charging infrastructure [5]. Both push fleets toward higher-value assets that almost always require external credit.

Origination itself is being rebuilt. Branch-based underwriting that depended on audited financials and physical collateral inspections is giving way to data-driven credit decisions built on telematics feeds, fuel-card histories and e-invoice records. Captive lenders now surface financing offers inside OEM fleet portals, while non-bank lenders score owner-operators on GPS-derived utilization. The Equipment Leasing and Finance Association puts annual U.S. equipment finance volume at roughly USD 1,300 billion [10], and a rising share of truck and van deals within that pool now clears approval in hours rather than days.

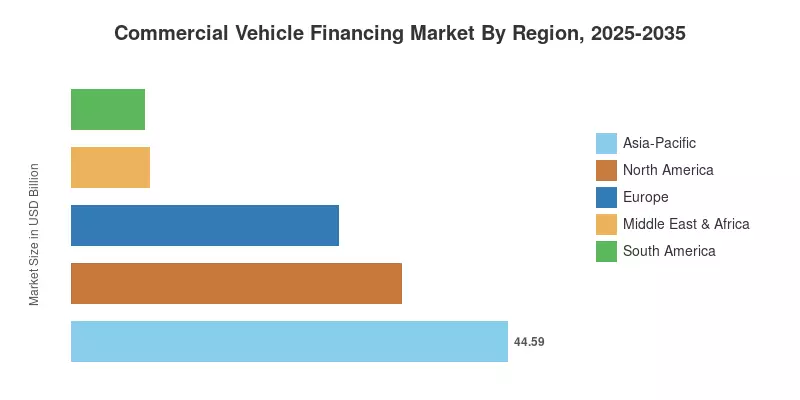
Within the Commercial Vehicle Financing Market, Asia-Pacific leads with a 36.4% share in 2025, supported by China's freight base and India's NBFC-led lending to small fleet owners. Middle East & Africa is the fastest-growing region at a 6.47% CAGR, as Gulf logistics corridors and African trade-route upgrades lift truck and van demand. North America ranks second, backed by deep captive-finance penetration and a mature leasing ecosystem. Over the next decade, advantage will shift toward lenders that can price battery-electric residual risk with confidence.

Key Report Takeaways

• By Provider Type

  • Banks held a 44.4% share in 2025, although Basel III final reforms are raising the capital cost of balance-sheet truck lending
  • NBFCs are projected to post a 6.42% CAGR, the fastest among provider types, by funding informal operators that banks overlook

• By Financing Type

  • Loans accounted for a 60.7% share of the Commercial Vehicle Financing Market in 2025, reflecting owner-operator preference for asset ownership
  • Operating Lease is forecast to grow at a 6.50% CAGR as fleets shift residual-value risk to lessors

• By Vehicle Condition

  • New vehicles represented a 54.3% share in 2025, anchored by OEM captive programs at dealer point-of-sale
  • Used vehicle financing is set to expand at a 6.52% CAGR, helped by AI-based depreciation models

• By Vehicle Type

  • LCV led the Commercial Vehicle Financing Market with a 42.9% share in 2025, driven by parcel and quick-commerce fleets
  • Medium/Heavy Trucks generated USD 44.6 billion in 2025, with the largest ticket sizes in the portfolio

• By Channel

  • Direct origination retained a 69.0% share in 2025 through dealer desks and captive portals.
  • Online Aggregators are expected to grow at a 6.55% CAGR as AI underwriting compresses approval times.

• By Region

  • Asia-Pacific contributed a 36.4% share in 2025
  • Middle East & Africa is forecast to grow at a 6.47% CAGR through 2035
  • North America reached USD 33.8 billion in 2025

Market Size and Forecast (2021–2035)

Market Research Future sized the Commercial Vehicle Financing Market by aggregating outstanding and newly originated loan, lease and credit-line volumes across banks, captive finance arms, NBFCs and credit unions, cross-checked against OEM delivery data, lender annual reports and regulatory filings. Historical values for 2021–2024 draw on reported portfolio disclosures and industry association statistics, while 2026–2035 figures apply a bottom-up forecast by vehicle type and region, adjusted for interest-rate paths, emission rules and electrification adoption curves.
Commercial Vehicle Financing Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
E-commerce and urban delivery demand for LCV fleets +1.1% Global; strongest in Asia-Pacific and North America Medium term (2–4 yr)
Fleet electrification raising average ticket sizes +1.0% Europe, China, North America Long term (≥4 yr)
NBFC and alternative-data lending to informal operators +0.9% India, ASEAN, Africa Short term (≤2 yr)
Embedded OEM telematics and captive finance +0.8% North America, Europe Medium term (2–4 yr)
Emission-norm replacement cycles and pre-buys +0.7% North America, Europe, India Short term (≤2 yr)
Logistics corridor investment in the Gulf and Africa +0.6% Middle East & Africa Long term (≥4 yr)


E-Commerce and Urban Delivery Demand for LCV Fleets

Dense fleets of sub-3.5-ton vans are necessary for parcel networks, and hardly any of them are purchased outright. The scale is demonstrated by Amazon's pledge to install 100,000 specialized electric delivery trucks by 2030 [21]. Each van is leased or financed, frequently through multi-year servicing contracts. Electric three-wheelers are being added by quick-commerce companies in India at a comparable rate. Lenders are able to carefully price utilization risk due to the predictability of delivery routes, which maintains high approval rates and drives LCV origination volumes ahead of all other vehicle classes.


Fleet Electrification Raising Average Ticket Sizes

For new heavy-duty vehicles, Regulation (EU) 2024/1610 requires CO2 reductions of 45% by 2030, 65% by 2035, and 90% by 2040 [3]. According to an ICCT cost study, battery-electric tractors are currently two to three times more expensive to buy than their diesel counterparts [7]. Even in cases where unit volumes are unchanged, that price difference increases average financed balances. Lenders benefit from having more books per client, but they also have to deal with lengthier repayment terms and more collateral concerns related to battery status.


NBFC and Alternative-Data Lending to Informal Operators

India's Scale Based Regulation framework, introduced by the Reserve Bank of India in 2021, formalized oversight of large NBFCs while leaving room for specialist vehicle lenders to grow [8]. Shriram Finance reported assets under management above ₹2.6 lakh crore (about USD 30 billion) in FY2025, with commercial vehicles its largest segment [19]. These lenders underwrite first-time owner-operators using repayment behavior, fuel spend and mobile-wallet data, reaching a borrower pool that bank credit models reject.

Embedded OEM Telematics and Captive Finance

Captive lenders convert telematics access into pricing power. PACCAR's financial services segment manages assets above USD 20 billion [20], and Daimler Truck Financial Services bundles financing with connectivity and maintenance packages across its brands [25]. Real-time location, engine health and mileage data lower loss-given-default because repossession and remarketing become faster. Captives use this edge to offer rates that independent banks struggle to match on new-vehicle deals at the dealer desk.

Emission-Norm Replacement Cycles and Pre-Buys

The U.S. EPA's December 2022 heavy-duty rule cuts allowable NOx emissions by more than 80% from model year 2027 [11]. Compliance adds engineering cost to every new truck, prompting fleets to accelerate purchases of current-generation models during 2025–2026. Similar pre-buy patterns followed India's BS-VI Phase 2 transition in April 2023. Each cycle pulls origination volume forward, delivering short bursts of loan demand followed by softer quarters that lenders must plan around.

Logistics Corridor Investment in the Gulf and Africa

Saudi Arabia's National Transport and Logistics Strategy targets more than SAR 1 trillion (about USD 267 billion) of transport and logistics investment by 2030 [22]. New ports, dry ports and rail-linked drayage hubs create sustained demand for heavy trucks, tankers and last-mile vans. Sovereign-backed contractors typically finance fleets through structured leases with regional banks and captives. Comparable corridor programs in Egypt and East Africa extend this pipeline beyond the Gulf.

Restraints Impact Analysis

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
Interest-rate volatility and higher funding costs −0.8% Global Short term (≤2 yr)
Residual-value uncertainty for battery-electric trucks −0.6% Europe, North America, China Medium term (2–4 yr)
Basel III final reforms raising bank capital charges −0.5% Europe, North America Medium term (2–4 yr)
Credit stress among small fleets and owner-operators −0.5% North America Short term (≤2 yr)
Reversal of clean-vehicle purchase incentives −0.4% North America Short term (≤2 yr)


Interest-Rate Volatility and Higher Funding Costs

The Federal Reserve lifted its policy rate range to 5.25–5.50% by July 2023 before cutting 100 basis points in late 2024 [12]. Swings of this size reprice floating-rate credit lines immediately and compress margins on fixed-rate loans funded short. Owner-operators respond by delaying replacements, which extends asset ages and reduces origination counts. Lenders with matched-funding structures or deposit bases weather these cycles better than wholesale-funded independents.

Basel III Final Reforms Raising Bank Capital Charges

The Basel Committee's 2017 package [1] is now arriving in national rules. The EU's CRR3 has applied since January 1, 2025 [9], and the 2023 U.S. proposal for large banks projected an aggregate increase in common equity tier 1 requirements of about 16% [13]. Higher risk weights on unrated corporate borrowers make balance-sheet truck lending less attractive, nudging banks toward partnerships or asset sales.

Residual-Value Uncertainty for Battery-Electric Trucks

Sources reported a 20% fall in average lithium-ion pack prices in 2024, to USD 115 per kWh [16]. Rapid cost declines are welcome for buyers but erode the resale value of vehicles already on lenders' books. With thin auction data for used electric trucks, lessors add conservative residual buffers, which raises monthly payments and slows adoption among price-sensitive fleets.

Credit Stress Among Small Fleets and Owner-Operators

While insurance and maintenance costs increased, spot rates were squeezed by the 2023–2024 U.S. freight recession. For significant portions of that time, operating-authority revocations exceeded new permits, according to FMCSA registration data [14]. Lenders tightened down payment criteria and shortened tenors for small operators as a result of the concentration of delinquencies among carriers with fewer than ten trucks.


Reversal of Clean-Vehicle Purchase Incentives

2025 legislation terminated the U.S. Commercial Clean Vehicle Credit for vehicles purchased after September 30, 2025 [6]. The credit offered up to USD 40,000 per qualifying heavy vehicle. Eliminating the credit makes electric fleet leases less profitable and increases the initial cost difference with diesel. Until cost parity is reached, financing demand for battery-electric units in North America is probably going to decline.


Commercial Vehicle Financing Market Opportunities

Underpenetrated Emerging Markets in Africa and ASEAN

Formal credit reaches only a fraction of truck buyers in sub-Saharan Africa and parts of ASEAN, where most vehicles are bought used and paid in cash. The World Bank's Logistics Performance Index 2023 shows wide performance gaps between these regions and advanced economies [15], and closing them requires fleet renewal. Lenders that pair mobile-money repayment data with local dealer networks can build a durable position in the Commercial Vehicle Financing Market before global banks arrive.

Telematics Data Monetization and Usage-Based Contracts

Connected vehicles generate mileage, idle-time and driving-behavior data that lenders can turn into revenue. Pay-per-kilometre leases, dynamic insurance bundles and fleet benchmarking services allow financiers to earn fee income beyond interest spread. Captives already hold this data; independent lenders can access it through aggregator APIs. The model also improves collections, because contracts can adjust payments to real utilization.

Battery-as-a-Service and Split-Asset Financing

A new asset class for energy firms and infrastructure funds is created by separating battery ownership from the chassis, which also lowers the upfront ticket for operators. The idea has been scaled up in China's heavy-truck battery-swap networks [4]. While a battery owner receives fees per kWh and bears the risk of degradation, financiers can fund the chassis on traditional terms.


Certified Used-Vehicle Finance Backed by AI Residual Models

With validated service histories and telemetry records, OEM-certified pre-owned programs now provide prices that are comparable to those of new cars [20]. Lenders can prolong tenors on used trucks with lower loss rates by using machine-learning models trained on auction results to predict depreciation by manufacturer, mileage, and duty cycle. This opens up a sizable underserved borrower market for smaller fleets.


Fleet Securitization and Green Asset-Backed Funding

Lenders can recycle capital by packaging truck loans and leases into asset-backed securities, easing the pressure from bank capital rules. Portfolios of zero-emission vehicles qualify for green labels under the ICMA Green Bond Principles [17], attracting ESG-mandated investors at tighter spreads. Securitization also gives NBFCs a funding source independent of bank credit lines.

Commercial Vehicle Financing Market Future Outlook

AI Underwriting and Embedded Telematics Finance

Credit decisions in the Commercial Vehicle Financing Market will increasingly run on live operating data rather than historical financial statements. Lenders will score fleets on route profitability, fuel efficiency and maintenance compliance pulled directly from vehicles. Expect approval times to fall to minutes for standard LCV deals and collections to shift toward automated, utilization-linked payment schedules that reduce default rates among seasonal operators.

Electrification and the Build-Out of Residual-Value Markets

Battery-electric trucks remain a small share of global sales, concentrated in China and Europe, according to the IEA [4]. U.S. Phase 3 greenhouse-gas standards finalized in March 2024 [2] and EU targets for 2030 imply rapid growth later in the decade, though policy direction in the U.S. remains fluid. The decisive variable for lenders will be liquid secondary markets for used electric trucks, which will narrow residual buffers and lower lease rates.

Platform Economics and Embedded Distribution

Financing will increasingly be sold inside platforms that fleets already use: OEM portals, freight marketplaces, fuel-card apps and fleet-management software. Platform owners will capture origination fees while balance-sheet lenders compete on funding cost. This splits the value chain between distribution and capital, favouring lenders with low-cost funding and API-ready credit engines over those relying on branch networks.

ESG Disclosure and Sustainability-Linked Lending

The ISSB's IFRS S2 standard, issued in June 2023 [18], requires companies to disclose climate risks, including financed emissions for lenders adopting it. Banks and lessors in the Commercial Vehicle Financing Market will face pressure to shift portfolios toward low-emission vehicles and price diesel assets for transition risk. Sustainability-linked loans with margin step-downs for verified emissions cuts are likely to spread from large corporates to mid-size fleets.

Regional Market Share Analysis

Region Key Metric (2025) Primary Investment Themes
North America USD 33.8 Billion Captive finance, EPA 2027 pre-buy, credit-union niches
Europe 22.3% share CO2-driven fleet renewal, operating leases, CRR3 capital rules
Asia-Pacific 36.4% share NBFC lending, electric LCVs and three-wheelers, China freight base
South America USD 7.5 Billion Agribusiness trucking, BNDES-backed credit lines
Middle East & Africa 6.47% CAGR Logistics corridors, sovereign-fund infrastructure projects
Total USD 122.5 Billion —

Regional dynamics in the Commercial Vehicle Financing Market reflect differences in lender structure, freight intensity and regulation. Asia-Pacific leads on volume through a mix of Chinese state banks and Indian NBFCs, North America and Europe rely heavily on captive and leasing channels, and the Middle East & Africa grows fastest on the back of infrastructure-led fleet expansion.


North America

Country Key Metric Key Driver
US 81.5% share of region Captive finance depth, EPA 2027 pre-buy
Canada USD 3.9 Billion (2025) iMHZEV zero-emission incentives
Mexico 6.9% CAGR (2026–2035) Nearshoring freight and cross-border fleets

Captive lenders such as PACCAR Financial, Daimler Truck Financial Services and Volvo Financial Services finance a large portion of new Class 8 deliveries at the dealer desk, while banks and equipment-finance subsidiaries dominate mixed fleets. Credit unions and regional banks retain a foothold in small-ticket commercial auto loans for trades that run pickup-based vehicles. Canada's iMHZEV program offers up to CAD 200,000 per zero-emission heavy vehicle, supporting electric leases, and Mexico's nearshoring boom is lifting cross-border trucking demand and dollar-denominated fleet credit.


Europe

Country Key Metric Key Driver
Germany 23.8% share of region Largest truck parc, captive leasing depth
UK USD 4.4 Billion (2025) Contract hire and van leasing culture
France 15.2% share of region Low-emission zones in major cities
Italy USD 2.9 Billion (2025) Ageing fleet replacement
Spain 5.8% CAGR (2026–2035) Iberian logistics hub expansion
Nordic Countries 6.9% share of region Early electric truck adoption
Russia USD 1.4 Billion (2025) Domestic lessors after Western exit
Rest of Europe 12.4% share of region Central European manufacturing corridors

European fleets favour operating and finance leases, with Germany and the UK hosting large captive and bank-owned lessors. Regulation (EU) 2024/1610 forces a steep ramp in zero-emission truck purchases [3], while CRR3 raises capital costs for bank lenders [9]. Nordic countries lead electric truck adoption thanks to low-cost clean power. Russia's market has been largely closed to Western captives since 2022, leaving domestic leasing companies in control of new originations.


Asia-Pacific

Country Key Metric Key Driver
China 41.2% share of region Freight scale, electric truck deployment
India 7.4% CAGR (2026–2035) NBFC reach, PM E-DRIVE incentives
Japan USD 5.6 Billion (2025) Leasing-company dominance
South Korea 5.3% share of region Hydrogen and electric truck subsidies
ASEAN 6.9% CAGR (2026–2035) E-commerce logistics, low credit penetration
Rest of Asia-Pacific USD 2.8 Billion (2025) Mining and agricultural haulage in Australia

China anchors the Commercial Vehicle Financing Market in this region through state-bank credit and OEM finance companies serving the world's largest truck fleet. India's NBFCs extend credit to first-time owner-operators, and PM E-DRIVE incentives support electric buses and trucks [5]. Japan relies on leasing majors such as Mitsubishi HC Capital, while ASEAN economies show fast growth from low credit penetration.


South America

Country Key Metric Key Driver
Brazil 61.4% share of region BNDES Finame credit, agribusiness freight
Argentina USD 1.1 Billion (2025) Macroeconomic stabilization, fleet renewal
Rest of South America 5.2% CAGR (2026–2035) Mining and port logistics

Brazil's BNDES Finame lines provide subsidized long-tenor credit for domestically built trucks, supporting agribusiness haulage across soybean and sugar corridors. High policy rates in Brazil raise borrowing costs for independent truckers, while Argentina's inflation history keeps tenors short and down payments high. Chile, Colombia and Peru show steady demand tied to mining and port logistics.


Middle East & Africa

Country Key Metric Key Driver
Saudi Arabia 26.8% share of region National Transport and Logistics Strategy
UAE 7.3% CAGR (2026–2035) Port and free-zone logistics growth
South Africa USD 1.9 Billion (2025) Mature bank vehicle-finance books
Egypt 7.0% CAGR (2026–2035) Suez Canal Economic Zone logistics
Rest of MEA 24.1% share of region East African trade corridors

Gulf infrastructure programs make this the fastest-growing region in the Commercial Vehicle Financing Market. Saudi Arabia's logistics strategy [22] and UAE port and free-zone expansion drive structured fleet leases, while South Africa's banks run mature vehicle-finance books. Egypt's Suez Canal Economic Zone adds trucking demand, and East African corridors are opening to mobile-money-based lenders.


Commercial Vehicle Financing Market By Region, 2025-2035

Commercial Vehicle Financing Market Segmentation

By Provider Type

Across the Commercial Vehicle Financing Market, Banks lead with a 44.4% share, yet capital charges under Basel III final reforms are slowing their portfolio growth. NBFCs are the fastest-growing provider type at a 6.42% CAGR, winning informal owner-operators through alternative-data scoring. Captive Finance Arms generate USD 34.1 billion by bundling telematics, service and residual guarantees with new-vehicle sales. Credit Unions hold a smaller position built on relationship lending in North American niches.

Segment Key Metric Primary Demand Driver
Banks 44.4% share Large-fleet relationships, low deposit funding costs
Captive Finance Arms USD 34.1 Billion (2025) OEM telematics and bundled service contracts
NBFCs 6.42% CAGR (2026–2035) Alternative-data lending to informal operators
Credit Unions 5.7% share Relationship underwriting for local fleets


By Financing Type

Inside the Commercial Vehicle Financing Market, Loans hold a 60.7% share because owner-operators value outright ownership and equity build-up. Operating Lease is the fastest-growing product at a 6.50% CAGR, as fleets transfer residual-value risk to lessors and buy fleet leasing services bundled with maintenance. Finance Lease suits mid-size fleets seeking eventual ownership, while Credit Line remains a niche tool due to floating-rate exposure.

Segment Key Metric Primary Demand Driver
Loans 60.7% share Owner-operator preference for asset ownership
Finance Lease USD 22.8 Billion (2025) Mid-size fleets targeting eventual ownership
Operating Lease 6.50% CAGR (2026–2035) Residual-risk transfer, bundled maintenance
Credit Line 3.8% share Working-capital flexibility for large fleets


By Vehicle Condition

For the Commercial Vehicle Financing Market, New vehicles retain a 54.3% share, supported by captive programs and emission-driven replacement purchases. Used vehicle financing is the faster-growing condition segment at a 6.52% CAGR, as AI depreciation models and certified pre-owned programs reduce lender losses. Abundant off-lease inventory from earlier fleet expansions keeps supply of financeable used units strong.

Segment Key Metric Primary Demand Driver
New 54.3% share Captive programs, emission-norm replacement
Used 6.52% CAGR (2026–2035) Certified pre-owned programs, AI residual models


By Vehicle Type

Within the Commercial Vehicle Financing Market, LCV is both the dominant and fastest-growing vehicle type, holding a 42.9% share on the strength of parcel delivery, quick commerce and urban electrification mandates. Medium/Heavy Trucks deliver USD 44.6 billion with the largest ticket sizes, but slower unit growth as higher rates extend replacement cycles. Buses depend on public procurement, while Special-Purpose vehicles rely on bespoke project finance.

Segment Key Metric Primary Demand Driver
LCV 42.9% share E-commerce delivery, low-emission zones
Medium/Heavy Trucks USD 44.6 Billion (2025) Long-haul freight, emission-norm replacement
Buses 12.5% share Public transit electrification programs
Special-Purpose USD 10.0 Billion (2025) Construction, mining and municipal projects


By Channel

Throughout the Commercial Vehicle Financing Market, Direct origination leads with a 69.0% share through dealer desks, captive portals and bank relationship managers. Online Aggregators are the fastest-growing channel at a 6.55% CAGR, using AI underwriting and freight-invoice data to approve small fleets quickly. Broker-Assisted channels keep relevance for complex, multi-lender deals but face margin pressure from digital platforms.

Segment Key Metric Primary Demand Driver
Direct 69.0% share Dealer point-of-sale and captive portals
Online Aggregators 6.55% CAGR (2026–2035) AI underwriting, rapid approvals
Broker-Assisted 19.6% share Complex multi-lender fleet deals


Competitive Benchmarking

The Commercial Vehicle Financing Market is moderately fragmented, with an estimated Herfindahl-Hirschman Index below 1,000 and the top five lenders holding roughly 20–27% of global volume. Captive finance arms of truck OEMs lead in new heavy-truck origination, universal banks dominate large-fleet relationships, and regional NBFCs control informal segments in India and Southeast Asia. Competition centres on funding cost, data access and residual-value expertise.

Company Est. Revenue Share Range Key Offerings for Commercial Vehicle Financing Market Strategic Positioning
Daimler Truck Financial Services ~5–7% Loans, leases, connected service bundles Global captive leader across multiple truck brands
Volvo Financial Services ~4–6% Operating leases, usage-based contracts Captive with strong telematics integration
PACCAR Financial ~3–5% Retail loans, certified pre-owned finance Premium Class 8 captive in North America and Europe
Toyota Financial Services ~3–5% LCV loans and leases Captive strength in light commercial vehicles
Wells Fargo Equipment Finance ~3–5% Fleet loans, TRAC leases Large U.S. bank with national fleet coverage
Ally Financial ~2–4% Commercial vehicle loans, dealer floorplan Digital-first U.S. lender with dealer network
Bank of America ~2–4% Fleet and equipment finance Corporate relationship lending to large fleets
Shriram Finance ~2–3% Used and new CV loans India's largest CV-focused NBFC
BNP Paribas Leasing Solutions ~1–3% Operating and finance leases Pan-European vendor-finance partnerships
Mahindra Finance ~1–2% Rural and small-fleet CV loans Deep rural reach with GPS-based scoring


Recent News & Developments

  • Reserve Bank of India (November 2023): Raised risk weights on bank lending to NBFCs by 25 percentage points, increasing funding costs for vehicle-focused lenders and slowing disbursement growth [23]
  • U.S. EPA (March 2024): Finalized Phase 3 greenhouse-gas standards for heavy-duty vehicles, setting long-term demand signals for zero-emission truck financing [2]
  • European Union (May 2024): Adopted Regulation (EU) 2024/1610, locking in 45%, 65% and 90% CO2 reduction targets for new heavy-duty vehicles by 2030, 2035 and 2040 [3]
  • Ministry of Heavy Industries, India (September 2024): Approved the ₹10,900 crore PM E-DRIVE scheme covering electric buses, trucks and charging, expanding the pipeline for electric CV loans [5]
  • European Banking Authority (January 2025): CRR3 capital rules took effect across the EU, raising risk-weighted asset calculations for bank lenders [9]
  • Reserve Bank of India (February 2025): Reversed the 2023 risk-weight increase on bank lending to NBFCs effective April 2025, easing funding for CV-focused lenders [23]
  • U.S. Congress (July 2025): Enacted legislation ending the Commercial Clean Vehicle Credit for vehicles acquired after September 30, 2025, triggering a pre-deadline purchase wave [6]

Commercial Vehicle Financing Market Report Scope

Parameter Details
Market Scope Commercial Vehicle Financing Market covering loans, leases and credit lines provided by banks, captive finance arms, NBFCs and credit unions for new and used commercial vehicles
Study Period 2021–2035 (Historical: 2021–2024; Base Year: 2025; Forecast: 2026–2035)
CAGR 6.40% (2026–2035)
Market Size checkpoints USD 122.5 Billion (2025); USD 130.8 Billion (2026); USD 167.6 Billion (2030); USD 228.6 Billion (2035)
Fastest Growing Segments NBFCs (6.42% CAGR); Operating Lease (6.50% CAGR); Used (6.52% CAGR); Online Aggregators (6.55% CAGR); LCV
Companies Profiled Daimler Truck Financial Services, Volvo Financial Services, PACCAR Financial, Toyota Financial Services, Wells Fargo Equipment Finance, Ally Financial, Bank of America, Shriram Finance, BNP Paribas Leasing Solutions, Mahindra Finance
Valuation Currency USD Billion

FAQs

How does IFRS 16 affect the appeal of operating leases in the Commercial Vehicle Financing Market?
IFRS 16 requires lessees to record most leases on the balance sheet as right-of-use assets [24]. Fleets outside U.S. GAAP now choose operating leases for residual-risk transfer and bundled maintenance, not accounting optics.
What should a fleet operator compare when choosing between a captive lender and a bank?
Compare total contract cost, including bundled service, telematics and guaranteed buyback terms, not only the headline rate. Captive residual guarantees can remove refinancing risk at contract end.
Which risk indicators do lenders in the Commercial Vehicle Financing Market track for electric trucks?
Lenders track battery state-of-health, depot charging access and warranty transferability, since these set resale value [4]. Many now require telematics battery reports at origination and lease return.
How do battery-swap models change loan structures?
Swapping lets financiers fund the chassis and battery separately, cutting the operator's upfront ticket. The battery owner carries degradation risk and recovers costs through per-swap or per-kWh fees.
Can small fleets access sustainability-linked lending in the Commercial Vehicle Financing Market?
Access is widening but still favours fleets that can report verified emissions [17]. Some lenders accept telematics-derived fuel and mileage records as a lower-cost substitute for formal reporting.
How do lenders assess first-time owner-operators with no credit bureau history?
Lenders supplement thin bureau files with repayment data from fuel cards, toll accounts and mobile wallets. This alternative data can cut approval times to under a day.
Do used-truck buyers get the same loan tenors as new-truck buyers?
Usually not, because lenders cap tenors so loans end before assets reach roughly 10–12 years of age. Certified pre-owned programs with verified service records narrow that gap across the Commercial Vehicle Financing Market [20].
Author
Author Author Profile Abbas Raut LinkedIn Research Analyst
Abbas Raut is a Senior Research Analyst with 5+ years of experience delivering data-driven insights and strategic recommendations across the Automotive and Aerospace & Defense sectors. He specializes in emerging technologies, industry value chains, and global market dynamics shaping the future of mobility and defense. In automotive, Abbas has led studies on EVs, charging stations, BMS, superchargers, and more, guiding stakeholders through electrification and regulatory shifts. In Aerospace & Defense, he has analyzed markets for military electronics, drones, radars, and electronic warfare solutions, supporting procurement and investment strategies. With expertise in market sizing, forecasting, benchmarking, and technology adoption, Abbas is known for transforming complex datasets into actionable insights that drive strategy, innovation, and growth.
Co-Author Co-Author Profile Swapnil Palwe LinkedIn Team Lead - Research
With a technical background as Bachelor's in Mechanical Engineering, with MBA in Operations Management , Swapnil has 6+ years of experience in market research, consulting and analytics with the tasks of data mining, analysis, and project execution. He is the POC for our clients, for their consulting projects running under the Automotive/A&D domain. Swapnil has worked on major projects in verticals such as Aerospace & Defense, Automotive and many other domain projects. He has worked on projects for fortune 500 companies' syndicate and consulting projects along with several government projects.
Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.


















