Bioanalytical Testing Services Market (2026 - 2035)

Bioanalytical Testing Services Market Research Report: Size, Share, Trend Analysis By Types of Testing (DMPK testing, Biomarker testing, Virology testing, Serology testing, Immunogenicity testing), By Technology (Mass Spectrometry, Chromatography, Immunoassays, PCR), By Molecule Type (Small molecule, Large molecule), By Applications (Pharmaceuticals, Biotechnology, Clinical Research, Environmental Testing), By End Use (Pharmaceutical Companies, Contract Research Organizations, Academic Research Institutions) and By Regional (North America, Europe, South America, Asia-Pacific, Middle East and Africa) - Growth Outlook & Industry Forecast 2026 To 2035

Forecast Period
2026-2035
CAGR
9.6%
2025 Market Size
USD 4.55 Billion
2035 Market Size
USD 11.37 Billion
Life Sciences ● Updated August 27, 2026 Report ID: MRFR/LS/5111-CR | Pages: 100 | Author: Rahul Gotadki, Vikita Thakur

Bioanalytical Testing Services Market Summary

The Bioanalytical Testing Services Market was valued at USD 4.55 billion in 2025 and opens the forecast window at USD 4.98 billion in 2026, climbing to USD 11.37 billion by 2035 at a 9.6% CAGR. Two catalysts anchor that trajectory. The first is the steady migration of sponsor analytics out of fixed in-house laboratories: more than half of clinical study sample analysis now sits with specialist contract research organisations, and that share keeps climbing [1]. The second is regulatory convergence — the ICH M10 guideline on bioanalytical method validation, adopted across FDA, EMA and PMDA jurisdictions, has narrowed the gap between regional expectations and made cross-border study data far more portable [3].

Instrument estates are being rebuilt by laboratories. Automated liquid handlers, LIMS platforms, and high-resolution accurate-mass systems are replacing manual ELISA benches and single-quadrupole workhorses. These systems convert raw chromatograms into audit-ready datasets without the need for a technician to retype anything. The ten largest service providers collectively committed over USD 1.9 billion to laboratory capacity, automation, and digital infrastructure between 2023 and 2025, which has been followed by capital deployment. Method transfer cycles that were previously twelve weeks in duration are now completed in five.

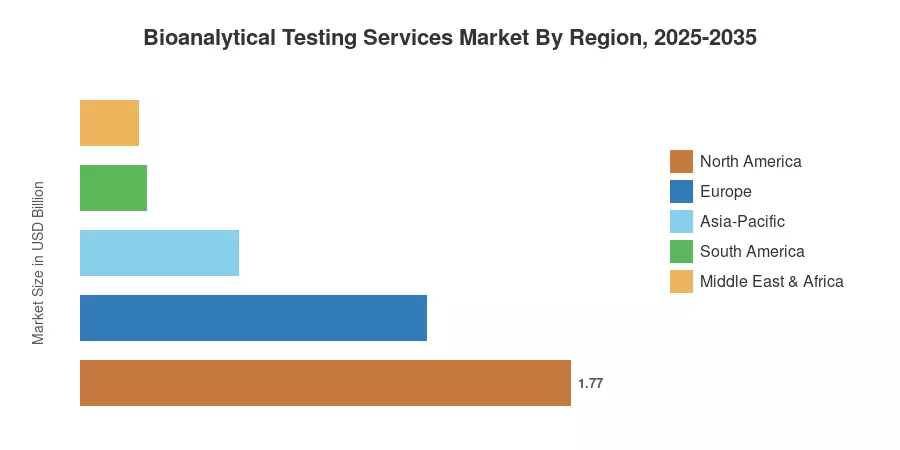
North America is the geographic location of 39.0% of 2025 revenue, which is supported by dense biotech concentration and NIH-funded trial volume. Chinese and Indian laboratories are acquiring regulated work outright rather than as low-cost overflow, resulting in a 12.6% increase in Asia-Pacific compounds through 2035. EMA biosimilar filings have propelled Europe to a second-place position at 27.5%. Providers who are capable of validating their claims once and defending them in five regulatory jurisdictions will be rewarded in the upcoming decade.


Key Report Takeaways

• By Molecule Type

  • Small molecules retained 59.8% of Bioanalytical Testing Services Market revenue in 2025, sustained by generic bioequivalence volume.
  • Large molecules are forecast to compound at 11.9% CAGR through 2035 as antibody-drug conjugates and bispecifics enter late-phase testing.

• By Test Type

  • Bioavailability and bioequivalence commanded 38.6% revenue share in 2025
  • Biomarker testing is projected to expand at 13.2% CAGR, the fastest of any test category
  • Pharmacokinetics contributed USD 1.02 billion in 2025

• By End User

  • Pharmaceutical companies accounted for 51.8% of demand in 2025
  • CDMOs are on track for a 13.9% CAGR between 2026 and 2035

• By Region

  • North America led the Bioanalytical Testing Services Market with a 39.0% revenue share in 2025
  • Asia-Pacific is set to grow at 12.6% CAGR through 2035
  • Europe generated USD 1.25 billion in 2025


Market Size and Forecast (2021–2035)

Estimates for the Bioanalytical Testing Services Market draw on service-line revenue disclosures from listed CROs, sponsor outsourcing budgets reported in annual filings, regulatory submission counts from FDA and EMA databases, and primary interviews with laboratory operations directors across four regions. Historical years are reconciled bottom-up against study volume; forecast years apply a demand model weighted by pipeline composition and outsourcing penetration.
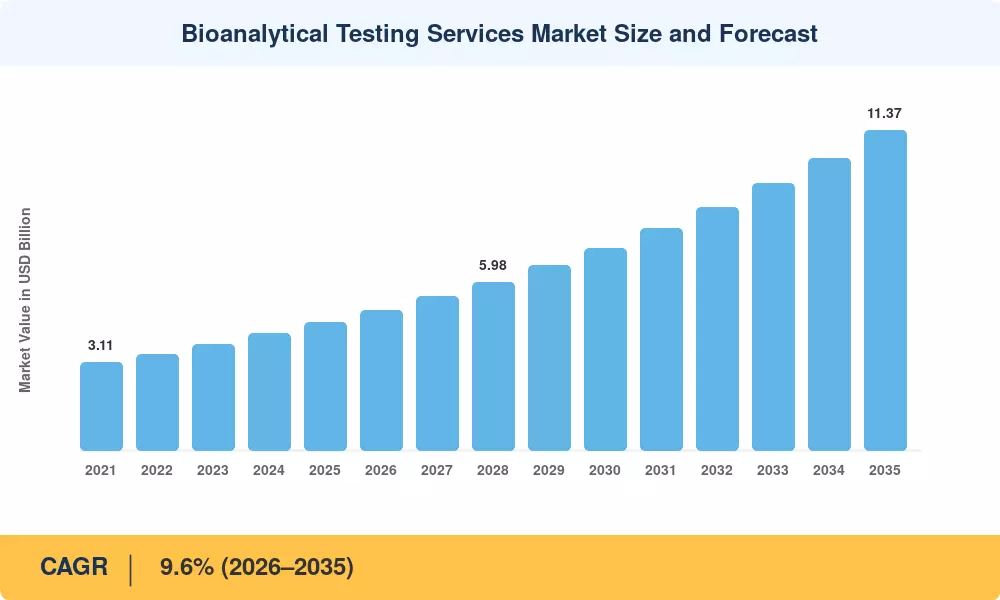
Bioanalytical Testing Services Market Size and Forecast
Our Impact
Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals
Partnering with 2000+ Global Organizations Each Year
30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Sponsor outsourcing of clinical study analytics +1.8 pp Global Medium-term (2–4 yr)
ICH M10 validation harmonisation +1.4 pp Global Short-term (≤2 yr)
Biologics and biosimilar pipeline expansion +1.6 pp North America, Europe, APAC Long-term (≥4 yr)
Cell and gene therapy trial volume +1.1 pp North America, Europe Long-term (≥4 yr)
Asia-Pacific regulated capacity build-out +1.0 pp Asia-Pacific Medium-term (2–4 yr)
Laboratory automation and high-resolution MS +0.8 pp Global Medium-term (2–4 yr)
Immunogenicity and biomarker data requirements +0.7 pp Global Short-term (≤2 yr)


Outsourcing Has Become Structural, Not Cyclical

Sponsors stopped treating external laboratories as surge capacity by 2022. Fixed-cost laboratory footprints carry depreciation that survives pipeline attrition, and corporate boards have taken notice. According to industry analyses, contract research organizations now manage nearly 75% of clinical trials. Large pharmaceutical sponsors routinely sign multiyear preferred-provider agreements covering method development through study close-out to secure operational bandwidth.


ICH M10 Rewrote the Compliance Baseline

Regulators finalized the ICH M10 bioanalytical harmonization guideline on May 24, 2022, with formal global enforcement timelines taking effect across member states by May 2023. A unified validation package now travels smoothly across the FDA, EMA, and PMDA review architectures. This standardization eliminates redundant multi-regional testing burdens, streamlining compliance baselines for regulated sample analysis worldwide under unified international standards.


Complex Modalities Demand Instrumentation Sponsors Will Not Buy

Antibody-drug conjugates require simultaneous quantification of intact conjugate, free payload, and total antibody—demanding three orthogonal assays on a single sample set. Biologics and advanced therapeutic modalities represent a vital portion of regulatory reviews, with the US FDA approving 50 novel products in 2024 and 46 novel drugs in 2025. Few sponsors justify owning the high-resolution mass spectrometry estate needed, driving service contracts.


Asia-Pacific Moved Up the Value Chain

Chinese and Indian laboratories no longer compete strictly on price. The National Medical Products Administration's alignment with ICH guidelines and India's modernized clinical trial regulatory rules have opened complex pivotal study work to domestic sites. Significant capital investments across the Asia-Pacific region continue to strengthen local bioanalytical infrastructure, supporting global trial execution under harmonized quality metrics and international standards.


Restraints Impact Analysis

Restraint impacts represent directional drag on the growth rate of the Bioanalytical Testing Services Market and are not additive to the CAGR figure.

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
Bioanalytical scientist shortage and wage inflation −0.9 pp Global Medium-term (2–4 yr)
Capital intensity of high-resolution MS platforms −0.7 pp Emerging markets Long-term (≥4 yr)
Data integrity findings and inspection risk −0.6 pp India, China Short-term (≤2 yr)
Pricing pressure from sponsor consolidation −0.5 pp North America, Europe Medium-term (2–4 yr)
Sample logistics and cold-chain fragility −0.4 pp Global Short-term (≤2 yr)


Talent Is the Binding Constraint

Validated method development depends heavily on experienced analysts. According to the US Bureau of Labor Statistics Occupational Outlook Handbook, employment for chemists and materials scientists spans tens of thousands of specialized roles, with median annual pay reaching USD 86,620. Providers face intense wage competition driven by persistent labor shortages. Automation supports laboratory throughput, but cannot replace expert troubleshooting for complex matrix-effect problems prior to database locks.


Inspection Risk Travels With the Sample

Regulatory findings at a single testing site can invalidate years of submitted data. Global health authorities like the US FDA and European Medicines Agency maintain strict data integrity enforcement protocols, issuing public warning letters and non-compliance notifications when electronic audit trails are compromised. Buyers now routinely audit electronic records architecture and data governance frameworks before approving service agreements to mitigate costly study re-analysis and severe regulatory delays.


Instrument Economics Exclude Smaller Entrants

A single high-resolution accurate-mass system with associated qualification runs USD 650,000 to USD 900,000 installed. Amortizing that heavy capital expenditure against regional study volume remains difficult outside the top tier of service providers. According to US Bureau of Labor Statistics industry profiles, testing laboratories house a significant share of technical personnel, reinforcing industry concentration among established networks with massive capital resources.


Bioanalytical Testing Services Market Opportunities

Decentralised and Microsampling Workflows

Volumetric absorptive microsampling cuts blood volume requirements by up to 90% and removes the frozen-plasma cold chain from the equation. Providers building validated microsampling assay libraries can serve paediatric, oncology and geriatric protocols that conventional venous draws struggle to support [8]. Adoption remains under 15% of eligible studies — the runway is long.

Biomarker and Precision-Medicine Assay Platforms

Companion diagnostic co-development creates recurring analytical demand that outlives the trial itself. Sponsors filing tissue-agnostic oncology indications need harmonised biomarker measurement across multiple tumour types, and few carry that capability internally [4].

Emerging-Market Regulated Capacity

Brazil's ANVISA and Saudi Arabia's SFDA have both expanded bioequivalence data requirements for local registration, creating demand for in-country accredited laboratories where almost none exist at scale [15] [17]. First-movers capture registration-driven volume with limited competition.

Data Monetisation Through Federated Assay Libraries

Providers sit on decades of validated method parameters, matrix stability profiles and inter-laboratory reproducibility data. Licensing anonymised method-performance libraries as subscription products converts a sunk archive into recurring revenue — several top-tier laboratories piloted this model in 2025 [16].

Integrated Discovery-to-Clinic Service Bundles

Sponsors increasingly buy one contract covering discovery screening through registrational pharmacokinetic bioanalysis. Bundling reduces method transfer risk and locks in the provider for the full asset lifecycle.


Bioanalytical Testing Services Market Future Outlook

Machine Learning Moves Into Method Development

Algorithmic prediction of chromatographic conditions and matrix interference is compressing method development from weeks to days. Early deployments at top-tier laboratories reported 30–40% reductions in development runs during 2025 pilots [16]. Regulators have signalled openness provided the underlying validation remains empirical.

Sample Volume Shrinks, Assay Sensitivity Rises

Microsampling and dried-blood-spot workflows are expanding rapidly to support decentralized trials, with the global microsampling devices market valued at USD 2 billion and projected to reach USD 3.6 billion. Providers validating these platforms early secure a defensible technical moat, meeting rising global clinical demand for patient-centric sampling methodologies across pediatric, geriatric, and remote investigations worldwide.


Platform Economics Reshape Contracting

Preferred-provider agreements are lengthening as pharmaceutical sponsors seek operational stability. Industry market evaluations indicate that the broader global clinical trials outsourcing market has expanded past USD 54 billion, with major drug developers increasingly concentrating outsourced bioanalytical workflows among select, trusted multi-site laboratory networks to streamline complex, multi-phase clinical study pipelines successfully.


Sustainability Reporting Reaches the Laboratory

European Sustainability Reporting Standards (ESRS) and Plan Be Eco: CSRD / DMA for Healthcare — Guide 2026 emphasize sustainability. The United Nations Environment Programme (UNEP) provides the foundational framework for managing pharmaceutical pollution and chemical waste, which informs the environmental criteria used in these life-cycle assessments.


Solvent consumption, single-use plastics, and ultra-low-temperature storage carry measurable environmental footprints. Aligned with global climate reporting frameworks and the EU Corporate Sustainability Reporting Directive mandating comprehensive Scope 3 value chain disclosure, pharmaceutical sponsors now actively evaluate and score bioanalytical laboratory bidding proposals based on verified greenhouse gas data quality and sustainable practices.


Bioanalytical Testing Services Market Segmentation

By Molecule Type

Segment Metric Primary Demand Driver
Small Molecules 59.8% revenue share (2025) Generic bioequivalence and oral oncology
Large Molecules 11.9% CAGR (2026–2035) Antibody-drug conjugates, bispecifics


Small molecules still pay the bills across the Bioanalytical Testing Services Market. Patent expiries feed a steady stream of bioequivalence studies that require reliable, high-throughput quantification rather than technical novelty. Large molecules tell the growth story: ligand-binding assay development for a bispecific antibody routinely runs three to four times the cost of a comparable small-molecule method, and immunogenicity assessment adds a mandatory second workstream.

By Test Type

Segment Metric Primary Demand Driver
Bioavailability & Bioequivalence 38.6% revenue share (2025) Generic registration filings
Pharmacokinetics USD 1.02 Billion (2025) Dose-selection and bridging studies
Pharmacodynamics 9.8% revenue share (2025) Target engagement confirmation
Biomarker Testing 13.2% CAGR (2026–2035) Precision-medicine stratification
Immunogenicity / ADA Testing USD 0.34 Billion (2025) Biologics regulatory requirement
Method Development & Validation 8.1% revenue share (2025) ICH M10 compliance workload
Other Test Types USD 0.13 Billion (2025) Stability and metabolite profiling


Bioequivalence remains the volume anchor of the Bioanalytical Testing Services Market, though pricing is commoditised and margins thin. Biomarker testing runs the opposite economics — bespoke, scientifically demanding, and priced accordingly. Sponsors pursuing stratified indications need assays qualified to fit-for-purpose standards well before pivotal enrolment, which pulls spend earlier in the development timeline.

By End User

Segment Metric Primary Demand Driver
Pharmaceutical Companies 51.8% revenue share (2025) Large late-stage portfolios
Biopharmaceutical & Biotech Firms USD 1.13 Billion (2025) Venture-funded pipeline expansion
CDMOs 13.9% CAGR (2026–2035) Integrated manufacture-plus-analysis offers
Contract Research Organisations 6.4% revenue share (2025) Subcontracted specialty assays
Academic & Research Institutes USD 0.16 Billion (2025) Translational grant-funded studies
Other End Users 3.1% revenue share (2025) Government and public health programmes


Pharmaceutical majors dominate spending in the Bioanalytical Testing Services Market simply because they run the most late-phase studies. CDMOs are the interesting movement: as manufacturing partners absorb release testing and comparability work, they increasingly bundle clinical sample bioanalysis into the same contract, capturing scope that previously went to standalone laboratories.


Regional Market Share Analysis

Region Metric Primary Investment Themes
North America 39.0% revenue share (2025) Automation retrofit, cell and gene therapy assays
Europe USD 1.25 Billion (2025) Biosimilar comparability, EU CTR compliance
Asia-Pacific 12.6% CAGR (2026–2035) Regulated capacity build-out, ICH alignment
South America 5.2% revenue share (2025) Bioequivalence registration volume
Middle East & Africa USD 0.21 Billion (2025) Sovereign biotech funds, local manufacturing
Total USD 4.55 Billion (2025)

Regional performance in the Bioanalytical Testing Services Market tracks two variables: local clinical trial density and the maturity of the domestic regulatory inspectorate.


North America

Country Share of Region (2025) Key Driver
US 84.1% NIH-funded trial density, biotech clustering
Canada 10.4% CIHR grants, Toronto–Montreal assay hubs
Mexico 5.5% Nearshored bioequivalence capacity


North America anchors the Bioanalytical Testing Services Market through sheer pipeline depth. The FDA reviewed 50 novel therapeutics in 2024, each carrying multi-year analytical obligations [5]. Massachusetts and North Carolina host the densest laboratory clusters, and both states extended life-science tax credits through 2028 [18]. Canada's contribution skews toward early-phase pharmacokinetic work.

Europe

Country Metric Key Driver
Germany USD 0.29 Billion (2025) Biosimilar comparability programmes
UK 18.6% share of region MHRA international recognition route
France 13.1% share of region France 2030 health innovation funding
Italy USD 0.11 Billion (2025) Generic bioequivalence volume
Spain 7.4% share of region Clinical trial recruitment competitiveness
Nordic Countries 10.8% CAGR (2026–2035) Registry-linked biomarker studies
Russia 3.2% share of region Domestic substitution policy
Rest of Europe USD 0.09 Billion (2025) CEE cost-competitive laboratories


Europe's position in the Bioanalytical Testing Services Market rests on biosimilar economics. The EU approved 19 biosimilars in 2024, each requiring comparability assay packages spanning pharmacokinetics and immunogenicity [6]. The Clinical Trials Regulation's single-submission portal reduced administrative drag but raised documentation standards.

Asia-Pacific

Country Metric Key Driver
China 34.8% share of region NMPA ICH alignment, domestic biotech pipeline
India 14.2% CAGR (2026–2035) Generic export bioequivalence demand
Japan USD 0.21 Billion (2025) PMDA ethnic-bridging study requirements
South Korea 9.6% share of region Biosimilar manufacturing scale
ASEAN USD 0.08 Billion (2025) Singapore and Malaysia laboratory hubs
Rest of Asia-Pacific 4.1% share of region Australia early-phase tax incentive


Asia-Pacific delivers the steepest growth curve in the Bioanalytical Testing Services Market. China's NMPA accepted 1,240 IND applications in 2024, roughly triple the 2019 count [9]. India's laboratories cleared 68 FDA inspections during 2024 with no official action indicated, a credibility milestone that unlocked pivotal-study awards previously routed to Western sites [2].

South America

Country Share of Region (2025) Key Driver
Brazil 61.3% ANVISA bioequivalence registration mandate
Argentina 19.7% Regional generic manufacturing base
Rest of South America 19.0% Chile and Colombia trial recruitment


Brazil dominates regional demand within the Bioanalytical Testing Services Market. ANVISA's RDC 742/2022 tightened bioequivalence documentation for generic registration, and domestic laboratories added roughly 340 validated methods between 2023 and 2025 to absorb the workload [15].

Middle East & Africa

Country Metric Key Driver
Saudi Arabia 33.4% share of region Vision 2030 biotech localisation
UAE USD 0.05 Billion (2025) Free-zone laboratory investment
South Africa 21.8% share of region SAHPRA-accredited trial infrastructure
Egypt 11.2% share of region Regional generic manufacturing
Rest of MEA 9.9% share of region Nascent regulatory frameworks


Saudi Arabia leads the smallest regional slice of the Bioanalytical Testing Services Market. The National Biotechnology Strategy committed USD 3.4 billion through 2030, with laboratory accreditation among its stated pillars [17]. Execution risk remains high — accredited analyst headcount is the constraint, not capital.


Bioanalytical Testing Services Market By Region, 2025-2035

Competitive Benchmarking

Concentration in the Bioanalytical Testing Services Market sits at the low end of moderate. Market Research Future estimates a Herfindahl-Hirschman Index near 690, with the top five providers holding a combined 38–44% of global revenue. The remainder is genuinely fragmented — several hundred regional laboratories serve local bioequivalence and academic demand. Differentiation now runs on regulatory track record and multi-site redundancy rather than unit price.

Company Est. Revenue Share Range Key Offerings for Bioanalytical Testing Services Market Strategic Positioning
Labcorp Drug Development ~11–14% Regulated LC-MS/MS, immunogenicity, biomarker panels Scale leader with integrated central lab network
Thermo Fisher Scientific (PPD) ~8–11% Large-molecule bioanalysis, cell and gene therapy assays Instrument-plus-services vertical integration
Charles River Laboratories ~6–9% Discovery and preclinical DMPK, safety bioanalysis Early-phase specialist with discovery pull-through
IQVIA Laboratories ~5–8% Central laboratory, biomarker and companion diagnostics Data-linked analytics differentiation
Eurofins Scientific ~5–7% Method development, bioequivalence, stability testing Broad European site footprint
ICON plc ~4–6% Clinical sample analysis, immunoassay services Full-service CRO bundling
SGS SA ~3–5% Bioanalysis, biosafety, regulated method validation Accreditation-led quality positioning
WuXi AppTec ~3–5% Integrated discovery-to-clinic analytical services Asia-Pacific cost and speed advantage
Frontage Laboratories ~2–4% Regulated bioanalysis, biomarker assay development Mid-market agility, US–China dual footprint
Altasciences ~2–3% Early-phase pharmacokinetics, immunoanalytical services Phase I-plus-lab integrated model
Pharmaron ~2–3% Preclinical and clinical bioanalysis Cross-border regulated capacity


Recent News & Developments

Selected developments shaping the Bioanalytical Testing Services Market:

  • SGS (June, 2026) – Acquired CMIC, INC., a Chicago-based bioanalytical testing provider, strengthening North American GLP-compliant capabilities across preclinical and clinical drug-development phases.
  • SGS (May, 2026) – Acquired Keystone Bioanalytical, a Philadelphia-based LC-MS/MS specialist, expanding GLP-compliant bioanalysis capabilities supporting small and large molecule drug-development programs.
  • Agilent Technologies & Veeda Lifesciences (May, 2026) – Launched a joint Analytical Center of Excellence in Bengaluru, combining mass spectrometry with bioanalytical workflows for GLP-1 and complex biologics.


Bioanalytical Testing Services Market Report Scope

Parameter Detail
Market Scope Global bioanalytical testing services across molecule type, test type, end user and geography
Study Period 2021–2035 (Historical 2021–2024; Base Year 2025; Forecast 2026–2035)
CAGR 9.6% (2026–2035)
Market Size Checkpoints USD 4.55 Billion (2025); USD 4.98 Billion (2026); USD 11.37 Billion (2035)
Fastest Growing Segments Large molecules (11.9% CAGR); Biomarker testing (13.2% CAGR); CDMOs (13.9% CAGR); Asia-Pacific (12.6% CAGR)
Companies Profiled Labcorp Drug Development, Thermo Fisher Scientific (PPD), Charles River Laboratories, IQVIA Laboratories, Eurofins Scientific, ICON plc, SGS SA, WuXi AppTec, Frontage Laboratories, Altasciences, Pharmaron
Valuation Currency USD Billion

FAQs

What should sponsors audit before awarding a contract in the Bioanalytical Testing Services Market?
Prioritise electronic audit trail architecture, inspection history over five years, and analyst turnover rates. Instrument inventory matters less than documented method transfer success. Request incurred sample reanalysis performance data before shortlisting [2].
Which contract structure protects buyers on multi-year programmes?
Unit-priced sample contracts expose sponsors to volume risk; capacity reservation agreements with volume bands work better for late-phase programmes. Build method transfer costs into the base rate rather than treating them as change orders [10].
When does insourcing beat outsourcing for a mid-size biotech?
Rarely before three concurrent late-phase assets. Below that threshold, instrument depreciation and qualification overhead exceed external pricing. Discovery-stage screening is the exception where speed justifies internal capability [11].
How do ligand-binding assays compare with mass spectrometry in the Bioanalytical Testing Services Market?
Ligand-binding offers superior sensitivity for intact biologics but suffer reagent-lot variability. Mass spectrometry delivers structural specificity and better multiplexing. Antibody-drug conjugate programmes typically need both, run orthogonally [11].    
Which emerging use cases will reshape the Bioanalytical Testing Services Market after 2030?
Radioligand therapy dosimetry support and in vivo gene editing biodistribution assays are the two clearest. Both require capabilities almost no laboratory has validated at regulated scale today [7].        
Author
Author
Author Profile
Rahul Gotadki LinkedIn Research Manager
He holds an experience of about 9+ years in Market Research and Business Consulting, working under the spectrum of Life Sciences and Healthcare domains. Rahul conceptualizes and implements a scalable business strategy and provides strategic leadership to the clients. His expertise lies in market estimation, competitive intelligence, pipeline analysis, customer assessment, etc.
Co-Author
Co-Author Profile
Vikita Thakur LinkedIn Senior Research Analyst
She holds an experience of about 5+ years in market research and business consulting projects for sectors such as life sciences, medical devices, and healthcare IT. She possesses a robust background in data analysis, market estimation, competitive intelligence, pipeline analysis market trend identification, and consumer behavior insights. Her expertise lies in technical Sales support, client interaction and project management, designing and implementing market research studies, conducting competitive analysis, and synthesizing complex data into actionable recommendations that drive business growth.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of regulatory databases, peer-reviewed pharmaceutical journals, clinical trial registries, and authoritative health organizations. Key sources included the US Food & Drug Administration (FDA) Guidance for Industry documents, European Medicines Agency (EMA) Bioanalytical Method Validation guidelines, International Council for Harmonisation (ICH) M10 Bioanalytical Method Validation standards, ClinicalTrials.gov registry, Drug Information Association (DIA) publications, American Association of Pharmaceutical Scientists (AAPS) Journal, Bioanalysis Journal (Future Science Group), Molecular Pharmaceutics, Analytical and Bioanalytical Chemistry, National Institutes of Health (NIH) RePORTER database, Centers for Medicare & Medicaid Services (CMS) for laboratory billing codes, World Health Organization (WHO) International Nonproprietary Names (INN) database, Organisation for Economic Co-operation and Development (OECD) Test Guidelines, and national health ministry reports from key markets. These sources were used to collect clinical trial statistics, regulatory validation requirements, bioanalytical laboratory accreditation data, outsourcing trends, and competitive intelligence for ADME testing, pharmacokinetic analysis, biomarker quantification, and biopharmaceutical development workflows.


Primary Research

Qualitative and quantitative insights were obtained by interviewing supply-side and demand-side stakeholders during the primary research process. The supply-side sources consisted of CEOs, VPs of Service Development, quality assurance leaders, and business unit directors from contract research organizations (CROs), central bioanalytical laboratories, and specialty testing service providers. The demand-side sources included Chief Scientific Officers, Heads of Drug Metabolism and Pharmacokinetics (DMPK), Clinical Operations Directors, and procurement representatives from biopharmaceutical companies, biotechnology firms, and academic medical centers. Service segmentation was validated across mass spectrometry and chromatography platforms, theranostic pipeline timelines were confirmed, and insights were garnered on outsourcing adoption patterns, pricing structures for regulated bioanalysis, and laboratory capacity utilization rates through primary research.

Primary Respondent Breakdown:

By Designation: C-level Executives (28%), Director Level (42%), Others (30%)

By Region: North America (38%), Europe (24%), Asia-Pacific (28%), Rest of World (10%)


Market Size Estimation

Global market valuation was derived through revenue mapping and study volume analysis. The methodology included:

Identification of 50+ key service providers across North America, Europe, Asia-Pacific, and Latin America

Service mapping across ADME testing, pharmacokinetic analysis, bioavailability studies, biomarker testing, and other regulated bioanalytical services

Analysis of reported and modeled annual revenues specific to bioanalytical testing portfolios

Coverage of service providers representing 75-80% of global market share in 2024

Extrapolation using bottom-up (clinical study volume × average selling price by phase/therapeutic area) and top-down (service provider revenue triangulation) approaches to derive segment-specific valuations for mass spectrometry, chromatography, immunoassays, and polymerase chain reaction (PCR) technologies

Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.
















