Atomic Clock Market (2026 - 2035)

Atomic Clock Market Size, Share, Industry Trend & Analysis Research Report By Type (Rubidium, Cesium, Hydrogen Maser), By End User (Defence, Space, Civil and Commercial), By Application (Navigation, Surveillance, Electronic Warfare, Telecommunication, Financial Trading and Data Centers, Broadcast and Media, Other Applications), By Region (North America, Europe, Asia-Pacific, South America, Middle East & Africa) - Forecast to 2035.
ID: MRFR/AD/29796-HCR 128 Pages Shubham Munde, Sejal Akre Last Updated: September 17, 2026
Atomic Clock Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)5.82%
2025 Market SizeUSD 700.5 Million
2035 Market SizeUSD 1,233.9 Million
Key Players
Microchip Technology Inc.
Safran
Adtran
Frequency Electronics Inc.
VREMYA-CH JSC
Excelitas Technologies
Opportunities
  • Timing-as-a-Service for the Mid-Market
  • Emerging-Market GNSS Augmentation
  • Data-Centre Timing as a Monetisable Layer

Atomic Clock Market Summary

The Atomic Clock Market closed 2025 at USD 700.5 Million, opens the forecast window at USD 741.6 Million in 2026, and is projected to reach USD 1,233.9 Million by 2035 at a 5.82% CAGR. Two catalysts anchor that trajectory. The first is sovereign resilience spending on positioning, navigation, and timing — the U.S. National Timing Resilience and Security Act and its successor appropriations have pushed federal agencies toward terrestrial timing backups that no longer depend solely on satellite broadcast [1][5]. The second is regulatory: financial venues in the EU and the U.S. now operate under microsecond-class timestamp obligations that make a disciplined laboratory reference a compliance asset rather than an engineering luxury [11][12].

Beneath those headline numbers, a quieter substitution is reshaping the Atomic Clock Market. Rack-mounted quartz ensembles and older GNSS-disciplined oscillators are giving way to rubidium and miniature beam-tube references embedded directly in base stations, substations and trading racks. The European Space Agency's Galileo Second Generation programme alone carries a payload budget in excess of EUR 1.47 billion, a meaningful share of which flows to onboard frequency standards and time-transfer hardware [4].

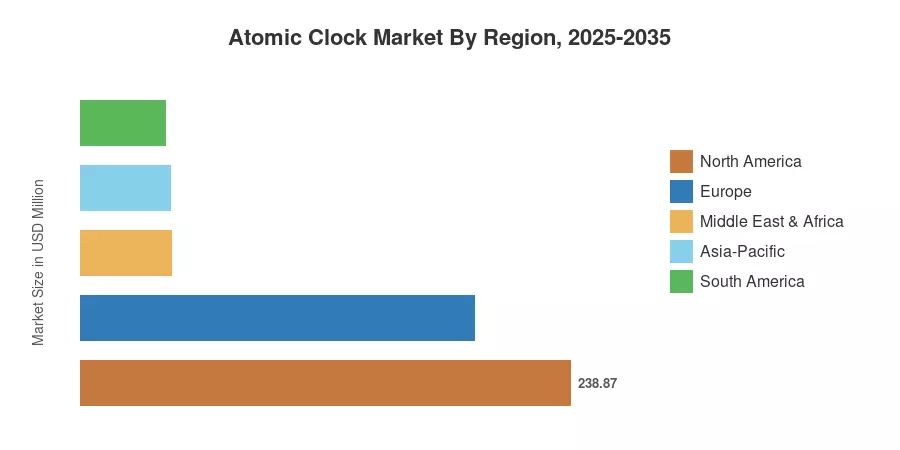
Regionally, North America holds 34.1% of the Atomic Clock Market in 2025 on the strength of defence and capital-markets demand. Asia-Pacific is the growth engine at a 6.28% CAGR, driven by BeiDou expansion, India's NavIC augmentation and Japanese optical metrology programmes . Europe follows as the second-largest region at 27.4%, supported by Galileo, national metrology institutes and a dense telecom synchronisation base. Expect the gap between the top two regions to narrow materially before 2032.


Key Report Takeaways

• By Technology

  • Cesium-based frequency standards led the Atomic Clock Market with a 43.3% share in 2025, retaining primacy in national primary reference roles
  • Rubidium standards generated USD 251.6 million in 2025 as size, weight and power constraints pushed designers toward compact references
  • Hydrogen maser systems are forecast to expand at a 5.21% CAGR through 2035 on radio-astronomy and satellite ground-segment demand

• By Sector

  • Civil and commercial deployments accounted for 48.8% of the Atomic Clock Market in 2025, the largest end-user block
  • Space applications are projected to grow fastest at a 6.56% CAGR as constellation refresh cycles compress
  • Defence procurement contributed USD 234.0 Million in 2025, concentrated in electronic warfare and GPS-denied navigation programmes

• By Region

  • North America held 34.1% of the Atomic Clock Market in 2025, anchored by federal timing infrastructure
  • Asia-Pacific is set to record the highest regional CAGR at 6.28% through 2035
  • Europe generated USD 191.9 million in 2025, with Germany and the United Kingdom the two deepest national pools


Market Size and Forecast (2021–2035)

Historical values were reconstructed from customs-level trade flows for frequency-standard subheadings, national metrology institute procurement disclosures, satellite payload contract awards and the segment reporting of listed timing vendors. Forecast years apply a demand-side build across four installed-base pools — telecom synchronisation nodes, GNSS payloads, defence platforms and financial-infrastructure racks — cross-checked against announced constellation replenishment schedules.
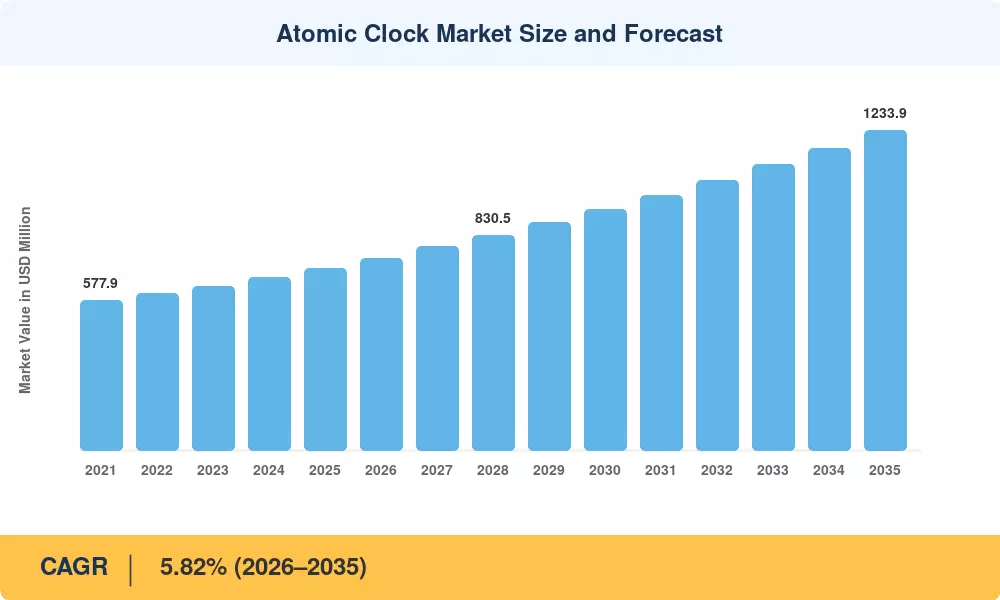
Atomic Clock Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
GNSS modernisation and sovereign constellation programmes +1.25 Global Long-term (≥4 yr)
Telecom phase-synchronisation obligations (5G-Advanced, O-RAN) +1.10 Asia-Pacific, Europe Medium-term (2–4 yr)
Defence PNT resilience and GPS-denied operations funding +0.95 North America, Europe Medium-term (2–4 yr)
Financial timestamp compliance regimes +0.85 North America, Europe Short-term (≤2 yr)
Miniaturisation economics in low-power references +0.70 Global Long-term (≥4 yr)
Hyperscale data-centre timing infrastructure +0.55 North America, Asia-Pacific Medium-term (2–4 yr)
Optical standards and redefinition of the SI second +0.40 Europe, Asia-Pacific Long-term (≥4 yr)


Sovereign Navigation Programmes Convert Policy Into Payload Orders

Galileo Second Generation, BeiDou-3 augmentation and NavIC’s L1 enlargement have one procurement characteristic in common: each satellite carries redundant frequency references. And any change in launch cadence feeds straight through to order books. The European Union has earmarked EUR 9.0 billion for its space program for 2021–2027, including the single greatest commitment for Galileo and EGNOS [4]. The Department of Space, India, has approved a follow-on NavIC series which takes the constellation to eleven satellites, each specified with domestic rubidium references .


Telecom Synchronisation Moves From Nice-to-Have to Contractual

Time-division duplex 5G networks can tolerate some ±1.5 microseconds phase error at the air interface, while coordinated features like carrier aggregation constrain that budget further [9]. Operators that formerly required a single GNSS antenna at each site are now requesting holdover-capable references at aggregation nodes. The ITU-R and 3GPP synchronization profiles have essentially encoded a hardware requirement into network design regulations, and procurement documents in Japan, South Korea, and Germany increasingly specify holdover length explicitly [7][9].


Defence Budgets Reward Assured Timing

Assured PNT has moved from a research line to a fielded requirement due to jamming and spoofing occurrences logged throughout Eastern European and Middle Eastern airspace. PNT modernization activities surpassing USD 2.1 billion across the services, with a designated portion for onboard frequency references and time-transfer modules was mentioned in the U.S. Department of Defense budget papers for FY2025 [5][6]. This emphasis has been echoed in national procurement programs by NATO countries.


Capital Markets Buy Traceability, Not Just Accuracy

MiFID II RTS 25 mandates high-frequency trading venues to timestamp to 100 microseconds of UTC with documented traceability, while the U.S. Consolidated Audit Trail imposes equivalent responsibilities on reporting members [11][12]. Compliance is as much an audit exercise as an engineering one, and this favors references that ship with calibration certifications and ongoing surveillance, a specification bias that has boosted average selling prices in the financial-infrastructure channel.


Restraints Impact Analysis

Restraint weightings are directional drags applied to the same analyst scoring framework used in Section 4. They represent friction on adoption velocity rather than deductions from the forecast CAGR, and several interact — cost sensitivity, for instance, amplifies substitution risk.

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
High unit cost and extended procurement cycles −0.80 Global Medium-term (2–4 yr)
Substitution by GNSS-disciplined oscillators at the low end −0.65 Global Medium-term (2–4 yr)
Export control and dual-use licensing friction −0.55 North America, Europe Short-term (≤2 yr)
Beam-tube supply chain and specialist labour scarcity −0.45 Global Long-term (≥4 yr)
Installed-base inertia and 15–20 year replacement cycles −0.35 Global Long-term (≥4 yr)


Price Points Still Gate the Mid-Market

A laboratory-grade primary reference regularly comes in at between USD 45,000 and USD 90,000/unit before integration, while a disciplined quartz alternative is an order of magnitude lower [14]. That delta dictates the project for a regional utility or a Tier 3 operator. Procurement cycles worsen the problem: Across Europe, the average public-sector timing award takes between eleven and sixteen months from tender to contract, pushing revenue recognition well past the budget year in which the demand emerges.


Good-Enough Alternatives Compress the Entry Tier

Modern GNSS disciplined oscillators with extended holdover firmware now provide stability suitable for a considerable proportion of enterprise synchronization needs. Purchasers will reasonably opt out of the premium where a network can sustain a few microseconds of drift over a day. This ceiling on entry-tier penetration is true, but erodes when jamming incidents make satellite-dependent holdover look less like a deal [9].


Supply Chains Are Thin by Design

Cesium beam tube manufacture depends on a small number of qualified facilities and a shrinking pool of technicians with vacuum-physics experience. Lead times of nine to fourteen months were common through 2024–2025, and vendors have responded by lengthening quoted delivery windows rather than expanding capacity [19]. Export licensing for dual-use timing hardware adds a further two to five months on cross-border defence-adjacent orders .


Atomic Clock Market Opportunities

Timing-as-a-Service for the Mid-Market

Subscription time distribution over fibre and dedicated terrestrial links lets buyers rent traceability instead of owning hardware. National metrology institutes in the UK and Germany already operate fibre time-transfer links exceeding 700 km, and commercial resellers are packaging those feeds for financial and telecom clients [3][20]. The model converts a capital objection into an operating line item and directly attacks the restraint identified in.

Emerging-Market GNSS Augmentation

Southeast Asia, the Gulf and Brazil are building augmentation and monitoring infrastructure without legacy installed bases to defend. Indonesia, Vietnam and Saudi Arabia have each announced national CORS or timing-reference programmes since 2023, creating greenfield demand where specification decisions are still open [21]. Vendors that win reference-design status early capture the refresh cycle for two decades.

Data-Centre Timing as a Monetisable Layer

Hyperscale operators increasingly sell timing accuracy as a tenant-facing feature, with cloud providers publishing microsecond-class clock-error bounds in service documentation [15][16]. That transforms a facility cost into a differentiated product tier and creates a repeatable, non-defence revenue pool for reference vendors — an important diversification given the Atomic Clock Market's historical concentration in government budgets.

Optical Clock Commercialisation

Optical lattice and ion standards have demonstrated fractional uncertainties near 1 × 10⁻¹⁸ in national laboratories. First-mover suppliers of ruggedised, rack-mountable optical references stand to reset the premium tier of the technology stack.

Space-Qualified Miniature References

Constellation operators planning hundreds of satellites cannot afford flagship-class references on every bus. Demand is consolidating around space-qualified rubidium and chip-scale units with sub-watt draw, a niche where qualification heritage is the barrier to entry rather than raw performance [4][13].


Atomic Clock Market Future Outlook

Autonomy Raises the Floor on Timing Requirements

Autonomous vehicles, port automation and unmanned aviation all fail unsafely when timing degrades. The FAA and EASA have both flagged GNSS interference as an operational risk category, and airport-adjacent spoofing reports rose sharply through 2024–2025 [1][22]. As certification frameworks mature, onboard and infrastructure-side holdover will migrate from optional to mandated — a structural, non-cyclical demand floor for the Atomic Clock Market.

Platform Economics Favour Integrated Time Stacks

Buyers increasingly purchase a synchronisation outcome rather than a component. Vendors bundling references with time-transfer software, monitoring dashboards and calibration services capture materially higher attach revenue than hardware-only suppliers. Expect consolidation as pure-play component makers pair with network-management software firms.

Grid Modernisation Creates a Second Large Civil Pool

Synchrophasor deployment continues to expand, and the International Energy Agency projects global grid investment must reach roughly USD 600 billion annually by 2030 to meet electrification targets [23]. Wide-area monitoring depends on microsecond-aligned measurement across substations, which pulls precision references into a utility budget line that historically ignored them entirely.

Redefinition of the Second Resets the Premium Tier

Work under the CIPM toward an optical redefinition of the SI second is scheduled for consideration around 2030 [2][3]. When it lands, national laboratories will re-anchor their traceability chains, and a replacement wave will follow through calibration hierarchies.


Regional Market Share Analysis

Region Metric (2025) Primary Investment Themes
North America 34.1% share Federal timing resilience, capital-markets compliance, defence PNT
Europe USD 191.9 Million Galileo G2, metrology institutes, telecom synchronisation
Asia-Pacific 6.28% CAGR (2026–2035) BeiDou and NavIC expansion, optical metrology, 5G-Advanced
South America 5.9% share GNSS monitoring stations, broadcast timing, mining telemetry
Middle East & Africa USD 44.2 Million Sovereign PNT programmes, smart-grid synchronisation
Total USD 700.5 Million —

Regional demand in the Atomic Clock Market splits along a clear line: mature markets buy for resilience and compliance, while growth markets buy to build capability they never previously owned. That distinction explains why North America leads on installed value while Asia-Pacific leads on growth rate. The table below discloses a single calibrated metric per region.


North America

Country Metric Key Driver
US 82.4% of region Federal PNT resilience mandates and exchange timestamp rules
Canada USD 26.3 Million Defence communications and northern navigation infrastructure
Mexico 5.42% CAGR Telecom network densification and broadcast modernisation


Federal policy does most of the work here. Executive Order 13905 obliged U.S. agencies to identify and mitigate dependence on satellite timing, and the resulting agency plans have translated into terrestrial reference procurement across transportation, energy and communications [1][5]. Exchange operators in New Jersey and Chicago run their own reference chains to satisfy audit-trail obligations [12]. Canada's contribution skews defence and Arctic communications, while Mexico's growth is telecom-led rather than government-led.

Europe

Country Metric Key Driver
Germany 22.8% of region National metrology programmes and industrial synchronisation
UK USD 33.9 Million Financial timestamp compliance and resilient timing trials
France 5.71% CAGR Space payload manufacturing and defence programmes
Italy 8.4% of region Radio astronomy and satellite ground segment
Spain USD 12.5 Million Galileo ground infrastructure and telecom rollout
Nordic Countries 6.02% CAGR Grid synchronisation and subsea communications
Russia 7.2% of region GLONASS payload and domestic reference production
Rest of Europe 15.9% of region EU-funded metrology and cross-border fibre time transfer


Europe's demand is unusually institution-led. PTB and NPL operate reference chains that anchor national traceability, and both have extended optical fibre time-transfer links to commercial users [3][20]. The EU's Space Programme allocation and the European Commission's critical-infrastructure resilience work provide a decade of visible funding [4]. Britain's post-Brexit timing resilience programme has funded trials of terrestrial backup services aimed explicitly at the financial district.

Asia-Pacific

Country Metric Key Driver
China 31.6% of region BeiDou payload production and domestic supply substitution
India 7.12% CAGR NavIC expansion and indigenous reference development
Japan USD 35.1 Million Optical clock research and QZSS augmentation
South Korea 11.4% of region KPS constellation programme and 5G synchronisation
ASEAN 6.85% CAGR CORS networks and telecom infrastructure build-out
Rest of Asia-Pacific 9.7% of region Broadcast, defence and research procurement


Asia-Pacific's advantage is that its constellations are still being built. China's BeiDou global service reached full operational capability in 2020 and has moved into a replenishment and augmentation phase . South Korea approved the Korean Positioning System with a programme value near KRW 3.7 trillion through 2035, which will require domestically qualified space references [21]. Japan's contribution runs through metrology rather than volume, with RIKEN and NICT optical standards among the most accurate operating worldwide [2].

South America

Country Metric Key Driver
Brazil 52.4% of region Satellite ground stations and broadcast timing modernisation
Argentina USD 8.9 Million Radio astronomy and national metrology upgrades
Rest of South America 5.14% CAGR Mining telemetry and telecom synchronisation


Brazil anchors the region through its space agency ground segment and a broadcast sector that has been migrating to digital standards requiring tighter synchronisation. Argentina's demand concentrates in scientific installations, including radio-astronomy facilities that depend on maser references for very-long-baseline interferometry. Across the rest of the continent, mining and energy telemetry provide steady but modest replacement volume rather than programme-scale orders.

Middle East & Africa

Country Metric Key Driver
Saudi Arabia 29.8% of region National PNT strategy and giga-project infrastructure
UAE USD 10.3 Million Space programme expansion and financial-centre timing
South Africa 5.44% CAGR Radio astronomy and grid synchronisation
Egypt 11.2% of region Satellite ground segment and telecom modernisation
Rest of MEA 20.6% of region Defence communications and broadcast infrastructure


Saudi Arabia's Vision 2030 infrastructure agenda has embedded timing requirements into smart-grid and transport programmes, and the kingdom's space authority has signalled sovereign PNT ambitions [21]. The UAE combines an expanding space programme with a financial centre subject to international timestamp expectations. South Africa's demand is scientific — the SKA precursor arrays require hydrogen maser references at scale, and site expansion drives procurement more than commercial telecom does.


Atomic Clock Market By Region, 2025-2035

Atomic Clock Market Segmentation

By Type

Technology choice in the Atomic Clock Market reduces to a trade between absolute stability and deployability, and the three principal classes occupy distinct positions on that curve.

Segment Metric (2025) Primary Demand Driver
Cesium 43.3% share National primary references and traceability chains
Rubidium USD 251.6 Million Space payloads and size-, weight- and power-constrained platforms
Hydrogen Maser 5.21% CAGR Radio astronomy, VLBI and satellite ground segment


Cesium holds its lead because the SI second is still defined by a cesium transition, which makes a cesium atomic frequency standard the natural anchor for any traceable calibration chain. That regulatory gravity is difficult to dislodge, though it will loosen if optical redefinition proceeds. Rubidium is the volume story: lower cost, smaller envelope and adequate stability for most embedded roles, which is why it dominates satellite bus specifications and increasingly appears in telecom aggregation nodes.

By End User

End-user composition in the Atomic Clock Market has shifted decisively toward civil buyers over the past five years, reversing a long period of defence dominance.

Segment Metric (2025) Primary Demand Driver
Civil and Commercial 48.8% share Telecom synchronisation, financial compliance, data centres
Defence USD 234.0 Million Assured PNT, electronic warfare, secure communications
Space 6.56% CAGR Constellation replenishment and new sovereign programmes


Civil and commercial demand now sets the pace, and it behaves differently from government demand — shorter cycles, tighter price sensitivity, higher unit volumes. Space is the fastest-growing block because constellation architectures have changed: more satellites, shorter design lives and faster refresh cadence mean more references purchased per decade even where per-unit performance requirements relax.

By Application

Application mix within the Atomic Clock Market spans defence-grade to commodity-adjacent use cases, with navigation the largest single pool.

Segment Metric (2025) Primary Demand Driver
Navigation 21.5% share GNSS payloads and multi-constellation receiver design
Telecommunication USD 133.1 Million 5G-Advanced phase alignment and holdover requirements
Surveillance 15.2% share ISR platforms and coherent radar processing
Financial Trading and Data Centers 6.54% CAGR Timestamp regulation and cloud clock-bound guarantees
Electronic Warfare USD 91.1 Million Frequency-agile systems and coherent jamming resistance
Broadcast and Media 4.62% CAGR Digital transmission networks and single-frequency networks
Other Applications 7.8% share Scientific research, metrology and test infrastructure


Navigation leads and will keep leading, but its growth is programme-driven and therefore lumpy — a single constellation award can move a year. Financial trading and data centres deliver the steadiest compounding because the underlying driver is regulatory and contractual rather than budgetary, and because cloud providers have begun publishing clock-error commitments that require reference hardware to honour [15][16].


Competitive Benchmarking

Concentration in the Atomic Clock Market sits in the moderate band. Analyst estimates place the Herfindahl-Hirschman Index near 950–1,100, with the top five suppliers holding roughly 48–56% of global revenue. The structure is best described as a concentrated core with a long tail: two or three vendors dominate primary-reference and telecom-grade supply, while a dozen specialists compete on space qualification, ruggedisation, and national-champion status. Barriers are heritage and qualification rather than patents.

Company Est. Revenue Share Range Key Offerings for the Atomic Clock Market Strategic Positioning
Microchip Technology Inc. ~14–18% Cesium primary standards, rubidium oscillators, chip-scale atomic clock CSAC modules, time servers Broadest portfolio; strong telecom and defence channel
Safran (Orolia) ~11–15% Rubidium standards, resilient PNT systems, GNSS simulators Systems integrator positioning across defence and civil aviation
Adtran (Oscilloquartz) ~8–11% Cesium and rubidium telecom clocks, sync assurance software Telecom synchronisation specialist with software attach
Frequency Electronics Inc. ~6–9% Space-qualified rubidium and quartz references, RAFS units Deep satellite payload heritage; U.S. government aligned
VREMYA-CH JSC ~5–8% Hydrogen masers, cesium standards, time-transfer equipment Dominant in domestic and allied GLONASS supply
Excelitas Technologies ~4–7% Rubidium standards, precision timing subsystems Component-level supplier to defence primes
Chengdu Spaceon Electronics ~4–7% Rubidium and cesium references, timing modules Principal domestic supplier to Chinese constellation programmes
Stanford Research Systems ~3–5% Benchtop rubidium standards, distribution amplifiers Laboratory and test-instrumentation channel
Leonardo S.p.A. ~2–4% Space passive hydrogen masers, rubidium payload clocks Galileo payload incumbent with ESA qualification depth
AccuBeat Ltd. ~2–4% Miniature rubidium standards, space-qualified oscillators Niche supplier for compact and airborne platforms
Exail Technologies ~2–4% Cold-atom clocks, quantum sensing references Emerging quantum-technology entrant
Teledyne e2v ~1–3% Cold-atom clock components, miniaturised references Component and subsystem specialist


Recent News & Developments

Developments across 2023–2025 cluster around three themes relevant to the Atomic Clock Market: miniaturisation, sovereign supply and optical readiness.

  • Microchip Technology (August 2026): Expanded its low-power chip-scale product line with improved holdover specifications, targeting unmanned platforms and portable defence radios where power budgets are the binding constraint [13].


  • Adtran / Oscilloquartz (September 2024): Released updated synchronisation assurance software bundled with cesium-grade references for tier-one operator networks, reinforcing the platform model described in.
  • National Institute of Standards and Technology (October 2024): Published updated comparison results for optical standards supporting the international roadmap toward redefinition of the second [2].
  • Indian Space Research Organisation (May 2023): Confirmed indigenous rubidium reference qualification for the extended NavIC series, reducing import dependence for the programme .
  • Korea Aerospace Research Institute (May 2025): Progressed Korean Positioning System payload development, including onboard reference procurement planning through 2035 [21].
  • Exail Technologies (July 2024): Advanced field trials of transportable cold-atom references aimed at defence and metrology customers, signalling commercial intent for quantum-class timing [24].


Atomic Clock Market Report Scope

Parameter Detail
Market Scope Global demand for atomic frequency standards across rubidium, cesium and hydrogen maser technologies, spanning defence, space, and civil and commercial end users
Study Period 2021–2035 (Historical 2021–2024; Base Year 2025; Forecast 2026–2035)
CAGR 5.82% (2026–2035)
Market Size Checkpoints USD 700.5 Million (2025); USD 741.6 Million (2026); USD 1,233.9 Million (2035)
Fastest Growing Segments Space (end user); Financial Trading and Data Centers (application); Asia-Pacific (region)
Companies Profiled 12 leading suppliers across primary reference, telecom-grade and space-qualified categories
Valuation Currency USD Million, constant 2025 prices

FAQs

What total cost of ownership should a buyer model beyond the purchase price in the Atomic Clock Market?
Budget for annual calibration, beam-tube or lamp replacement at five-to-seven-year intervals, and environmental conditioning. Lifetime service typically adds 30–45% to acquisition cost over a fifteen-year deployment [14].
How should procurement teams compare vendor holdover specifications?
Insist on holdover figures stated at a defined temperature range and confidence level, not headline best-case numbers. Ambient variation degrades real-world holdover substantially, so require test data matching your site conditions [7].
What integration problems most often delay deployments in the Atomic Clock Market?
Antenna siting, cable delay compensation, and network management protocol mismatches cause the majority of schedule slips. Allocate commissioning time for delay calibration; skipping it silently erodes accuracy for years [15].
Do export controls apply to commercial timing purchases?
Frequently, yes. Several precision frequency standards sit on dual-use control lists, and cross-border shipments to defence-adjacent end users require licensing that can add months to lead time .
When does a chip-scale device make more sense than a rack-mounted rubidium unit?
Choose chip-scale where power is under two watts and stability requirements are moderate — portable radios, small drones, handheld receivers. Rack rubidium wins wherever mains power and stricter drift limits apply [13].
What competitive dynamic should buyers watch in the Atomic Clock Market?
Software attach is becoming the differentiator. Vendors bundling monitoring and assurance platforms are winning tier-one contracts against hardware-only competitors, which affects long-term support economics.
Is optical clock technology worth waiting for?
Not for operational deployments this decade. Transportable optical systems remain laboratory-adjacent and unqualified for most field environments; specify current technology and plan a refresh window after 2030 [3][24].      
Author
Author Author Profile Shubham Munde LinkedIn Team Lead - Research
Shubham brings over 7 years of expertise in Market Intelligence and Strategic Consulting, with a strong focus on the Automotive, Aerospace, and Defense sectors. Backed by a solid foundation in semiconductors, electronics, and software, he has successfully delivered high-impact syndicated and custom research on a global scale. His core strengths include market sizing, forecasting, competitive intelligence, consumer insights, and supply chain mapping. Widely recognized for developing scalable growth strategies, Shubham empowers clients to navigate complex markets and achieve a lasting competitive edge. Trusted by start-ups and Fortune 500 companies alike, he consistently converts challenges into strategic opportunities that drive sustainable growth.
Co-Author Co-Author Profile Sejal Akre LinkedIn Senior Research Analyst
She has over 5 years of rich experience, in market research and consulting providing valuable market insights to client. Hands on expertise in management consulting, and extensive knowledge in domain including ICT, Automotive & Transportation and Aerospace & Defense. She is skilled in Go-to market strategy, industry analysis, market sizing, in depth company profiling, competitive intelligence & benchmarking and value chain amongst others.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of regulatory databases, peer-reviewed scientific journals, technical publications, and authoritative metrology organizations. Key sources included the National Institute of Standards and Technology (NIST), National Physical Laboratory (NPL-UK), Physikalisch-Technische Bundesanstalt (PTB-Germany), Bureau International des Poids et Mesures (BIPM), International Telecommunication Union (ITU), Institute of Electrical and Electronics Engineers (IEEE), American Institute of Physics (AIP), National Aeronautics and Space Administration (NASA), European Space Agency (ESA), US Department of Defense (DoD), National Science Foundation (NSF), National Center for Science and Engineering Statistics (NCSES), OECD Science and Technology Indicators, and national metrology institute reports from key markets. These sources were used to collect frequency standard specifications, regulatory framework data, precision timing studies, technological advancement trends, and market landscape analysis for cesium atomic clocks, rubidium atomic clocks, optical lattice clocks, and hydrogen maser technologies.


Primary Research

In order to gather both qualitative and quantitative insights, supply-side and demand-side stakeholders were interviewed during the primary research process. CEOs, vice presidents of engineering, chief technology officers, and heads of business development from companies that produce atomic clocks, create frequency standards, and offer precision timing solutions were examples of supply-side sources. Chief scientists, systems engineers, network architects, and procurement leads from telecom companies, defense contractors, aerospace manufacturers, academic institutions, and governmental organizations made up demand-side sources. Primary research obtained information on technology adoption trends, pricing tactics, and procurement dynamics in addition to validating market segmentation and product development roadmaps.

Primary Respondent Breakdown:

By Designation: C-level Primaries (32%), Director Level (31%), Others (37%)

By Region: North America (38%), Europe (29%), Asia-Pacific (25%), Rest of World (8%)


Market Size Estimation

Global market valuation was derived through revenue mapping and unit shipment analysis. The methodology included:

Identification of 40+ key manufacturers across North America, Europe, Asia-Pacific, and Latin America

Product mapping across cesium atomic clocks, rubidium atomic clocks, optical lattice clocks, and hydrogen maser categories

Analysis of reported and modeled annual revenues specific to atomic clock and frequency standard portfolios

Coverage of manufacturers representing 75-80% of global market share in 2024

Extrapolation using bottom-up (unit shipments × ASP by region) and top-down (manufacturer revenue validation) approaches to derive segment-specific valuations

Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Aircraft MRO Market
Case Study
Aerospace & Defense
Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.


















