5G Infrastructure Market (2026 - 2035)

ID: MRFR/ICT/9046-CR 128 Pages Aarti Dhapte Last Updated: September 15, 2026
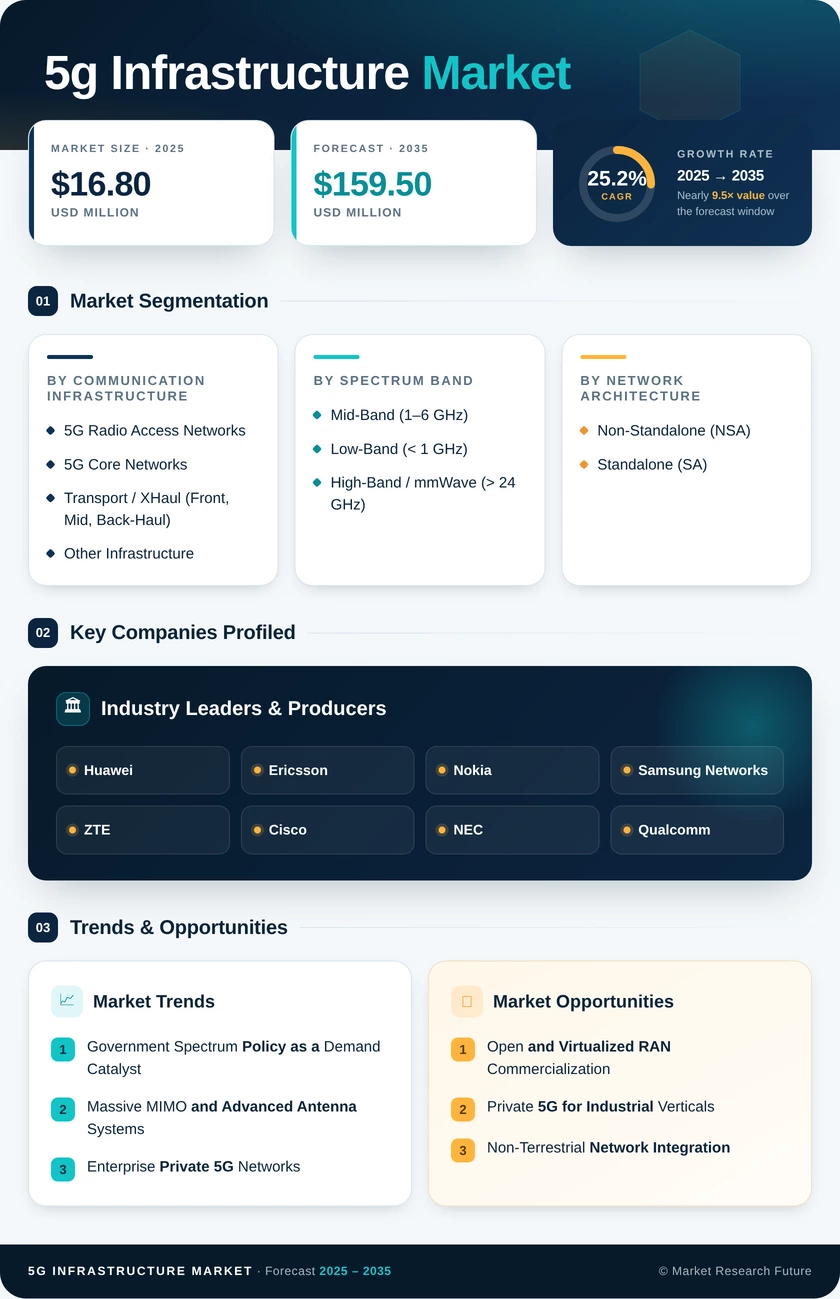
5G Infrastructure Market Size, Share and Research Report By Communication Infrastructure (5G Radio Access Networks, 5G Core Networks, Transport / XHaul (Front, Mid, Back-Haul), Other Infrastructure), By Spectrum Band (Low-Band, 24 GHz), By Network Architecture (Non-Standalone (NSA), Standalone (SA)), By Core Network Technology (Software-Defined Networking (SDN), Network Functions Virtualization (NFV), Multi-Access Edge Computing (MEC)), By End-User Vertical (Telecom Operators (Public Networks), Manufacturing & Industrial, Consumer Electronics, Other Verticals (Healthcare, Energy, Transport)) and By Regional (North America, Europe, South America, Asia Pacific, Middle East and Africa) - Industry Forecast to 2035.
5G Infrastructure Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)25.2%
2025 Market SizeUSD 16.8 Billion
2035 Market SizeUSD 159.5 Billion
Key Players
Huawei
Ericsson
Nokia
Samsung Networks
ZTE
Cisco
Opportunities
  • Open and Virtualized RAN Commercialization
  • Private 5G for Industrial Verticals
  • Non-Terrestrial Network Integration
  1. 1 Market Overview |
    1. 1.1 Study Assumptions & Market Definition |
    2. 1.2 Scope of the Study |
    3. 1.3 Research Methodology
  2. 2 Market Summary & Key Takeaways
  3. 3 Market Dynamics |
    1. 3.1 Market Drivers Analysis | |
      1. 3.1.1 Government Spectrum Auctions & National Broadband Mandates | |
      2. 3.1.2 Massive MIMO and Advanced Antenna Systems | |
      3. 3.1.3 Enterprise Private 5G Network Adoption | |
      4. 3.1.4 Fixed Wireless Access Expansion | |
      5. 3.1.5 Network Slicing and Edge Computing Monetization | |
      6. 3.1.6 Autonomous Vehicle and Industry
    2. 4.0 Connectivity Requirements | |
      1. 3.1.7 Satellite-Terrestrial Integration (NTN) |
    3. 3.2 Market Restraints Analysis | |
      1. 3.2.1 High Capex Burden and Operator Debt Loads | |
      2. 3.2.2 Geopolitical Vendor Restrictions | |
      3. 3.2.3 Spectrum Fragmentation and Harmonization Delays | |
      4. 3.2.4 Energy Cost and Sustainability Pressures | |
      5. 3.2.5 Skilled Workforce Shortages for Deployment |
    4. 3.3 Market Opportunity Analysis | |
      1. 3.3.1 Open and Virtualized RAN Commercialization | |
      2. 3.3.2 Private 5G for Industrial Verticals | |
      3. 3.3.3 Non-Terrestrial Network Integration | |
      4. 3.3.4 Emerging Market Leapfrog Deployments | |
      5. 3.3.5 Network-as-a-Service and Data Monetization |
    5. 3.4 Industry Value Chain Analysis |
    6. 3.5 Porter's Five Forces Analysis
  4. 4 Global 5G Infrastructure Market Size & Forecast (2021–2035) |
    1. 4.1 Historical Market Size (2021–2025) |
    2. 4.2 Current & Forecast Market Size (2026–2035) |
    3. 4.3 Market Size by Revenue (USD Billion) |
    4. 4.4 Year-over-Year Growth Analysis
  5. 5 Segmentation Analysis |
    1. 5.1 By Communication Infrastructure | |
      1. 5.1.1 5G Radio Access Networks | |
      2. 5.1.2 5G Core Networks | |
      3. 5.1.3 Transport / XHaul (Front, Mid, Back-Haul) | |
      4. 5.1.4 Other Infrastructure |
    2. 5.2 By Spectrum Band | |
      1. 5.2.1 Low-Band ( 24 GHz) |
    3. 5.3 By Network Architecture | |
      1. 5.3.1 Non-Standalone (NSA) | |
      2. 5.3.2 Standalone (SA) |
    4. 5.4 By Core Network Technology | |
      1. 5.4.1 Software-Defined Networking (SDN) | |
      2. 5.4.2 Network Functions Virtualization (NFV) | |
      3. 5.4.3 Multi-Access Edge Computing (MEC) |
    5. 5.5 By End-User Vertical | |
      1. 5.5.1 Telecom Operators (Public Networks) | |
      2. 5.5.2 Manufacturing & Industrial | |
      3. 5.5.3 Consumer Electronics | |
      4. 5.5.4 Other Verticals (Healthcare, Energy, Transport)
  6. 6 Regional Analysis |
    1. 6.1 North America | |
      1. 6.1.1 United States | |
      2. 6.1.2 Canada | |
      3. 6.1.3 Mexico |
    2. 6.2 Europe | |
      1. 6.2.1 Germany | |
      2. 6.2.2 United Kingdom | |
      3. 6.2.3 France | |
      4. 6.2.4 Italy | |
      5. 6.2.5 Spain | |
      6. 6.2.6 Nordic Countries | |
      7. 6.2.7 Russia | |
      8. 6.2.8 Rest of Europe |
    3. 6.3 Asia-Pacific | |
      1. 6.3.1 China | |
      2. 6.3.2 India | |
      3. 6.3.3 Japan | |
      4. 6.3.4 South Korea | |
      5. 6.3.5 ASEAN | |
      6. 6.3.6 Rest of Asia-Pacific |
    4. 6.4 South America | |
      1. 6.4.1 Brazil | |
      2. 6.4.2 Argentina | |
      3. 6.4.3 Rest of South America |
    5. 6.5 Middle East & Africa | |
      1. 6.5.1 Saudi Arabia | |
      2. 6.5.2 UAE | |
      3. 6.5.3 South Africa | |
      4. 6.5.4 Egypt | |
      5. 6.5.5 Rest of MEA
  7. 7 Competitive Landscape |
    1. 7.1 Market Share Analysis (2025) |
    2. 7.2 Competitive Benchmarking Matrix |
    3. 7.3 Company Profiles | |
      1. 7.3.1 Huawei | |
      2. 7.3.2 Ericsson | |
      3. 7.3.3 Nokia | |
      4. 7.3.4 Samsung Networks | |
      5. 7.3.5 ZTE | |
      6. 7.3.6 Cisco | |
      7. 7.3.7 NEC | |
      8. 7.3.8 Qualcomm | |
      9. 7.3.9 Mavenir | |
      10. 7.3.10 Fujitsu
  8. 8 Future Outlook & Strategic Recommendations (2026–2035) |
    1. 8.1 AI-Native Network Operations |
    2. 8.2 Network-as-a-Platform Economics |
    3. 8.3 Energy Efficiency and Sustainability Mandates |
    4. 8.4 Convergence with 6G Research Programs
  9. 9 Recent Developments & News
  10. 10 Frequently Asked Questions (FAQs)
  11. 11 Report Scope & Methodology |
    1. 11.1 Study Period & Base Year |
    2. 11.2 Data Sources & Citations |
    3. 11.3 Abbreviations
  12. 12 LIST OF TABLES |
  13. TABLE 1 Global 5G Infrastructure Market Size & Forecast, by Revenue (USD Billion), 2021–2035 |
  14. TABLE 2 Global 5G Infrastructure Market — Year-over-Year Growth Analysis, 2021–2035 |
  15. TABLE 3 Global 5G Infrastructure Market — Driver Impact Analysis |
  16. TABLE 4 Global 5G Infrastructure Market — Restraint Impact Analysis |
  17. TABLE 5 Global 5G Infrastructure Market Size, by Communication Infrastructure, 2021–2035 (USD Billion) |
  18. TABLE 6 Global 5G Infrastructure Market Size, by Spectrum Band, 2021–2035 (USD Billion) |
  19. TABLE 7 Global 5G Infrastructure Market Size, by Network Architecture, 2021–2035 (USD Billion) |
  20. TABLE 8 Global 5G Infrastructure Market Size, by Core Network Technology, 2021–2035 (USD Billion) |
  21. TABLE 9 Global 5G Infrastructure Market Size, by End-User Vertical, 2021–2035 (USD Billion) |
  22. TABLE 10 Global 5G Infrastructure Market Size, by Region, 2021–2035 (USD Billion) |
  23. TABLE 11 North America 5G Infrastructure Market Size, by Country, 2021–2035 (USD Billion) |
  24. TABLE 12 Europe 5G Infrastructure Market Size, by Country, 2021–2035 (USD Billion) |
  25. TABLE 13 Asia-Pacific 5G Infrastructure Market Size, by Country, 2021–2035 (USD Billion) |
  26. TABLE 14 South America 5G Infrastructure Market Size, by Country, 2021–2035 (USD Billion) |
  27. TABLE 15 Middle East & Africa 5G Infrastructure Market Size, by Country, 2021–2035 (USD Billion) |
  28. TABLE 16 Competitive Benchmarking Matrix — Global 5G Infrastructure Market, 2025 |
  29. TABLE 17 Company Profiles — Key Players, Global 5G Infrastructure Market |
  30. TABLE 18 Recent Developments & Strategic Announcements, 2023–2025 |
  31. TABLE 19 Report Scope & Methodology |
  32. TABLE 20 Detailed Sources and Citations |
  33. TABLE 21 North America 5G Infrastructure Market Size, by Communication Infrastructure, 2021–2035 (USD Billion) |
  34. TABLE 22 North America 5G Infrastructure Market Size, by Spectrum Band, 2021–2035 (USD Billion) |
  35. TABLE 23 North America 5G Infrastructure Market Size, by Network Architecture, 2021–2035 (USD Billion) |
  36. TABLE 24 North America 5G Infrastructure Market Size, by End-User Vertical, 2021–2035 (USD Billion) |
  37. TABLE 25 Europe 5G Infrastructure Market Size, by Communication Infrastructure, 2021–2035 (USD Billion) |
  38. TABLE 26 Europe 5G Infrastructure Market Size, by Spectrum Band, 2021–2035 (USD Billion) |
  39. TABLE 27 Europe 5G Infrastructure Market Size, by Network Architecture, 2021–2035 (USD Billion) |
  40. TABLE 28 Europe 5G Infrastructure Market Size, by End-User Vertical, 2021–2035 (USD Billion) |
  41. TABLE 29 Asia-Pacific 5G Infrastructure Market Size, by Communication Infrastructure, 2021–2035 (USD Billion) |
  42. TABLE 30 Asia-Pacific 5G Infrastructure Market Size, by Spectrum Band, 2021–2035 (USD Billion) |
  43. TABLE 31 Asia-Pacific 5G Infrastructure Market Size, by Network Architecture, 2021–2035 (USD Billion) |
  44. TABLE 32 Asia-Pacific 5G Infrastructure Market Size, by End-User Vertical, 2021–2035 (USD Billion) |
  45. TABLE 33 South America 5G Infrastructure Market Size, by Communication Infrastructure, 2021–2035 (USD Billion) |
  46. TABLE 34 South America 5G Infrastructure Market Size, by Spectrum Band, 2021–2035 (USD Billion) |
  47. TABLE 35 South America 5G Infrastructure Market Size, by Network Architecture, 2021–2035 (USD Billion) |
  48. TABLE 36 South America 5G Infrastructure Market Size, by End-User Vertical, 2021–2035 (USD Billion) |
  49. TABLE 37 Middle East & Africa 5G Infrastructure Market Size, by Communication Infrastructure, 2021–2035 (USD Billion) |
  50. TABLE 38 Middle East & Africa 5G Infrastructure Market Size, by Spectrum Band, 2021–2035 (USD Billion) |
  51. TABLE 39 Middle East & Africa 5G Infrastructure Market Size, by Network Architecture, 2021–2035 (USD Billion) |
  52. TABLE 40 Middle East & Africa 5G Infrastructure Market Size, by End-User Vertical, 2021–2035 (USD Billion)
  53. 13 LIST OF FIGURES |
  54. FIGURE 1 Global 5G Infrastructure Market Dynamics (Drivers, Restraints, Opportunities) |
  55. FIGURE 2 Industry Value Chain Analysis — 5G Infrastructure Market |
  56. FIGURE 3 Porter's Five Forces Analysis — 5G Infrastructure Market |
  57. FIGURE 4 Global 5G Infrastructure Market Size Trend & Forecast (USD Billion), 2021–2035 |
  58. FIGURE 5 Global 5G Infrastructure Market Share, by Communication Infrastructure (%), 2025 |
  59. FIGURE 6 Global 5G Infrastructure Market Share, by Spectrum Band (%), 2025 |
  60. FIGURE 7 Global 5G Infrastructure Market Share, by Network Architecture (%), 2025 |
  61. FIGURE 8 Global 5G Infrastructure Market Share, by End-User Vertical (%), 2025 |
  62. FIGURE 9 Global 5G Infrastructure Market Share, by Region (%), 2025 |
  63. FIGURE 10 North America 5G Infrastructure Market Size & Forecast (USD Billion), 2021–2035 |
  64. FIGURE 11 Europe 5G Infrastructure Market Size & Forecast (USD Billion), 2021–2035 |
  65. FIGURE 12 Asia-Pacific 5G Infrastructure Market Size & Forecast (USD Billion), 2021–2035 |
  66. FIGURE 13 South America 5G Infrastructure Market Size & Forecast (USD Billion), 2021–2035 |
  67. FIGURE 14 Middle East & Africa 5G Infrastructure Market Size & Forecast (USD Billion), 2021–2035 |
  68. FIGURE 15 Competitive Landscape — Market Share Analysis (%), 2025 |
  69. FIGURE 16 Competitive Benchmarking Radar — Top 10 Players

Segmentation Quick Reference

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
Communication Infrastructure5G RAN; 5G Core Networks; Transport / XHaul; Other5G Radio Access NetworksTransport / XHaul
Spectrum BandLow-Band; Mid-Band; High-Band / mmWaveMid-Band (1–6 GHz)High-Band / mmWave
Network ArchitectureNon-Standalone (NSA); Standalone (SA)Non-Standalone (NSA)Standalone (SA)
Core Network TechnologySDN; NFV; MECSDNMEC
End-User VerticalTelecom Operators; Manufacturing & Industrial; Consumer Electronics; Other VerticalsTelecom OperatorsManufacturing & Industrial
RegionNorth America; Europe; Asia-Pacific; South America; Middle East & AfricaAsia-PacificAsia-Pacific


Market Segmentation Overview

By Communication Infrastructure

Sub-SegmentKey Trend
5G Radio Access NetworksMassive MIMO and multi-band radio evolution driving upgrade cycles
5G Core NetworksCloud-native standalone core enabling slicing and edge services
Transport / XHaul (Front, Mid, Back-Haul)Coherent optics and time-sensitive networking expanding capacity
Other InfrastructurePower, cooling, and tower systems adapting to 5G energy profiles


Radio access networks remain the largest infrastructure investment category as operators balance geographic expansion with capacity densification. The migration toward standalone core platforms is unlocking new service-based revenue models, while transport infrastructure investments are scaling to support the bandwidth demands of dense small cell architectures.

By Spectrum Band

Sub-SegmentKey Trend
Low-Band (< 1 GHz)Broad rural coverage and deep indoor signal penetration
Mid-Band (1–6 GHz)Global harmonization around 3.3–3.8 GHz for capacity layer
High-Band / mmWave (> 24 GHz)Ultra-high throughput for dense venues and fixed wireless


Mid-band spectrum dominates global 5G deployments, offering the most commercially viable trade-off between speed and coverage. High-band mmWave continues to find traction in stadium, airport, and dense urban corridor applications where extreme capacity is required.

By Network Architecture

Sub-SegmentKey Trend
Non-Standalone (NSA)Legacy approach leveraging 4G EPC; majority of current installed base
Standalone (SA)Future-ready architecture enabling full 5G capabilities


The industry is progressing through a multi-year migration from NSA to SA deployments. Standalone architecture is essential for unlocking network slicing, ultra-reliable low-latency communications, and advanced edge computing capabilities that define the 5G value proposition for enterprise buyers.

By Core Network Technology

Sub-SegmentKey Trend
Software-Defined Networking (SDN)Programmable transport and traffic management
Network Functions Virtualization (NFV)Decoupling network functions from proprietary hardware
Multi-Access Edge Computing (MEC)Distributed compute at the network edge for latency-sensitive apps


SDN and NFV form the virtualization foundation of modern 5G core networks, enabling operators to deploy and scale services with software agility. MEC extends compute and storage resources to the edge of the network, creating new service delivery models for industrial and consumer applications.

By End-User Vertical

Sub-SegmentKey Trend
Telecom Operators (Public Networks)Consumer broadband and wholesale enterprise connectivity
Manufacturing & IndustrialPrivate 5G for automation, robotics, and quality control
Consumer ElectronicsCPE devices, FWA modems, and mobile hotspot equipment
Other Verticals (Healthcare, Energy, Transport)Mission-critical and IoT connectivity requirements


Telecom operators account for the vast majority of 5G infrastructure spending, driven by competitive pressure to expand coverage and deliver differentiated consumer experiences. Enterprise and industrial verticals are emerging as the highest-growth demand source, as dedicated private 5G networks enable use cases that public networks cannot efficiently serve.




Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.