5G Infrastructure Market Summary
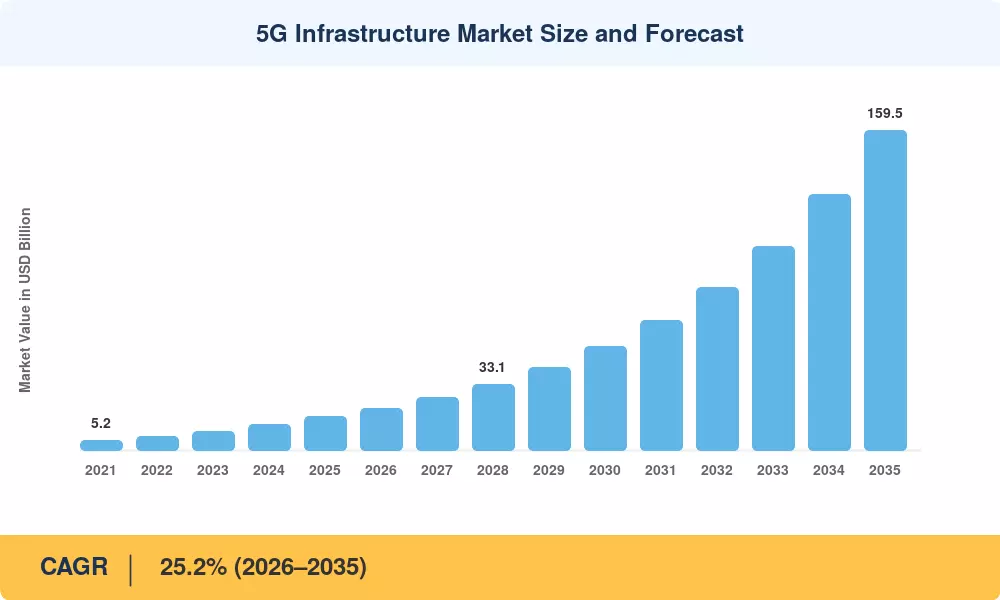
The 5G Infrastructure Market reached an estimated USD 16.8 billion in 2025 and is projected to grow from USD 21.1 billion in 2026 to USD 159.5 billion by 2035, reflecting a compound annual growth rate of 25.2% across the forecast period. This aggressive trajectory is anchored in government-led spectrum allocation programs — the U.S. FCC alone auctioned over USD 8 billion in C-band spectrum licenses between 2021 and 2024 — and in operator commitments that have collectively exceeded USD 350 billion globally for 5G network rollout through 2030 [1].
The 5G Infrastructure Market is fundamentally reshaping how telecommunications networks are designed, deployed, and monetized. Legacy 4G LTE macro-cell architectures are giving way to dense, multi-layered network topologies that combine massive MIMO antenna arrays, virtualized core functions, and fiber-fed transport links. Operators across 48 countries had launched commercial 5G services by the end of 2024, according to the GSA, with capex directed at radio access networks, standalone core platforms, and high-capacity backhaul upgrades [4].
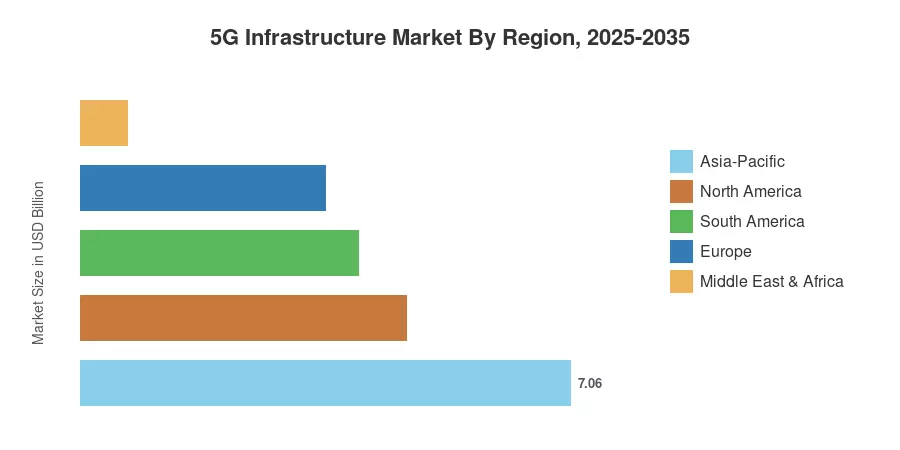
Asia-Pacific commands the largest share of the 5G Infrastructure Market at approximately 42% of global revenue, driven by China's state-directed rollout that deployed over 3.5 million base stations by mid-2024. The region also registers the fastest growth, with a CAGR exceeding 27%. North America holds roughly a 28% share, buoyed by mid-band spectrum deployment across the three major carriers. Europe accounts for about 21%, with regulatory harmonization under the EU's Digital Decade targets accelerating investment. As private 5G networks gain enterprise traction and satellite-terrestrial convergence matures, the 5G Infrastructure Market is entering a phase of sustained, multi-decade expansion [6].
Key Report Takeaways
• By Communication Infrastructure
- 5G Radio Access Networks represented the dominant infrastructure segment, holding over 46% of total 5G Infrastructure Market revenue in 2025, as operators prioritize outdoor macro and indoor small cell deployments.
- Transport/XHaul infrastructure is projected to record a CAGR of 28.1% during the forecast period, reflecting surging demand for fiber-based fronthaul and midhaul connectivity.
- 5G Core Networks attracted USD 3.2 billion in spending during 2025, as carriers migrate toward cloud-native, standalone architectures.
• By Spectrum Band
- Mid-band spectrum (1–6 GHz) accounted for approximately 52% of the 5G Infrastructure Market by value in 2025, serving as the capacity workhorse for most commercial deployments.
- Low-band holdings continue to expand rural coverage reach, with over 85% population coverage achieved in leading markets by 2024.
• By Region
- Asia-Pacific leads the 5G Infrastructure Market with a 42% revenue share and is simultaneously the fastest-growing region at a projected CAGR of 27.3%.
- North America generated approximately USD 4.7 billion in 5G infrastructure spending during 2025, underpinned by C-band and mmWave investments.
5G Infrastructure Market Size and Forecast (2021–2035)
Market Research Future's estimates are derived from a bottom-up methodology combining operator capex disclosures, vendor shipment data, regulatory filings, and validated third-party forecasts. Historical figures reflect actual industry spending, while forecast values apply the calibrated 25.2% CAGR with adjustments for cyclical capex peaks, spectrum auction timing, and technology migration milestones [1].




 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA



