キャップクロージャー市場 概要
主要な市場動向とハイライト
市場規模と予測
| CAGR (2025 - 2035) | 4.90% |
| CAGR (2025 - 2035) | 4.90% |
The Caps and Closures Market is currently experiencing a dynamic evolution, driven by various factors including consumer preferences, technological advancements, and sustainability initiatives. As the demand for convenience and product safety continues to rise, manufacturers are increasingly focusing on innovative designs and materials. This shift is evident in the growing popularity of tamper-evident and child-resistant closures, which enhance product integrity and consumer trust. Additionally, the market is witnessing a notable trend towards lightweight and recyclable materials, aligning with global sustainability goals. Companies are investing in research and development to create eco-friendly options that meet regulatory standards while appealing to environmentally conscious consumers. Moreover, the Caps and Closures Market is influenced by the expansion of the food and beverage sector, which requires efficient packaging solutions. The rise of e-commerce has further accelerated the need for secure and reliable closures that can withstand the rigors of shipping and handling. As brands strive to differentiate themselves in a competitive landscape, customization and branding opportunities through closures are becoming increasingly important. Overall, the market appears poised for continued growth, with innovation and sustainability at the forefront of strategic initiatives.
The Caps and Closures Market is increasingly prioritizing sustainability, with manufacturers exploring biodegradable and recyclable materials. This trend reflects a broader commitment to environmental responsibility, as companies seek to reduce their carbon footprint and meet consumer demand for eco-friendly products.
Innovations in manufacturing processes are reshaping the Caps and Closures Market. Automation and smart technologies are enhancing production efficiency and quality control, allowing for more precise and consistent closure designs that cater to diverse consumer needs.
As competition intensifies, brands are leveraging closures as a means of differentiation. Customization options, including unique shapes and colors, are becoming essential for attracting consumer attention and reinforcing brand identity in the Caps and Closures Market.
技術革新は、キャップとクロージャー市場を形成する極めて重要な役割を果たしています。進歩 射出成形や自動化などので製造技術により、生産効率が向上し、コストが削減されました。で2025 市場では、不正開封防止やチャイルドレジスタンスなどの機能を組み込んだスマート クロージャーの採用が急増すると予想されています。これらの革新は製品の安全性を向上させるだけでなく、ユーザーエクスペリエンスも向上させます。さらに、デザインと生産プロセスにデジタル技術を統合することで、より高度なカスタマイズと迅速なプロトタイピングが可能になり、ブランドが市場の需要に迅速に対応できるようになります。その結果、これらの技術の進歩を活用する企業は、消費者の進化するニーズに応え、キャップとクロージャ市場での地位を強化する可能性があります。
規制順守は、キャップとクロージャー市場の重要な推進力です。世界中の政府が包装材料や安全基準に関して厳格な規制を導入する中、メーカーは競争力を維持するために適応する必要があります。で2025、これらの規制への準拠は、材料の選択と設計プロセスに大きな影響を与えることが予想されます。これには、食品の安全性、リサイクル可能性、および化学物質含有量での包装に関するガイドラインの遵守が含まれます。でコンプライアンス対策に積極的に取り組む企業は、評判を高め、消費者の信頼を築く可能性があります。さらに、持続可能性を重視するで規制枠組みにより、メーカーは環境に優しいキャップとクロージャの革新と開発を推進しています。その結果、規制の状況を効果的に乗り越えることができるかどうかが、キャップアンドクロージャー市場の成功の重要な決定要因となるでしょう。
電子商取引の急速な成長は、キャップアンドクロージャー市場に大きな影響を与えています。オンラインショッピングが拡大し続けるにつれて、安全で信頼性の高い梱包ソリューションに対する需要が高まっています。で2025、it 電子商取引分野では、輸送中の製品の完全性を保証する革新的なキャップとクロージャーが必要になることが予想されます。これには、消費者エクスペリエンスを向上させる改ざん防止シールや開けやすいデザインなどの機能が含まれます。さらに、消費者直販チャネルの増加により、製品を保護するだけでなく、ブランド価値を反映したパッケージングも必要となります。その結果、電子商取引市場の特定のニーズを満たすように製品を調整するメーカーは、オンライン小売の成長傾向を利用して、キャップとクロージャー市場を繁栄させる可能性があります。
キャップとクロージャー市場は、持続可能性への取り組みの影響をますます受けています。消費者の環境意識が高まっており、メーカーも環境に優しい材料や生産プロセスを採用するようになっています。企業がキャップとクロージャの生分解性およびリサイクル可能なオプションを模索していることから、この変化は明らかです。で2025、市場のかなりの部分がプラスチック廃棄物の削減に焦点を当てており、持続可能な包装ソリューションの需要は増加すると予測されています。その結果、持続可能性を優先するブランドは競争力を獲得し、環境への責任を重視する増加する層にアピールする可能性があります。 さらに、政府が包装廃棄物に関するより厳格なガイドラインを実施しているため、規制上の圧力もこの傾向を推進しており、それによりメーカーはキャップとクロージャー市場の製品の革新と適応を余儀なくされています。
キャップとクロージャ市場では、カスタマイズとブランディングの機会がますます重要になっています。競争が激化する中、ブランドは店頭で自社製品を差別化する独自のパッケージングソリューションを模索しています。で2025 市場では、企業が独自のアイデンティティを確立できるようにする、パーソナライズされたキャップとクロージャが増加すると予測されています。この傾向は、パッケージが消費者の認識において重要な役割を果たす飲料や化粧品などので分野で特に顕著です。さらに、ブランドのロゴや色をクロージャに組み込むことができるため、ブランドの認知度とロイヤルティが向上します。消費者が自分の好みに共鳴する製品に惹かれるにつれて、カスタマイズされたキャップとクロージャの需要は増加する可能性があり、キャップとクロージャ市場の製造業者にとって有利な機会をもたらします。
In the caps and closures market, the material type segment is predominantly led by plastic, which has carved out the largest market share due to its lightweight, cost-effective, and versatile nature. Plastics are widely utilized across various industries, from beverages to personal care, contributing to their significant prevalence. Conversely, metal closures, particularly aluminum and tinplate, are seeing a surge in popularity, capturing attention with their robustness and recycled properties, indicating a shift towards sustainability in consumer preferences.
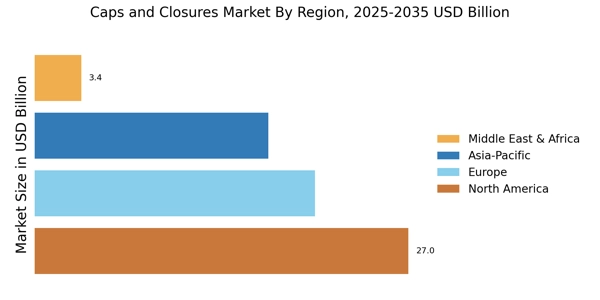
North America is the largest market for caps and closures, holding approximately 40% of the global market share. The region's growth is driven by increasing demand for sustainable packaging solutions and stringent regulations promoting eco-friendly materials. The U.S. leads in innovation, with a focus on advanced manufacturing technologies and consumer preferences shifting towards convenience and recyclability. Key players like Crown Holdings and Ball Corporation dominate the landscape, supported by a robust supply chain and significant investments in R&D. The U.S. and Canada are the primary contributors, with a competitive environment fostering collaboration among manufacturers. The presence of major companies ensures a steady supply of innovative products, catering to diverse industries such as food and beverage, pharmaceuticals, and personal care.
Europe is the second-largest market for caps and closures, accounting for around 30% of the global share. The region's growth is significantly influenced by stringent regulations aimed at reducing plastic waste and promoting recycling. The European Union's directives on single-use plastics are driving manufacturers to innovate and adopt sustainable practices, enhancing market dynamics. Leading countries include Germany, France, and the UK, where companies like Mondi Group and Alpla are at the forefront of sustainable packaging solutions. The competitive landscape is characterized by a mix of established players and emerging startups, all striving to meet the evolving consumer demands for eco-friendly products. The focus on circular economy principles is reshaping the market, encouraging collaboration across the supply chain.
Asia-Pacific is witnessing rapid growth in the caps and closures market, holding approximately 25% of the global share. The region's expansion is driven by increasing urbanization, rising disposable incomes, and a growing demand for packaged goods. Countries like China and India are leading this growth, supported by favorable government policies and investments in manufacturing capabilities. China is the largest market, with significant contributions from local manufacturers and multinational companies. The competitive landscape is evolving, with key players like Amcor and Berry Global expanding their presence. The region's diverse consumer base is pushing for innovative packaging solutions, creating opportunities for companies to introduce new products tailored to local preferences and sustainability goals.
The Middle East and Africa region is emerging as a significant player in the caps and closures market, holding about 5% of the global share. The growth is driven by increasing consumer demand for packaged products, particularly in the food and beverage sector. Additionally, government initiatives aimed at boosting local manufacturing are creating a favorable environment for market expansion. Countries like South Africa and the UAE are leading the charge, with a growing number of local manufacturers entering the market. The competitive landscape is characterized by a mix of established companies and new entrants, all vying for market share. The presence of key players such as Graham Packaging and AptarGroup is enhancing the region's capabilities, fostering innovation and meeting the rising demand for diverse packaging solutions.
The Caps and Closures Market is currently characterized by a dynamic competitive landscape, driven by innovation, sustainability, and strategic partnerships. Major players such as Crown Holdings (US), Ball Corporation (US), and Amcor (AU) are actively shaping the market through their distinct operational focuses. Crown Holdings (US) emphasizes innovation in packaging solutions, particularly in the beverage sector, while Ball Corporation (US) is leveraging its extensive experience in aluminum packaging to enhance sustainability initiatives. Amcor (AU) is also prioritizing sustainable practices, focusing on developing recyclable and biodegradable materials. Collectively, these strategies not only enhance their market positioning but also contribute to a more sustainable future for the industry.
In terms of business tactics, companies are increasingly localizing manufacturing to reduce lead times and optimize supply chains. This approach appears to be a response to the growing demand for efficiency and responsiveness in the market. The Caps and Closures Market is moderately fragmented, with key players exerting considerable influence. The collective actions of these companies suggest a trend towards consolidation, as they seek to enhance their competitive edge through strategic collaborations and acquisitions.
In August 2025, Crown Holdings (US) announced a partnership with a leading beverage manufacturer to develop a new line of eco-friendly caps. This collaboration is significant as it aligns with the growing consumer demand for sustainable packaging solutions, potentially positioning Crown as a leader in environmentally responsible practices within the sector. The partnership not only enhances Crown's product offerings but also strengthens its market presence in the beverage industry.
In September 2025, Ball Corporation (US) unveiled its latest initiative aimed at reducing carbon emissions across its production facilities. This strategic move underscores Ball's commitment to sustainability and reflects a broader industry trend towards environmental responsibility. By investing in cleaner technologies, Ball Corporation (US) is likely to enhance its operational efficiency while appealing to environmentally conscious consumers.
In July 2025, Amcor (AU) launched a new range of closures designed specifically for the food and beverage sector, focusing on enhancing product freshness and shelf life. This innovation is crucial as it addresses the increasing consumer preference for longer-lasting products. Amcor's proactive approach in developing advanced closure solutions may provide a competitive advantage, particularly in markets where product quality is paramount.
As of October 2025, the Caps and Closures Market is witnessing a shift towards digitalization, with companies increasingly integrating AI and data analytics into their operations. This trend is indicative of a broader movement towards efficiency and innovation. Strategic alliances are becoming more prevalent, as companies recognize the value of collaboration in navigating the complexities of the market. Looking ahead, competitive differentiation is likely to evolve, with a pronounced shift from price-based competition to a focus on innovation, technology, and supply chain reliability. This evolution suggests that companies that prioritize these aspects will be better positioned to thrive in the increasingly competitive landscape.
May 2026: Reliable Caps partnered with PureCycle Technologies to introduce closures made with up to 75% certified post-consumer recycled (PCR) polypropylene using PureCycle’s PureFive® resin. The closures are available through Reliable Caps’ distribution network across most of its product portfolio. The development addresses demand for recycled-content packaging in food, beverage, personal care and household applications while aiming to maintain product appearance, processing consistency and performance.
March 2026: Amcor announced a collaboration with Vöslauer Mineralwasser to supply a customized tethered closure for the Austrian mineral-water brand’s bottles. The cap remains attached to the bottle after opening, helping reduce litter and support collection and recycling. Its design allows the cap to open widely and stay away from the consumer’s face, combining ease of use with packaging sustainability objectives.
February 2026: Origin Materials partnered with Matrix Bottling Group to support the commercial adoption of recyclable PET bottle caps. Under the agreement, Matrix will provide bottling and capping services for beverages using Origin’s PET closures. Following a joint bottling trial in the fourth quarter of 2025, the companies planned customer qualification trials and product runs throughout 2026. The collaboration supports the shift toward mono-material PET packaging, designed to improve the recyclability of bottles and their caps together.
January 2026: Amcor introduced a lightweight, ergonomically designed tethered cap for Wattwiller, a French natural mineral-water brand owned by Spadel. Manufactured from HDPE and designed for recycling with PET bottles, the closure uses a smaller 26 mm bottle neck to reduce material use and weight compared with the previous design. Its flower-shaped surface combines smooth and ribbed sections to improve grip and make opening easier for consumers with limited dexterity.
June 2026: Blue Ocean Closures launched Paper-Plug™, a fiber-based opening and dispensing concept integrating a fiber screw closure directly into carton and corrugated-board packaging. The design aims to offer an alternative to conventional plastic fitments and complex opening assemblies for food, home-care and other packaged products. This development expands fiber-based packaging innovation into caps, closures and dispensing systems.
キャップおよびクロージャ市場は、革新的な持続可能な素材と飲料分野の需要の増加によって、at、4.1%、CAGRから2024から2035に成長すると予測されています。
新しい機会は以下にあります:
2035までに、キャップアンドクロージャー市場は、イノベーションと持続可能性によって力強い成長を達成すると予想されます。
| MARKET SIZE 2024 | 67.42(USD Billion) |
| MARKET SIZE 2025 | 70.19(USD Billion) |
| MARKET SIZE 2035 | 104.92(USD Billion) |
| COMPOUND ANNUAL GROWTH RATE (CAGR) | 4.1% (2024 - 2035) |
| REPORT COVERAGE | Revenue Forecast, Competitive Landscape, Growth Factors, and Trends |
| BASE YEAR | 2024 |
| Market Forecast Period | 2025 - 2035 |
| Historical Data | 2019 - 2024 |
| Market Forecast Units | USD Billion |
| Key Companies Profiled | Market analysis in progress |
| Segments Covered | Market segmentation analysis in progress |
| Key Market Opportunities | Adoption of sustainable materials in the Caps and Closures Market enhances eco-friendly packaging solutions. |
| Key Market Dynamics | Rising demand for sustainable packaging drives innovation in caps and closures, influencing competitive dynamics and consumer preferences. |
| Countries Covered | North America, Europe, APAC, South America, MEA |
キャップとクロージャーの市場は、at 75.0 USD Billionで2024 と評価されました。
市場は2035までに110.0 USD Billionに達すると予測されています。
2025 - 2035 中のキャップおよびクロージャー市場の予想 CAGR は 3.54% です。
飲料セグメントが大半を占めると予想されており、評価範囲は30.0から45.0 USD Billionとなっている。
主な素材にはプラスチック、金属、ガラス、木、紙が含まれ、プラスチックの価値は 30.0 から 45.0 USD Billion の間です。
スクリューキャップは 20.0 から 30.0 USD Billion の評価範囲で市場をリードすると予想されます。
主要企業には、Crown Holdings、Ball Corporation、Amcor、Silgan Holdings、Berry Global が含まれます。
食品および飲料最終用途セグメントの評価額は、30.0 から 45.0 USD Billion になると予想されます。
医薬品セグメントの評価額は 10.0 から 15.0 USD Billion の間であり、他のセグメントと比較して中程度のシェアを示しています。
傾向としては、消費者の好みによって、持続可能な素材や革新的なクロージャのデザインに対する需要が高まっていることが挙げられます。
The secondary research process involved comprehensive analysis of regulatory databases, industry standards, trade publications, and authoritative packaging organizations. Key sources included the US Food and Drug Administration (FDA) – Center for Food Safety and Applied Nutrition (CFSAN) for food contact substance regulations and 21 CFR Part 177 compliance data; European Food Safety Authority (EFSA) for plastic materials and articles intended to come into contact with food (EU Regulation 10/2011); US Environmental Protection Agency (EPA) for guidelines on recycled plastics and sustainable packaging materials; ASTM International standards (ASTM D3198, ASTM D3475 for child-resistant packaging); International Organization for Standardization (ISO) – ISO 8317 (child-resistant closures), ISO 9001 quality management systems; Plastics Industry Association (PLASTICS); Packaging Machinery Manufacturers Institute (PMMI); National Sanitation Foundation (NSF); US Census Bureau – Annual Survey of Manufactures (ASM) for NAICS Code 326160 (Plastics Bottle Manufacturing); Eurostat – Packaging Waste Statistics and Circular Economy indicators; United Nations Environment Programme (UNEP) for global plastic pollution treaties and Extended Producer Responsibility (EPR) frameworks; World Health Organization (WHO) – Good Manufacturing Practices (GMP) for pharmaceutical packaging; US Department of Agriculture (USDA) – bio-based packaging certifications; European Commission – Single Use Plastics Directive (SUPD); China National Center for Food Safety Risk Assessment (CFSA); Japan Ministry of Health, Labour and Welfare (MHLW) – Food Sanitation Law compliance data; and National Bureau of Statistics of China for manufacturing output metrics.
Production statistics, material safety studies, regulatory compliance data, recycling infrastructure analysis, and trade flow patterns for closure technologies involving polyethylene (PE), polypropylene (PP), high-density polyethylene (HDPE), low-density polyethylene (LDPE), polyethylene terephthalate (PET), aluminum, and steel were gathered from these sources.
To gather both qualitative and quantitative insights, supply-side and demand-side stakeholders were interviewed during the primary research process. CEOs, VPs of manufacturing, leaders of global innovation, officers in charge of regulatory compliance, and commercial directors from companies that make rigid packaging, injection molding, and raw material resin were among the supply-side sources. Demand-side sources included quality assurance leads from food processing companies (Mondelez, Danone), supply chain executives from personal care brands (Unilever, Procter & Gamble), pharmaceutical packaging managers (Pfizer, Johnson & Johnson), and procurement directors from multinational beverage corporations (Coca-Cola, PepsiCo, Nestlé).
Primary research confirmed sustainability transition timelines (shift to 30-50% rPET content), validated market segmentation across screw closures, dispensing caps, tethered caps, and crown closures, and collected information on automated capping line investments, lightweighting strategies, tamper-evident technology adoption, and raw material price volatility management.
Primary Respondent Breakdown:
By Designation: C-level Primaries (32%), Director Level (30%), Others (38%)
By Region: North America (33%), Europe (25%), Asia-Pacific (32%), Rest of World (10%)
Production volume analysis and revenue triangulation were used to get the global market valuation. The following were part of the methodology:
Finding more than fifty important manufacturers in the Middle East and Africa, Asia-Pacific, Latin America, Europe, and North America
Product mapping for rubber (butyl rubber, bromobutyl), metal (aluminum, steel), plastic (PP, HDPE, LDPE, PET, PS), and new bioplastic materials (PLA, bio-PE)
Technology segmentation encompassing post-mold tamper-evident band applications, compression molding, and injection molding
Examination of projected and reported yearly sales for caps and closures portfolios, omitting revenues from flexible packaging and container bodies
Coverage of producers who will account for 75–80% of the world market in 2024
To determine segment-specific valuations for food and beverage (carbonated drinks, bottled water, alcoholic beverages), pharmaceutical (OTC medications, prescription drugs, vaccines), personal care (cosmetics, toiletries), and household cleaning applications, extrapolation using top-down (manufacturer revenue validation) and bottom-up (production volume × Average Selling Price by material type and region) approaches is used.
このレポートの無料サンプルを受け取るには、以下のフォームにご記入ください
“This is really good guys. Excellent work on a tight deadline. I will continue to use you going forward and recommend you to others. Nice job”
“Thanks for sending the report it gives us a good global view of the Betaïne market.”
“We found the report very insightful! we found your research firm very helpful. I'm sending this email to secure our future business.”
“I am very pleased with how market segments have been defined in a relevant way for my purposes (such as "Portable Freezers & refrigerators" and "last-mile"). In general the report is well structured. Thanks very much for your efforts.”
“We got the report in time, we really thank you for your support in this process. I also thank to all of your team as they did a great job.”
“The Automotive 48V ECU Components Procurement Intelligence Study” was a complex project, but the Market Research Future (MRFR) team handled it with quality, agility, and customer-centricity. They delivered all requested data on time and within the agreed scope. The team, including Shubhendra Anand and Rahul Gotadki, was always readily available to clarify questions and swiftly implement necessary adjustments, driving the project to a successful conclusion within a very demanding timeframe.
I would also like to specifically commend Akshay Agarwal for his responsiveness and support at every stage—from our initial inquiry on May 6th through to final delivery on June 18th. His dedication made the entire process seamless.”
“Thanks. It’s been a pleasure working with you, please use me as reference with any other Intel employees.”
“Thank you, this will be very helpful for OQS.”
“I have been reading the first document or the study, ,the Global HVAC and FP market report 2021 till 2026. Must say, good info! I have not gone in depth at all parts, but got a good indication of the data inside!”