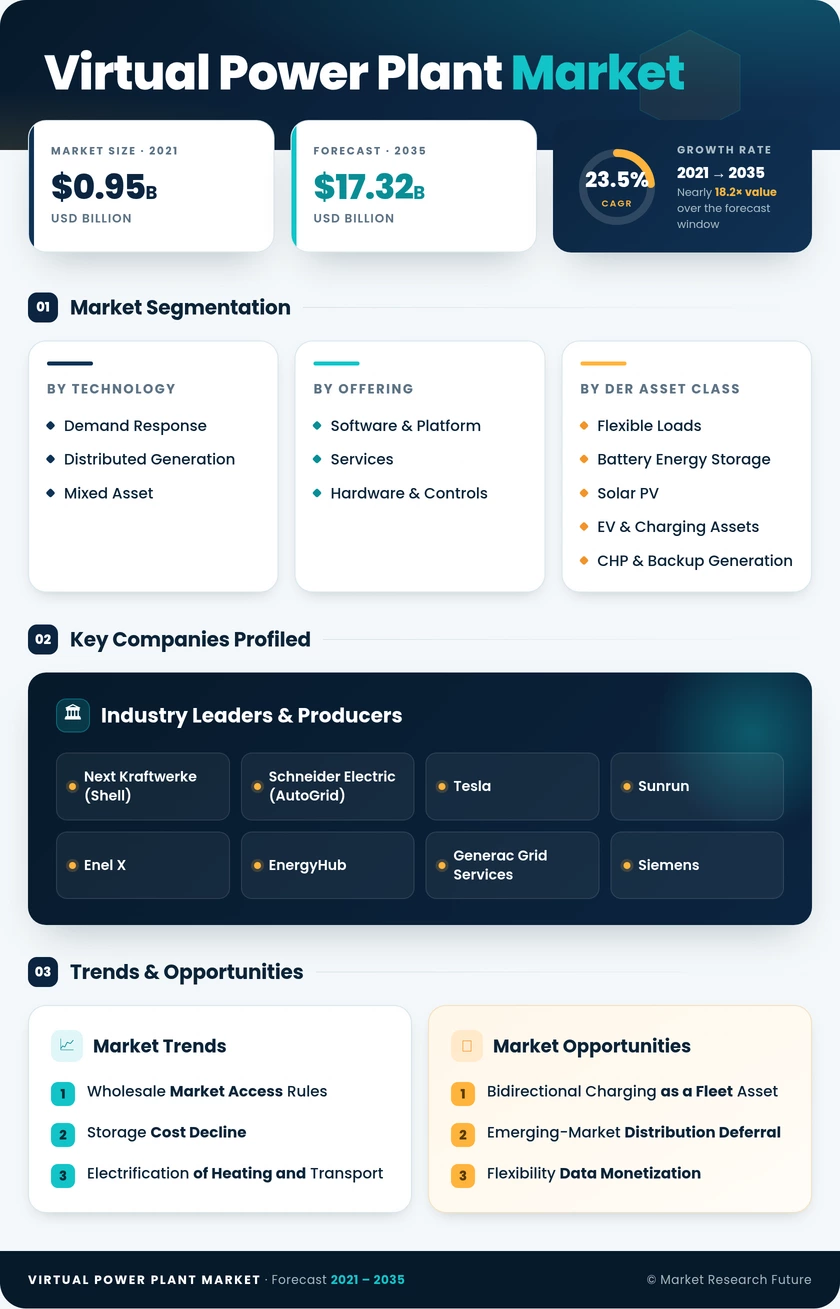
Virtual Power Plant Market (2026 - 2035)

ID: MRFR/EnP/4134-HCR 200 Pages Chitranshi Jaiswal Last Updated: September 15, 2026
Virtual Power Plant Market Research Report By Technology (Demand Response, Distributed Generation, Mixed Asset), By Offering (Software & Platform, Services, Hardware & Controls), By DER Asset Class (Flexible Loads, Battery Energy Storage, Solar PV, EV & Charging Assets, CHP & Backup Generation), By End User (Commercial, Industrial, Residential) - Forecast to 2035
Virtual Power Plant Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)23.5%
2025 Market SizeUSD 2.10 Billion
2035 Market SizeUSD 17.32 Billion
Key Players
Next Kraftwerke
Schneider Electric
Tesla
Sunrun
Enel X
EnergyHub
Opportunities
  • Bidirectional Charging as a Fleet Asset
  • Emerging-Market Distribution Deferral
  • Flexibility Data Monetization
  1. 1 Market Overview | |
    1. 1.1 Study Assumptions & Market Definition | |
    2. 1.2 Scope of the Study | |
    3. 1.3 Research Methodology | |
  2. 2 Market Summary & Key Takeaways | |
    1. 2.1 Key Takeaways by Technology | |
    2. 2.2 Key Takeaways by Sector | |
    3. 2.3 Key Takeaways by Geography | |
  3. 3 Global Market Size & Forecast (2021–2035) | |
    1. 3.1 Historical Market Size (2021–2025) | |
    2. 3.2 Current & Forecast Market Size (2026–2035) | |
    3. 3.3 Year-over-Year Growth Analysis | |
  4. 4 Market Drivers Analysis | |
    1. 4.1 Wholesale Market Access Rules | |
    2. 4.2 Storage Cost Decline | |
    3. 4.3 Electrification of Heating and Transport | |
    4. 4.4 Capacity Adequacy Stress | |
  5. 5 Market Restraints Analysis | |
    1. 5.1 Fragmented Tariff Design | |
    2. 5.2 Acquisition Cost and Churn | |
    3. 5.3 Telemetry and Settlement Latency | |
  6. 6 Market Opportunity Analysis | |
    1. 6.1 Bidirectional Charging as a Fleet Asset | |
    2. 6.2 Emerging-Market Distribution Deferral | |
    3. 6.3 Flexibility Data Monetization | |
    4. 6.4 Grid-Interactive Buildings and Standards Convergence | |
    5. 6.5 Ancillary Products Beyond Frequency | |
    6. 6.6 Industry Value Chain Analysis | |
    7. 6.7 Porter's Five Forces Analysis | |
  7. 7 Regional Analysis | |
    1. 7.1 North America | | |
      1. 7.1.1 United States | | |
      2. 7.1.2 Canada | | |
      3. 7.1.3 Mexico | |
    2. 7.2 Europe | | |
      1. 7.2.1 Germany | | |
      2. 7.2.2 United Kingdom | | |
      3. 7.2.3 France | | |
      4. 7.2.4 Netherlands | | |
      5. 7.2.5 Rest of Europe | |
    3. 7.3 Asia-Pacific | | |
      1. 7.3.1 China | | |
      2. 7.3.2 Japan | | |
      3. 7.3.3 Australia | | |
      4. 7.3.4 India | | |
      5. 7.3.5 South Korea | |
    4. 7.4 South America | | |
      1. 7.4.1 Brazil | | |
      2. 7.4.2 Chile | | |
      3. 7.4.3 Rest of South America | |
    5. 7.5 Middle East & Africa | | |
      1. 7.5.1 United Arab Emirates | | |
      2. 7.5.2 Saudi Arabia | | |
      3. 7.5.3 South Africa | | |
      4. 7.5.4 Rest of Middle East & Africa | |
  8. 8 Future Outlook (2026–2035) | |
    1. 8.1 Autonomous Dispatch | |
    2. 8.2 Platform Economics | |
    3. 8.3 Electrification Supercycle | |
    4. 8.4 Verified Carbon and Reliability Attributes | |
  9. 9 Segmentation Analysis | |
    1. 9.1 By Technology | | |
      1. 9.1.1 Demand Response | | |
      2. 9.1.2 Distributed Generation | | |
      3. 9.1.3 Mixed Asset | |
    2. 9.2 By Offering | | |
      1. 9.2.1 Software & Platform | | |
      2. 9.2.2 Services | | |
      3. 9.2.3 Hardware & Controls | |
    3. 9.3 By DER Asset Class | | |
      1. 9.3.1 Flexible Loads | | |
      2. 9.3.2 Battery Energy Storage | | |
      3. 9.3.3 Solar PV | | |
      4. 9.3.4 EV & Charging Assets | | |
      5. 9.3.5 CHP & Backup Generation | |
    4. 9.4 By End User | | |
      1. 9.4.1 Commercial | | |
      2. 9.4.2 Industrial | | |
      3. 9.4.3 Residential | |
  10. 10 Competitive Landscape | |
    1. 10.1 Market Share Analysis (2026) | |
    2. 10.2 Competitive Benchmarking Matrix | |
    3. 10.3 Company Profiles | | |
      1. 10.3.1 Next Kraftwerke (Shell) | | |
      2. 10.3.2 Schneider Electric | | |
      3. 10.3.3 Tesla | | |
      4. 10.3.4 Sunrun | | |
      5. 10.3.5 Enel X | | |
      6. 10.3.6 EnergyHub | | |
      7. 10.3.7 Generac Grid Services | | |
      8. 10.3.8 Siemens | | |
      9. 10.3.9 Hitachi Energy | | |
      10. 10.3.10 Voltus | |
  11. 11 Recent Developments & News | |
  12. 12 Report Scope & Methodology | |
    1. 12.1 Study Period & Base Year | |
    2. 12.2 Data Sources & Citations | |
    3. 12.3 Abbreviations | |
  13. 13 Detailed Sources and Citations | |
  14. 14 Frequently Asked Questions (FAQs) | | LIST OF TABLES | |
  15. TABLE 1 Global Virtual Power Plant Market Size & Forecast, by Revenue (USD Billion), 2021–2035 | |
  16. TABLE 2 Global Virtual Power Plant Market — Year-over-Year Growth Analysis, 2021–2035 | |
  17. TABLE 3 Driver Impact Analysis — Global Virtual Power Plant Market, 2026–2035 | |
  18. TABLE 4 Restraint Impact Analysis — Global Virtual Power Plant Market, 2026–2035 | |
  19. TABLE 5 Global Market Size, by Region, 2021–2035 (USD Billion) | |
  20. TABLE 6 North America Market Size, by Country, 2021–2035 (USD Billion) | |
  21. TABLE 7 Europe Market Size, by Country, 2021–2035 (USD Billion) | |
  22. TABLE 8 Asia-Pacific Market Size, by Country, 2021–2035 (USD Billion) | |
  23. TABLE 9 South America Market Size, by Country, 2021–2035 (USD Billion) | |
  24. TABLE 10 Middle East & Africa Market Size, by Country, 2021–2035 (USD Billion) | |
  25. TABLE 11 Global Market Size, by Technology, 2021–2035 (USD Billion) | |
  26. TABLE 12 Global Market Size, by Offering, 2021–2035 (USD Billion) | |
  27. TABLE 13 Global Market Size, by DER Asset Class, 2021–2035 (USD Billion) | |
  28. TABLE 14 Global Market Size, by End User, 2021–2035 (USD Billion) | |
  29. TABLE 15 North America Market Size, by Technology and End User, 2021–2035 (USD Billion) | |
  30. TABLE 16 Europe Market Size, by Technology and End User, 2021–2035 (USD Billion) | |
  31. TABLE 17 Asia-Pacific Market Size, by Technology and End User, 2021–2035 (USD Billion) | |
  32. TABLE 18 South America Market Size, by Technology and End User, 2021–2035 (USD Billion) | |
  33. TABLE 19 Middle East & Africa Market Size, by DER Asset Class, 2021–2035 (USD Billion) | |
  34. TABLE 20 Competitive Benchmarking Matrix — Global Virtual Power Plant Market, 2026 | |
  35. TABLE 21 Company Profiles — Key Players | |
  36. TABLE 22 Recent Developments & Strategic Announcements, 2023–2025 | |
  37. TABLE 23 Report Scope & Methodology Summary | |
  38. TABLE 24 Detailed Sources and Citations Index | | LIST OF FIGURES | |
  39. FIGURE 1 Market Dynamics — Drivers, Restraints and Opportunities Snapshot | |
  40. FIGURE 2 Industry Value Chain Analysis | |
  41. FIGURE 3 Porter's Five Forces Assessment | |
  42. FIGURE 4 Global Market Size Trend and Forecast, 2021–2035 | |
  43. FIGURE 5 Year-over-Year Growth Curve, 2022–2035 | |
  44. FIGURE 6 Market Share by Technology, 2025 vs 2035 | |
  45. FIGURE 7 Market Share by Offering, 2025 vs 2035 | |
  46. FIGURE 8 Market Share by DER Asset Class, 2025 | |
  47. FIGURE 9 Market Share by End User, 2025 vs 2035 | |
  48. FIGURE 10 Regional Revenue Share, 2025 | |
  49. FIGURE 11 Regional CAGR Comparison, 2026–2035 | |
  50. FIGURE 12 Country-Level Revenue Contribution — Top Ten Markets, 2025 | |
  51. FIGURE 13 Competitive Landscape Positioning Matrix, 2026 | |
  52. FIGURE 14 Estimated Revenue Share of Leading Players, 2026

Segmentation Quick Reference

DimensionSub-SegmentsDominant SegmentFastest Growing Segment
By TechnologyDemand Response; Distributed Generation; Mixed AssetDemand ResponseMixed Asset
By OfferingSoftware & Platform; Services; Hardware & ControlsSoftware & PlatformHardware & Controls
By DER Asset ClassFlexible Loads; Battery Energy Storage; Solar PV; EV & Charging Assets; CHP & Backup GenerationFlexible LoadsEV & Charging Assets
By End UserCommercial; Industrial; ResidentialCommercialResidential
By RegionNorth America; Europe; Asia-Pacific; South America; Middle East & AfricaNorth AmericaAsia-Pacific


Market Segmentation Overview

By Technology

Sub-SegmentKey Trend
Demand ResponseEstablished baselines and settlement rules allow rapid utility scaling without new tariff design.
Distributed GenerationRooftop solar and combined heat and power increasingly bid as coordinated portfolios.
Mixed AssetBlended generation-and-load stacks capture energy, capacity and reserve revenue simultaneously.


Technology mix is migrating from single-product curtailment toward orchestrated portfolios. Operators that can co-optimize across markets defend margin as any individual product saturates, and this is the clearest structural shift visible in the forecast window.

By Offering

Sub-SegmentKey Trend
Software & PlatformSubscription and dispatch-fee models drive recurring revenue and high gross margin.
ServicesProgram design, enrollment and market operations increasingly outsourced by regulated utilities.
Hardware & ControlsGateways, submeters and bidirectional chargers grow fastest as telemetry requirements tighten.


Value concentrates in software because incremental device onboarding costs almost nothing once integrations exist. Hardware grows quickly from a small base, driven mainly by settlement-grade metering and vehicle charging equipment.

By DER Asset Class

Sub-SegmentKey Trend
Flexible LoadsLowest cost per controllable kilowatt; thermal inertia supports short-duration events
Battery Energy StorageFalling pack prices enable firm four-hour capacity bids rather than probabilistic curtailment.
Solar PVExport management and curtailment mitigation add value beyond generation.
EV & Charging AssetsBidirectional standards and depot fleets unlock large evening capacity blocks.
CHP & Backup GenerationIndustrial resilience contracts monetize otherwise idle standby assets.


Asset mix determines which market products an operator can sell. Batteries and vehicles command premium pricing because they deliver firm, verifiable response, while flexible loads remain the volume backbone of most portfolios.

By End User

Sub-SegmentKey Trend
CommercialSingle contracts deliver megawatts through existing building management systems.
IndustrialProcess load shifting and on-site generation support high-value, low-frequency dispatch
ResidentialRising storage attachment rates convert passive customers into dispatchable fleets.


End-user economics diverge sharply. Commercial and industrial contracts scale with fewer counterparties, while residential portfolios carry higher acquisition cost but deliver the diversity and geographic spread that distribution-level flexibility products require.




Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.