Thermal Power Plant Market (2026 - 2035)

Thermal Power Plant Market Research Report By Fuel Type (Coal, Gas, Nuclear, Others) - Forecast to 2035
ID: MRFR/EnP/21690-HCR 100 Pages Snehal Singh Last Updated: September 17, 2026
Thermal Power Plant Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)0.62%
2025 Market SizeUSD 1,412.6 Billion
2035 Market SizeUSD 1,505.9 Billion
Key Players
GE Vernova
Siemens Energy
Mitsubishi Heavy Industries
Dongfang Electric
Harbin Electric
Shanghai Electric
Opportunities
  • Flexibility Retrofits and Ancillary Service Revenue
  • Emerging-Market Greenfield and Repowering Programmes
  • Hydrogen and Ammonia Co-Firing

Thermal Power Plant Market Summary

The Thermal Power Plant Market reached USD 1,412.6 billion in 2025 and opens the forecast window at USD 1,421.4 billion in 2026, advancing to USD 1,505.9 billion by 2035 at a CAGR of 0.62% between 2026 and 2035. Growth is deliberately slow because the asset base is mature, but it is not flat — capacity additions in South and Southeast Asia offset retirements across the OECD. India's National Electricity Plan (NEP-2023) commits roughly 80 GW of new coal-fired capacity by 2032, while the U.S. Inflation Reduction Act's 45Q provision offers USD 85 per tonne for sequestered carbon dioxide, redirecting capital toward capture retrofits rather than greenfield builds [1][3].

Technology substitution inside the Thermal Power Plant Market matters more than headline volume. Subcritical units built in the 1970s and 1980s are being replaced by ultra-supercritical steam cycles operating above 600°C and by H- and J-class gas turbines exceeding 64% net efficiency. The International Energy Agency estimates global fossil-fired generation investment at roughly USD 118 billion annually through 2030, with a rising share tied to flexibility upgrades rather than new capacity [1].

Asia-Pacific dominates the Thermal Power Plant Market with 58.2% of 2025 revenue, and it is also the fastest-growing region at a 1.34% CAGR. North America ranks second, supported by gas-fired capacity serving data-centre load growth that PJM interconnection queues now price at a premium. The next decade rewards operators who convert baseload fleets into dispatchable balancing assets.

Key Report Takeaways

• By Fuel Type

  • Coal remains the anchor of the Thermal Power Plant Market, holding 51.8% of 2025 global revenue despite accelerating OECD retirements.
  • Gas is the fastest-expanding fuel type at a 2.41% CAGR through 2035, driven by lower capital intensity and superior ramp rates.
  • Nuclear contributes approximately USD 268.4 billion in 2025 revenue, with life-extension programmes sustaining the installed base.

• By Region

  • Asia-Pacific leads the Thermal Power Plant Market at 58.2% share, concentrated in China, India and Indonesia
  • Middle East & Africa posts a 1.12% CAGR, the second-fastest regional rate, on Gulf gas expansion
  • Europe holds 11.4% share, the steepest structural decline among all regions

Market Size and Forecast (2021–2035)

Market sizing draws on installed capacity registries, utility annual reports, national grid operator dispatch data, and equipment order books from OEMs, triangulated against IEA and EIA generation statistics. Revenue reflects capacity payments, energy sales, fuel pass-through, and aftermarket service contracts attributable to thermal generating assets.
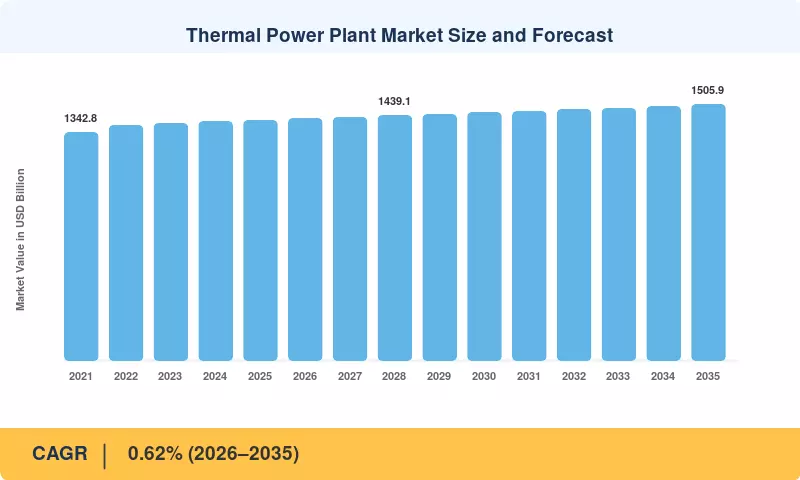
Thermal Power Plant Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Data-centre and electrification load growth +0.31 North America, Asia-Pacific Short-term (≤2 yr)
Emerging-economy capacity additions +0.28 Asia-Pacific, MEA Long-term (≥4 yr)
Grid balancing demand from renewables +0.22 Europe, North America Medium-term (2–4 yr)
Ultra-supercritical efficiency upgrades +0.17 Asia-Pacific Medium-term (2–4 yr)
Gas turbine fleet expansion +0.19 North America, MEA Short-term (≤2 yr)
Nuclear life-extension programmes +0.14 Europe, North America Long-term (≥4 yr)
Carbon capture retrofit incentives +0.11 North America Long-term (≥4 yr)


Data-Centre and Electrification Load Growth

Hyperscale computing has reversed a decade of flat electricity demand in mature economies. The U.S. Energy Information Administration projects commercial-sector electricity sales rising 3.1% annually through 2027, with data centres accounting for the majority of incremental load. PJM's 2025 capacity auction cleared at USD 329.17 per MW-day, roughly nine times the prior cycle, signalling acute scarcity that gas-fired plants are best positioned to monetise near-term [2][7].

Emerging-Economy Capacity Additions

India's National Electricity Plan targets approximately 80 GW of incremental coal capacity by 2032, backed by roughly USD 33 billion of committed utility capital expenditure. Indonesia and Vietnam continue commissioning units approved before financing restrictions tightened. These additions sustain volume growth that offsets the roughly 21 GW of annual OECD retirements, keeping global installed thermal capacity broadly stable through the forecast window [3][10].

Grid Balancing Demand from Renewables

Rising variable renewable penetration converts thermal assets from energy providers into flexibility providers. Germany's grid operators dispatched roughly 33 TWh of redispatch volume in 2024, most of it from gas and hard-coal units, at a system cost near EUR 2.8 billion. Capacity mechanisms in Poland, Italy and the United Kingdom now pay for availability rather than output, creating a revenue stream that is largely decoupled from generation volume [8][11].

Ultra-Supercritical Efficiency Upgrades

China has commissioned more than 200 ultra-supercritical units operating above 600°C, achieving net efficiencies near 45% against a subcritical baseline of roughly 33%. Each percentage point of efficiency gain reduces coal consumption by approximately 2.3%, materially lowering fuel cost and compliance exposure. Chinese regulators require new units to meet a 300 gce/kWh coal consumption standard, which effectively mandates advanced steam cycles [6][12].

Gas Turbine Fleet Expansion

Order books at leading turbine OEMs recorded roughly 22 GW of heavy-duty gas turbine bookings during 2024, the strongest year since 2015. Advanced-class machines deliver combined-cycle net efficiency above 64% while cutting carbon intensity to roughly 350 kg per MWh — around 60% below a typical subcritical coal unit. Gulf utilities and U.S. independent power producers account for the majority of these commitments [13].

Nuclear Life-Extension Programmes

Regulators have approved subsequent licence renewals extending U.S. reactor operation to 80 years, with per-unit refurbishment budgets in the USD 400–700 million range. France's EDF Grand Carénage programme carries a EUR 49.4 billion envelope through 2028 covering steam generator replacement and safety upgrades. Extending an existing reactor costs roughly one-fifth of new-build capacity per installed kilowatt, making life extension the dominant nuclear investment path [9][14].

Carbon Capture Retrofit Incentives

Section 45Q of the U.S. tax code pays USD 85 per tonne for geologically sequestered carbon dioxide from power generation, transforming retrofit economics on high-capacity-factor units. The Department of Energy's Carbon Capture Demonstration Projects Program allocated roughly USD 2.5 billion to commercial-scale installations at coal and gas facilities. Capture retrofits extend asset life under tightening emissions rules rather than expanding capacity [5][15].

Restraints Impact Analysis

Restraint impacts are directional estimates of drag on the growth rate. They interact with one another — financing constraints and policy pressure reinforce each other — so the values should not be summed against the driver table.

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
Coal phase-out policy commitments −0.34 Europe, North America Medium-term (2–4 yr)
Renewable cost deflation −0.29 Global Short-term (≤2 yr)
Capital access and insurance withdrawal −0.21 Global Short-term (≤2 yr)
Carbon pricing and compliance cost −0.18 Europe Medium-term (2–4 yr)
Declining capacity factors −0.15 Europe, North America Long-term (≥4 yr)


Coal Phase-Out Policy Commitments

More than 60 national and subnational governments have set coal exit dates, with Germany legislating 2038 and the United Kingdom having closed its last plant in September 2024. The U.S. Environmental Protection Agency's 2024 greenhouse gas rule requires 90% capture on units running past 2039, a threshold most operators treat as an implicit retirement deadline [11][18].

Renewable Cost Deflation

Utility-scale solar levelised cost fell to roughly USD 42 per MWh globally in 2024, undercutting the marginal running cost of many coal units. Four-hour battery storage system prices dropped below USD 165 per kWh, eroding the peaking premium that previously protected thermal margins. Merit-order displacement now begins earlier in the dispatch stack each year [16].

Capital Access and Insurance Withdrawal

Over 45 major insurers have restricted underwriting for new coal projects, and more than 200 financial institutions maintain coal exclusion policies. Weighted average cost of capital for unabated coal projects has risen roughly 380 basis points since 2019 in most markets. Higher financing costs materially compress project internal rates of return and delay final investment decisions [17].

Carbon Pricing and Compliance Cost

The average price of European Union Allowances in 2024 was around EUR 68 per ton, adding almost EUR 62 per MWh to the marginal cost of a mid-efficiency coal unit. Similar pressure is being applied to trade-exposed industrial power consumers using the Carbon Border Adjustment Mechanism. The dispatch order is increasingly being set by compliance economics rather than just by fuel cost [11].


Declining Capacity Factors

In OEDC Europe, average coal capacity factors decreased to 32% in 2024, compared with over 50% a decade earlier, meaning fixed expenditures were divided over fewer megawatt-hours of output. Less use means higher maintenance costs per unit and speeds up thermal cycling damage to boilers and turbines. Several operators are reporting negative gross margins on units running less than 25% utilization [1].


Thermal Power Plant Market Opportunities

Flexibility Retrofits and Ancillary Service Revenue

The most obvious value pool in the near-term is to turn baseload units into fast-ramping balancing assets. Units are eligible for frequency response and reserve markets with minimum stable load reductions from 50% to 20% of rated output and ramp rate improvements to 4%/minute. European ancillary service markets have expanded to over EUR 8 billion yearly, with thermal plants claiming the bulk of that cost.


Emerging-Market Greenfield and Repowering Programmes

Southeast Asia, Sub-Saharan Africa and South Asia combined require about 190 GW of firm capacity by 2035 to meet demand growth and dependability requirements. Bangladesh, the Philippines and Nigeria have active procurement pipelines where gas-fired capacity is competing with imported coal. In these markets, vendors that provide integrated engineering, procurement and finance packages win disproportionately.


Hydrogen and Ammonia Co-Firing

Turbine OEMs now offer machines certified for 30% hydrogen blending with a path to 100% by 2030, while Japanese utilities have demonstrated 20% ammonia co-firing at commercial coal units. Japan's Green Innovation Fund has allocated roughly JPY 68 billion to co-firing scale-up. Co-firing preserves asset value under decarbonisation mandates without requiring full replacement.

Digital Performance Monitoring and Outcome-Based Contracts

Sensor-instrumented turbines and boilers generate operational data that OEMs monetise through availability-guaranteed service agreements. These contracts shift revenue from parts sales to recurring performance fees, typically worth USD 4–9 million annually per gigawatt under management. Predictive maintenance analytics have reduced forced outage rates by 20–30% at instrumented sites, creating a data-driven aftermarket business model.

Carbon Capture as a Service

Third-party developers are financing, building and operating capture trains at host power plants under long-term tolling agreements, removing balance-sheet burden from utilities. This structure has already been applied to gas-fired assets in Alberta and the U.S. Gulf Coast. Host plants gain compliance certainty while capture operators monetise 45Q credits and enhanced oil recovery offtake.

Thermal Power Plant Market Future Outlook

Autonomous Plant Operations

Control room headcount is falling as advanced process control and machine learning take over combustion optimisation, soot-blowing schedules and load-following logic. Utilities deploying closed-loop optimisation report heat rate improvements of 1.5–2.5% and nitrogen oxide reductions near 15% without hardware changes. The Electric Power Research Institute estimates digital optimisation can defer roughly USD 1.2 million per unit in annual maintenance spend, and vendor roadmaps point toward minimally attended operation for combined-cycle assets by the early 2030s [6][21].

The Firm Capacity Premium

Energy-only markets are giving way to designs that pay explicitly for dependable capacity. As renewable penetration passes 40% in several major systems, scarcity pricing becomes volatile enough that regulators intervene with capacity mechanisms. Thermal plants running at 25% utilisation can remain profitable when availability payments cover fixed costs — a structural change that decouples plant economics from generation volume and preserves fleets that pure energy-market economics would retire [8].

Fuel Transition Pathways

Blending pathways will determine which assets survive past 2035. The International Renewable Energy Agency projects green hydrogen production costs falling to roughly USD 1.9 per kilogram by 2035 in favourable geographies, which brings blended gas turbine operation within range of carbon-priced alternatives. Ammonia co-firing offers coal units a parallel route, particularly across Japan and South Korea where import infrastructure already exists for other commodities [13][22].

Emissions Disclosure and Asset Valuation

Mandatory climate reporting under IFRS S2 and the EU Corporate Sustainability Reporting Directive forces utilities to disclose asset-level emissions and transition plans. Disclosure changes valuation: investors increasingly discount unabated thermal assets on remaining economic life rather than nameplate life. This dynamic accelerates the split between capture-equipped or gas-fired assets that retain terminal value and unabated coal units written down toward zero [11][23].

Regional Market Share Analysis

Region Metric Primary Investment Themes
North America USD 268.4 Billion (2025) Gas peaking, capture retrofits, data-centre supply
Asia-Pacific 58.2% share (2025) Ultra-supercritical builds, coal fleet expansion
Europe 11.4% share (2025) Retirement management, capacity mechanisms
South America 0.91% CAGR (2026–2035) Hydro backup, gas-fired firming
Middle East & Africa 1.12% CAGR (2026–2035) Gas expansion, desalination cogeneration
Total USD 1,412.6 Billion (2025) —


North America

Country Metric Key Driver
US 78.4% of region Data-centre load, 45Q retrofit credits
Canada USD 34.9 Billion Alberta gas cogeneration, hydro balancing
Mexico 1.68% CAGR CFE combined-cycle expansion


North American thermal generation has been reshaped by demand that nobody forecast five years ago. ERCOT and PJM both report interconnection queues dominated by load rather than supply, and gas-fired assets slated for retirement have received extension requests from grid operators. The Federal Energy Regulatory Commission's Order 1920 on transmission planning indirectly supports thermal retention by acknowledging resource adequacy gaps. Canada's federal Clean Electricity Regulations set a 2035 emissions threshold that channels investment toward capture-equipped gas rather than new unabated capacity [7][15].

Europe

Country Metric Key Driver
Germany 23.1% of region Redispatch and reserve capacity payments
UK USD 19.4 Billion Capacity market gas procurement
France 0.42% CAGR Nuclear fleet life extension
Italy 11.8% of region Combined-cycle balancing role
Spain USD 8.7 Billion Gas firming for solar-heavy grid
Nordic Countries 3.9% of region Combined heat and power district systems
Russia USD 31.2 Billion Domestic gas-fired baseload
Rest of Europe 6.4% of region Coal-to-gas conversion projects


European operators are managing decline rather than growth, and the commercial question is how to extract value from assets during a defined runway. Germany's Kraftwerkssicherheitsgesetz framework proposes tendering roughly 12.5 GW of new hydrogen-ready gas capacity to replace existing coal. Capacity remuneration mechanisms in Italy, Poland and the United Kingdom now provide a meaningful share of thermal plant gross margin, insulating operators from thin energy-market spreads [8][11].

Asia-Pacific

Country Metric Key Driver
China 54.6% of region Ultra-supercritical fleet, capacity pricing reform
India USD 168.3 Billion National Electricity Plan coal additions
Japan 8.2% of region Ammonia co-firing, LNG combined cycle
South Korea 1.04% CAGR Fleet modernisation, emissions retrofits
ASEAN USD 71.5 Billion Indonesia and Vietnam capacity commissioning
Rest of Asia-Pacific 3.1% of region Bangladesh and Pakistan gas procurement


Asia-Pacific is where thermal generation still grows in absolute terms. China introduced a two-part capacity pricing mechanism in 2024 that pays coal plants for availability, explicitly repositioning them as system backup for a renewable-heavy grid. India's regulator has directed that no thermal unit be retired before 2030 given reserve margin tightness, while simultaneously mandating flue gas desulphurisation retrofits across the fleet. Both policies extend asset life and sustain aftermarket spending [3][6][12].

South America

Country Metric Key Driver
Brazil 61.3% of region Hydrological risk backup generation
Argentina USD 12.6 Billion Vaca Muerta gas-fired expansion
Rest of South America 1.22% CAGR Chile and Colombia firming capacity


South American thermal demand is driven by hydrology. Brazil dispatches thermal capacity when reservoir levels fall, and the 2021 drought demonstrated how quickly reserve capacity becomes essential, with emergency procurement clearing above USD 190 per MWh—Argentina's Plan Gas. Ar programme underwrites domestic gas supply that feeds combined-cycle expansion around Buenos Aires. Regional interconnection remains limited, which sustains national-level firm capacity requirements [10][19].

Middle East & Africa

Country Metric Key Driver
Saudi Arabia 34.8% of region Liquids-to-gas displacement programme
UAE USD 21.3 Billion Combined-cycle and cogeneration capacity
South Africa 1.41% CAGR Eskom fleet recovery and maintenance
Egypt 12.6% of region Grid expansion and gas-fired additions
Rest of MEA USD 18.9 Billion Nigeria and Morocco capacity growth


Gulf utilities are executing a systematic substitution of crude and heavy fuel oil with natural gas in power generation, freeing liquids for export. Saudi Arabia's programme targets full liquids displacement by 2030, requiring several gigawatts of new combined-cycle capacity. South Africa's Eskom has stabilised its energy availability factor above 60% after a sustained maintenance push, unlocking deferred capital for boiler and turbine refurbishment across its coal fleet [20].

Thermal Power Plant Market By Region, 2025-2035

Thermal Power Plant Market Segmentation

By Fuel Type

Segment Metric Primary Demand Driver
Coal 51.8% share (2025) Asian baseload demand and capacity payments
Gas 2.41% CAGR (2026–2035) Flexibility, lower emissions intensity, fast build
Nuclear USD 268.4 Billion (2025) Life extension and firm low-carbon supply
Others 3.2% share (2025) Biomass co-firing, oil-fired peaking, waste-to-energy


Coal continues to anchor the Thermal Power Plant Market through sheer installed base, particularly across China and India where capacity mechanisms now underwrite units that energy-market economics alone would not support. Gas grows fastest because it solves three problems at once — build speed, ramp rate and emissions intensity — with advanced combined-cycle machines reaching net efficiency above 64%. Nuclear revenue holds steady on refurbishment spending rather than new construction, while Others remains a niche shaped by local fuel availability and waste policy.

Competitive Benchmarking

The Thermal Power Plant Market is highly concentrated on the equipment side and fragmented on the ownership side. Among original equipment manufacturers, the estimated Herfindahl-Hirschman Index sits near 1,850, with the top five suppliers accounting for roughly 62–68% of new turbine and boiler island orders. Barriers to entry are severe: metallurgical expertise for high-temperature components, installed-base service relationships spanning decades, and export credit relationships that shape emerging-market awards. Chinese state-owned manufacturers dominate domestic volume but compete selectively abroad, while Western OEMs concentrate on high-efficiency gas turbines and aftermarket services.

Company Est. Revenue Share Range Key Offerings for Thermal Power Plant Market Strategic Positioning
GE Vernova ~14–18% HA-class gas turbines, steam turbines, capture integration Leader in advanced-class gas turbine efficiency
Siemens Energy ~12–16% HL-class turbines, grid stabilisation, plant digitalisation Strong European service base, hydrogen-ready portfolio
Mitsubishi Heavy Industries ~10–14% JAC gas turbines, ultra-supercritical boilers, ammonia co-firing Leads ammonia and hydrogen combustion development
Dongfang Electric ~7–10% Ultra-supercritical boilers and steam turbine islands Dominant in Chinese domestic capacity additions
Harbin Electric ~6–9% Coal-fired boiler islands, turbine generators Major supplier to Belt and Road power projects
Shanghai Electric ~6–9% Full thermal island EPC, supercritical units Integrated EPC and equipment delivery
Doosan Enerbility ~4–6% Boilers, turbines, nuclear steam supply systems Korean champion pivoting to nuclear and hydrogen
BHEL ~4–6% Supercritical boilers, turbogenerators, retrofits Anchor supplier to India's national capacity plan
Toshiba Energy Systems ~3–5% Steam turbines, geothermal and nuclear systems Focused on Japanese and Asian service contracts
Ansaldo Energia ~2–4% GT36 gas turbines, plant upgrades, service Independent European alternative in mid-size gas
Wärtsilä ~2–4% Engine-based flexible generation, balancing plants Specialist in fast-start reciprocating capacity


Recent News & Developments

  • U.S. Environmental Protection Agency (April 2024): Finalised greenhouse gas standards requiring 90% carbon capture on coal units operating beyond 2039, effectively setting a retirement or retrofit decision deadline for the U.S. fleet [18]
  • National Development and Reform Commission, China (January 2024): Implemented a two-part capacity pricing mechanism paying coal plants for availability, reclassifying the fleet as system backup and stabilising operator revenue [12]
  • Mitsubishi Heavy Industries and JERA (June 2024): Completed a 20% ammonia co-firing demonstration at the Hekinan coal plant, validating a decarbonisation retrofit path for existing Asian coal capacity [13]
  • GE Vernova (September 2024): Reported heavy-duty gas turbine orders at their highest level in nearly a decade, citing North American data-centre demand and Gulf capacity procurement
  • Siemens Energy (March 2025): Announced expansion of gas turbine manufacturing capacity in response to multi-year order backlog extending beyond 2028
  • PJM Interconnection (July 2025): Capacity auction cleared at USD 329.17 per MW-day, a roughly ninefold increase that triggered retirement deferrals across the thermal fleet [7]
  • Central Electricity Authority, India (February 2025): Directed that thermal units be retained beyond previously notified retirement dates, pending reserve margin improvement under the National Electricity Plan [3]
  • U.S. Department of Energy (November 2024): Advanced funding under the Carbon Capture Demonstration Projects Program to commercial-scale installations at operating coal and gas facilities [15]

Thermal Power Plant Market Report Scope

Parameter Detail
Market Scope Global thermal power generation including coal, gas, nuclear and other fuel-based capacity; covers generation revenue, capacity payments, equipment and aftermarket services
Study Period 2021–2035 (Historical 2021–2024; Base Year 2025; Forecast 2026–2035)
CAGR 0.62% (2026–2035)
Market Size Checkpoints USD 1,412.6 Billion (2025); USD 1,421.4 Billion (2026); USD 1,457.0 Billion (2030); USD 1,505.9 Billion (2035)
Fastest Growing Segments Gas (Fuel Type, 2.41% CAGR); Asia-Pacific (Region, 1.34% CAGR)
Companies Profiled GE Vernova, Siemens Energy, Mitsubishi Heavy Industries, Dongfang Electric, Harbin Electric, Shanghai Electric, Doosan Enerbility, BHEL, Toshiba Energy Systems, Ansaldo Energia, Wärtsilä
Valuation Currency USD (Billion), constant 2025 exchange rates

FAQs

How should a buyer evaluate a flexibility retrofit business case in the Thermal Power Plant Market?
Compare projected ancillary service revenue against accelerated component fatigue cost, since cycling shortens boiler and rotor life. Most viable cases show payback under five years where reserve markets are liquid [8].
What contractual terms matter most when procuring long-term service agreements?
Availability guarantees, parts pricing escalation caps, and technology-refresh clauses determine lifetime cost more than headline fee. Negotiate data ownership explicitly — OEMs increasingly monetise plant telemetry [21].
Which is the better investment today in the Thermal Power Plant Market, combined-cycle gas or ultra-supercritical coal?
Gas wins in carbon-priced markets on lower emissions exposure and faster construction. Coal remains defensible only where domestic fuel is cheap, and capacity payments are secured .
What are the main integration challenges when adding carbon capture to an existing plant?
Steam extraction for solvent regeneration cuts net output by 15–20%, and most sites lack the physical footprint for capture trains. Transport and storage access is the binding constraint [15].
How does hydrogen readiness affect turbine procurement decisions in the Thermal Power Plant Market?
Hydrogen-ready machines carry a modest premium but avoid costly combustor replacement later. Verify the certified blend percentage and the vendor's contractual upgrade commitment rather than marketing claims [13].
What regulatory nuance most often surprises new entrants?
Emissions rules frequently apply thresholds based on operating hours or capacity factor, not just technology. Units can escape stringent standards by staying below utilisation limits, which reshapes dispatch strategy [18].
Are aftermarket services a reliable revenue stream as fleets shrink?
Yes — declining utilisation increases cycling damage and inspection frequency, sustaining parts demand even as generation falls. Service revenue per gigawatt has risen despite fleet contraction in Europe [6].
Author
Author Author Profile Snehal Singh LinkedIn Manager - Research
High acumen in analyzing complex macro & micro markets with more than 6 years of work experience in the field of market research. By implementing her analytical skills in forecasting and estimation into market research reports, she has expertise in Packaging, Construction, and Equipment domains. She handles a team size of 20-25 resources and ensures smooth running of the projects, associated marketing activities, and client servicing.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of regulatory databases, industry publications, government energy reports, and authoritative power sector organizations. Key sources included the International Energy Agency (IEA), US Energy Information Administration (EIA), European Environment Agency (EEA), World Energy Council (WEC), International Atomic Energy Agency (IAEA), International Renewable Energy Agency (IRENA), US Environmental Protection Agency (EPA), National Energy Technology Laboratory (NETL), Central Electricity Authority (CEA) of India, China Electricity Council (CEC), International Electrotechnical Commission (IEC), Power Engineering International, Gas Turbine World, and national energy ministry reports from key markets. These sources were used to collect installed capacity statistics, regulatory policy frameworks, emissions compliance data, technology adoption trends, and market landscape analysis for coal-fired, natural gas, biomass, and oil-based thermal power generation technologies.


Primary Research

In order to gather both qualitative and quantitative insights, supply-side and demand-side stakeholders were interviewed during the primary research process. CEOs, VPs of Engineering, heads of regulatory affairs, and commercial directors from EPC contractors, turbine/generator manufacturers, and thermal power plant OEMs were examples of supply-side sources. Chief operating officers of independent power producers (IPPs), utility directors, grid operators, procurement leads from state-owned power utilities, and representatives of the energy ministry from important thermal power markets were examples of demand-side sources. Market segmentation, technology rollout schedules, fuel switching trends, investments in efficiency upgrades, and the effects of carbon pricing were all confirmed by primary research.

Primary Respondent Breakdown:

By Designation: C-level Primaries (28%), Director Level (32%), Others (40%)

By Region: North America (32%), Europe (25%), Asia-Pacific (33%), Rest of World (10%)


Market Size Estimation

Global market valuation was derived through revenue mapping and installed capacity analysis. The methodology included:

Identification of 50+ key manufacturers and EPC contractors across North America, Europe, Asia-Pacific, Middle East & Africa, and Latin America

Technology mapping across conventional, supercritical, ultra-supercritical, and IGCC systems

Fuel type segmentation across coal, natural gas, biomass, and oil-based installations

Analysis of reported and modeled annual revenues specific to thermal power plant equipment and services

Coverage of manufacturers representing 75-80% of global market share in 2024

Extrapolation using bottom-up (installed capacity × capital cost by country/technology) and top-down (manufacturer revenue validation) approaches to derive segment-specific valuations

Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.


















