Telecom Analytics Market Summary
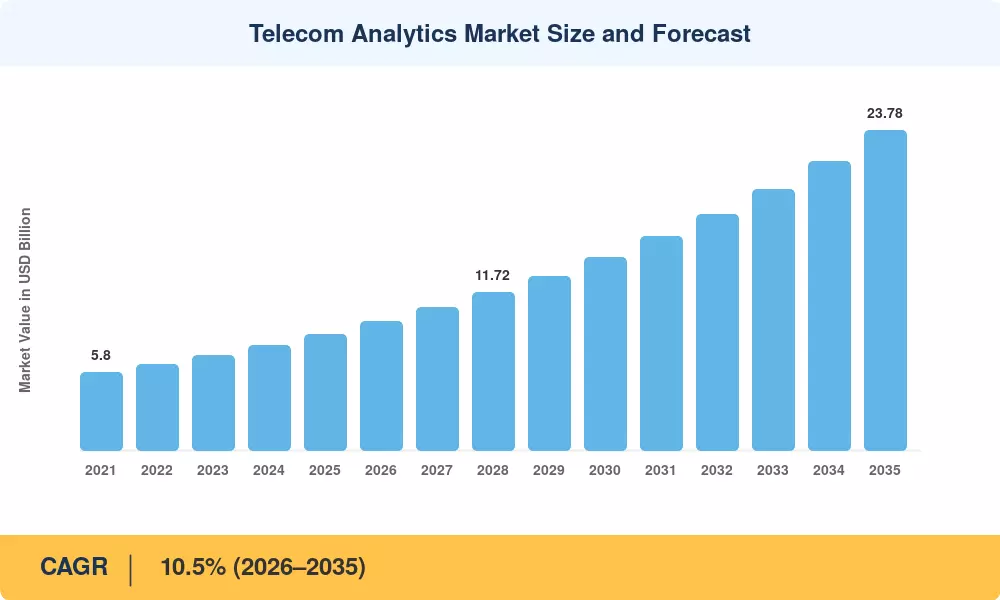
The Telecom Analytics Market was valued at USD 8.65 billion in 2025 and is projected to grow from USD 9.68 billion in 2026 to USD 23.78 billion by 2035, registering a CAGR of 10.5% during the forecast period (2026–2035). Accelerating 5G stand-alone network deployments across forty-plus countries has driven an exponential surge in network telemetry data, compelling operators to replace legacy reporting dashboards with AI-driven decision engines capable of sub-second response . The European Commission's Digital Decade programme and the US CHIPS and Science Act both earmark funding that indirectly channels billions toward data-infrastructure modernization, reinforcing operator budgets for advanced analytics platforms [2].
Cloud-native, microservices-based analytics architectures are replacing legacy BSS/OSS stacks, many of which are still operating on batch-processed data warehouses. Between 2024 and 2027, operators including Deutsche Telekom and Jio Platforms have pledged more than USD 1.2 billion for real-time data-fabric deployments . By reducing mean-time-to-repair by up to 38%, closed-loop automation—in which analytics engines identify an anomaly and initiate remediation without human intervention—is transforming analytics from a cost center into a tool for revenue protection [4].
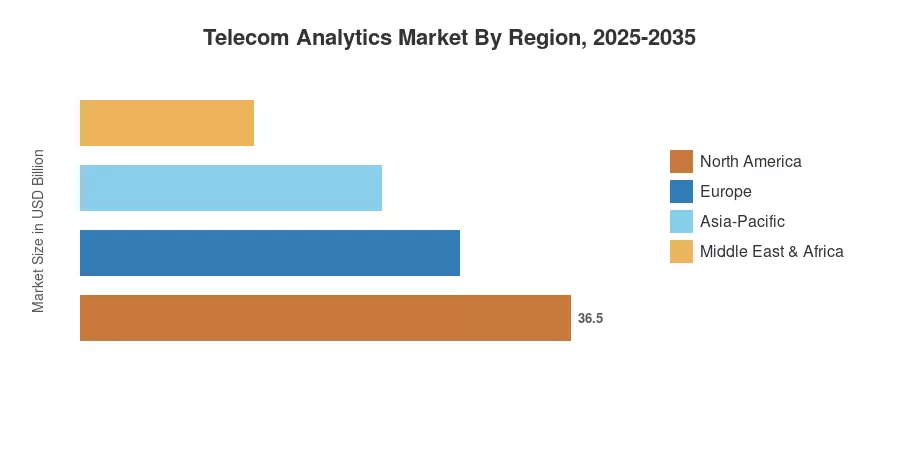
With roughly 37.2% of 2025 revenue, North America dominates the telecom analytics market thanks to early hyperscaler alliances and significant spectrum-auction spending. With a predicted 13.7% CAGR through 2035, Asia-Pacific is the fastest-growing area thanks to the enormous growth in mobile subscribers in Southeast Asia and India. With a roughly 26.5% share, Europe comes in second because of GDPR-mandated data-governance frameworks that, ironically, increase the stack of analytics tools. Over the next ten years, the confluence of edge computing, network slicing, and generative AI is expected to change the competitive landscape completely.
Key Report Takeaways
• By Application
- Customer Analytics commanded roughly 30.1% of the Telecom Analytics Market in 2025, driven by operators' need to personalize retention offers and reduce post-paid churn below 1.5% monthly.
- Network Analytics is expanding at a 13.1% CAGR through 2035, reflecting demand for real-time fault correlation across virtualized 5G core networks.
- Fraud Analytics captured an estimated USD 0.78 billion in 2025 as SIM-swap and subscription fraud losses exceeded USD 39 billion industry-wide.
• By Component & Deployment
- Software accounted for approximately 76.3% of the 2025 Telecom Analytics Market size, with platforms embedding pre-built ML models for demand forecasting.
• By Deployment
- Cloud deployment held about 71.2% share in 2025, although Edge and Hybrid configurations are growing at a 12.1% CAGR as data-residency mandates fragment purely cloud-first strategies.
• By Geography
- North America generated the largest revenue share in 2025 at 37.2%, anchored by Tier-1 operator spend exceeding USD 3.2 billion.
- Asia-Pacific is forecast to register a 13.7% CAGR through 2035, led by India's 5G subscriber base surpassing 350 million by late 2025.
Telecom Analytics Market Size and Forecast (2021–2035)
Market Research Future's estimates integrate primary operator surveys, vendor revenue disclosures, and third-party benchmarks. Historical figures (2021–2024) reflect verified deployment data; forecast values (2026–2035) are modeled at a constant 10.5% CAGR, incorporating demand-side adjustments for 5G monetization cycles and regulatory headwinds.




 Noah Malgeri
Co-Founder

 Peter Groot koerkamp
Account and Business Manager

 Younghwan Choi
Senior Retail Manager

 Mark Irwin
Management Consultant

 Akif Moroglu
Strategy & Business Development Director

 Guilherme Gomes Martins
Product Management Director

 Joseph Aguayo
Sales Operations & Pricing Manager

 La Terria Dodd
Program Support Specialist

 Rob Kooiker
Group Product Manager HVAC & Fire Protection GMA



