Proppants Market (2026 - 2035)

Proppants Market Research Report Information By Product Type (Frac Sand, Resin Coated, and Ceramics), By Application (Onshore and Offshore), and By Region (North America, Europe, Asia-Pacific, Latin America, and Middle East & Africa) – Forecast Till 2035
ID: MRFR/CnM/9075-HCR
180 Pages
Anshula Mandaokar
Last Updated: August 24, 2026
Proppants Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)4.6%
2025 Market SizeUSD 9.50 Billion
2035 Market SizeUSD 14.91 Billion
Key Players
Covia Holdings
U.S. Silica Holdings
Hi-Crush Inc.
Saint-Gobain
CARBO Ceramics
Badger Mining Corporation
Opportunities
  • Ceramic Proppant Adoption in High-Pressure Reservoirs
  • Localized Manufacturing in Emerging Economies
  • Digital Supply-Chain Optimization and Data Monetization

Proppants Market Summary

The global Proppants Market stood at an estimated USD 9.50 billion in 2025 and is projected to grow from USD 9.94 billion in 2026 to USD 14.91 billion by 2035, registering a CAGR of 4.6% across the forecast window. This expansion is rooted in rising upstream capital expenditure cycles across major oil-producing nations, with the U.S. Department of Energy's sustained funding for unconventional resource development acting as a structural demand anchor [1]. Operators are drilling longer laterals and deploying higher-intensity completions, pushing per-well proppant consumption to record levels that continue to reshape supply chain logistics.

The Proppants Market is witnessing a clear product-mix evolution. Conventional uncoated frac sand — long the default choice for most completion designs — is gradually sharing well-site tonnage with engineered alternatives. Resin-coated proppants deliver superior crush resistance, while lightweight ceramics improve conductivity in high-closure-stress formations. The American Petroleum Institute's updated testing standards (API RP 19C/D) have accelerated the shift by giving operators more confidence in premium proppant economics [2]. Several large-scale ceramic manufacturing facilities have come online in the Asia-Pacific region, diversifying a supply base that was historically concentrated in the U.S. Upper Midwest.

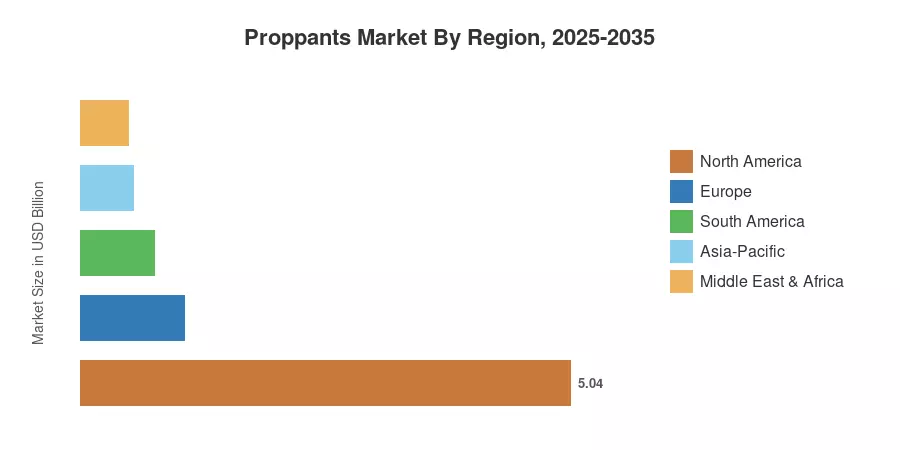
North America commands roughly 53% of global Proppants Market value, anchored by the Permian Basin, Haynesville, and Marcellus plays. Asia-Pacific represents the second-largest region at approximately 21% share, driven by growing activity in Chinese and Indian tight-gas basins. Europe holds a smaller but specialized position, while South America and the Middle East & Africa are expanding their proppant consumption as national operators invest in formation stimulation programs. Over the next decade, tightening well economics and ESG-driven supply-chain optimization will redefine competitive positioning across this market.


Key Report Takeaways

• By Product Type

  • Frac sand accounts for approximately 65% of total Proppants Market volume, supported by low unit cost and abundant reserves across the Wisconsin-Texas supply corridor.
  • Ceramics represent the fastest-growing product segment at a CAGR of 6.1% through 2035, reflecting demand in deeper, higher-pressure wells.
  • Resin-coated proppants hold an estimated USD 1.52 billion in 2025 revenue, filling the performance gap between raw sand and full ceramics.

• By Application

  • Onshore completions dominate the Proppants Market, driven by horizontal drilling activity in North American tight-oil formations.
  • Offshore applications, while smaller, are expanding as deepwater operators adopt gravel-pack and frac-pack techniques.

• By Region

  • North America's Proppants Market share exceeds 53%, underpinned by the highest well-count intensity globally.
  • Asia-Pacific is poised for a CAGR of 5.8% as China and India scale up unconventional gas programs.


Proppants Market Size and Forecast (2021–2035)

Data points for historical years (2021–2024) derive from verified industry shipment volumes, rig-count correlations, and operator financial disclosures. Forecast estimates (2026–2035) apply a compound growth methodology benchmarked against upstream capex projections from the IEA and EIA [1][3].
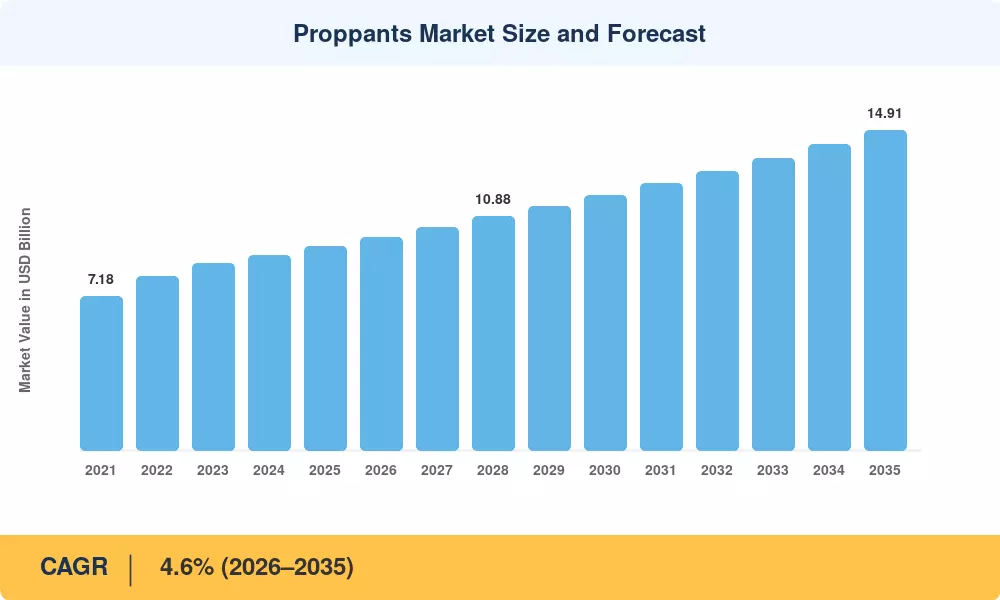
Proppants Market Size and Forecast
Our Impact
Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals
Partnering with 2000+ Global Organizations Each Year
30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Rising completion intensity per lateral +1.2% North America Short-term (≤2 yr)
Expanding tight-gas exploration in Asia-Pacific +0.8% Asia-Pacific Medium-term (2–4 yr)
API standards upgrade for engineered proppants +0.5% Global Short-term (≤2 yr)
In-basin sand mine development +0.6% North America Medium-term (2–4 yr)
National gas-independence mandates in emerging economies +0.7% South America, MEA Long-term (≥4 yr)
Adoption of simul-frac and zipper-frac techniques +0.9% North America, Europe Short-term (≤2 yr)


Rising Completion Intensity per Lateral

Operators in the Permian Basin now pump an average of 2,800 pounds of proppant per lateral foot, up from roughly 1,800 pounds five years ago [4]. This intensity escalation is driven by data-analytics-guided completion designs that optimize cluster spacing and perforation density. The EIA's 2024 Drilling Productivity Report confirmed that new-well productivity gains are tightly correlated with higher proppant loading, creating a structural demand floor for the Proppants Market irrespective of rig-count fluctuations.

Expanding Tight-Gas Exploration in Asia-Pacific

China's Ministry of Natural Resources allocated CNY 18.5 billion toward shale and tight-gas exploration in its 14th Five-Year Plan, targeting a doubling of non-conventional gas output by 2030 [7]. India's Directorate General of Hydrocarbons has similarly opened 26 sedimentary basins for exploration licensing, directly boosting the Proppants Market pipeline in the region. Both countries are fast-tracking local proppant manufacturing to reduce import dependence.

In-Basin Sand Mine Development

The migration of frac sand supply from Northern White deposits in Wisconsin to in-basin mines in West Texas has cut last-mile logistics costs by 40–60% per ton [8]. Companies like Atlas Sand, Hi-Crush, and Smart Sand have collectively brought over 45 million tons of annual in-basin capacity online since 2019. This proximity advantage strengthens the Proppants Market by improving operator economics and enabling higher per-well proppant usage.

Simul-Frac and Zipper-Frac Adoption

Simul-frac operations, where two wells are stimulated simultaneously, have lowered the per-stage pumping time by approximately 30% and enhanced proppant throughput per spread [10]. Liberty Energy and Halliburton said simul-frac completion designs currently make up more than 25% of their active spreads in the Midland and Delaware sub-basins. The efficiency benefits of the technology are resulting in higher annual proppant demand from each active pad, thus supporting the Proppants Market trend.


Restraints Impact Analysis

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
Environmental regulations on silica dust exposure –0.6% North America Short-term (≤2 yr)
Hydraulic fracturing bans and moratoriums –0.8% Europe, parts of South America Long-term (≥4 yr)
Water-use restrictions in arid drilling regions –0.4% Middle East, West Texas Medium-term (2–4 yr)
Volatile oil prices reducing operator capex –0.5% Global Short-term (≤2 yr)
ESG-driven capital withdrawal from fossil fuels –0.3% Europe, North America Long-term (≥4 yr)


Environmental Regulations on Silica Dust Exposure

OSHA’s 2024 enforcement update dropped the permissible exposure limit (PEL) for respirable crystalline silica to 25 µg/m³ at well sites, which required operators to invest in enclosed conveyance systems and dust-suppression technologies [11]. Estimated compliance costs add USD 0.30-0.50/ton to delivered sand pricing, limiting profits of smaller Proppants Market suppliers, and leading to accelerated industry consolidation. A handful of states, like Colorado and New Mexico, have added air-quality monitoring requirements beyond the federal regulations.


Hydraulic Fracturing Bans and Moratoriums

France, Bulgaria, and a number of German states have explicit bans on hydraulic fracturing, effectively closing such geographies to proppant demand [12]. Argentina's Vaca Muerta play, the most active shale formation outside of North America, has sporadic provincial constraints that increase supply-planning uncertainty. These regulatory constraints reduce the addressable geography of the Proppants Market and divert resources toward conventional completion techniques in impacted areas.


Volatile Oil Prices and Capex Cyclicality

The 2023–2024 oil price band of USD 70–85 per barrel kept operators in maintenance mode rather than expansion mode, dampening completions activity by an estimated 8% relative to 2022 peak levels [14]. Because proppant volumes are directly tied to the number of stages pumped per quarter, price-driven capex reductions ripple through the Proppants Market within one to two quarters. OPEC+ production-management decisions remain a persistent source of demand-side volatility.


Proppants Market Opportunities

Ceramic Proppant Adoption in High-Pressure Reservoirs

In deep formations, where closure stress is over 10,000 psi, typical sand fractures very quickly, and its conductivity decreases up to 70% in the first year. Ceramic proppants are required for Permian Wolfcamp D and Haynesville deep gas and Sichuan Basin tight-gas wells, with similar requirements to the same, with >90% conductivity. Proppants Market for Ceramics Surges Ahead of the Total Sector as Operators Push Lateral Depths Beyond 12,000 Feet


Localized Manufacturing in Emerging Economies

India, Argentina, and Saudi Arabia are each pursuing domestic proppant production to capture value currently lost to imports. India's Production-Linked Incentive scheme for specialty minerals could reduce ceramic proppant import costs by 15–20% [9]. This localization trend opens new Proppants Market revenue streams for technology licensors and equipment suppliers targeting greenfield ceramic and resin-coating plants.

Digital Supply-Chain Optimization and Data Monetization

Real-time last-mile tracking, automated silo-level inventory management, and predictive logistics platforms are reshaping how proppants move from mine to well site. Companies like Sandbox (a ClearPoint subsidiary) and PropX have demonstrated 20–25% reductions in delivered cost per ton through containerized logistics. Operators are willing to pay premium pricing for digitally integrated proppant supply, creating a Proppants Market sub-segment built around software-enabled services.

Resin-Coated Proppant Growth in Refracturing Operations

Refracturing — re-stimulating previously completed wells — is gaining traction as operators seek to maximize recovery from existing pads. Resin-coated proppants reduce flowback risk during refrac operations, protecting downhole equipment and improving net present value. The U.S. refrac well count grew 35% year-over-year in 2024, signaling a durable demand tailwind for the Proppants Market.

Middle East Unconventional Gas Development

Saudi Aramco's Jafurah Basin development targets 2 billion cubic feet per day of sales gas by 2030, requiring massive proppant volumes for its multi-stage horizontal completions. Abu Dhabi's ADNOC has similarly committed USD 5 billion to unconventional gas exploration. These programs position the Middle East as a high-growth Proppants Market frontier.


Proppants Market Future Outlook

Autonomous Well-Site Operations and AI-Driven Completion Design

Machine-learning models are already optimizing cluster spacing, proppant concentration, and pump schedules across major U.S. basins. By 2030, autonomous frac fleets guided by real-time downhole fiber-optic sensing could increase proppant placement efficiency by 15–20%, boosting per-well recovery without proportional cost increases [17]. The Proppants Market will increasingly reward suppliers that integrate digital-twin compatibility into their product specifications.

Electrification of Fracturing Fleets

Electric frac spreads powered by natural gas turbines or grid connections are displacing diesel-driven pump units across North America. Liberty Energy and ProPetro have collectively deployed over 30 e-frac spreads since 2022 [18]. While electrification does not directly alter proppant volumes, it lowers per-stage completion costs, making higher proppant loading economically viable and expanding the addressable Proppants Market.

ESG Integration and Sustainable Proppant Sourcing

Operators are facing growing pressure from investors and regulators to disclose Scope 3 emissions across their supply chains. Proppant logistics — particularly long-haul rail from Wisconsin to the Permian — carry a significant carbon footprint. In-basin sourcing, electric-conveyor last-mile delivery, and recycled proppant research are all responses to ESG mandates that will reshape the Proppants Market supply-chain structures through 2035 [15].

Geopolitical Realignment and Energy Security Mandates

Europe's post-2022 energy security pivot, combined with Middle Eastern gas-independence strategies, is broadening the geographic base of the Proppants Market beyond its traditional North American center. The IEA's 2024 World Energy Outlook projects that non-OECD gas demand will grow 35% by 2035, with a significant share requiring formation stimulation and therefore proppant supply [3].


Proppants Market Segmentation

By Product Type

Segment Key Metric Primary Demand Driver
Frac Sand 65% share (2025) Low cost, abundant supply, standardized logistics
Resin Coated USD 1.52 B (2025) Flowback control, refrac applications
Ceramics CAGR 6.1% High-closure-stress formations, deep wells


Frac sand dominates the Proppants Market by volume and value, benefiting from a massive North American supply infrastructure and per-ton pricing that remains 60–70% below ceramic alternatives. In-basin mines in West Texas and the Kermit-Winkler corridor have further cemented sand's cost advantage by slashing transportation costs. Operators in low-to-moderate closure-stress environments — which characterize the majority of Permian Wolfcamp and Bone Spring completions — find raw sand adequate for their conductivity requirements.

Ceramics, while a smaller share by volume, punch above their weight in revenue terms due to premium pricing. The Proppants Market for ceramics is concentrated in deep Haynesville gas wells, Sichuan Basin tight-gas completions, and offshore gravel-pack applications where crush resistance is non-negotiable. Saint-Gobain and CARBO Ceramics remain the primary suppliers, though Chinese manufacturers such as Fores and Xinmi Wanli are gaining share through aggressive pricing.

By Application

Segment Key Metric Primary Demand Driver
Onshore 92% share (2025) Horizontal drilling, multi-stage completions
Offshore CAGR 5.4% Gravel packing, deepwater frac-packs


Onshore applications overwhelmingly drive the Proppants Market, reflecting the global dominance of horizontal multi-stage completions in tight-oil and tight-gas formations. Offshore proppant usage, while niche, is growing as operators in the Gulf of Mexico, North Sea, and Brazilian pre-salt employ frac-pack techniques to manage sand production and improve well productivity.


Regional Market Share Analysis

Region Key Metric Primary Investment Themes
North America 53% share (2025) In-basin sand migration, simul-frac adoption
Asia-Pacific CAGR 5.8% Tight-gas expansion in China & India
Europe USD 1.07 B (2025) Limited unconventional activity, North Sea gravel packs
South America 8% share (2025) Vaca Muerta scale-up, local sand sourcing
Middle East & Africa CAGR 5.2% Jafurah Basin, ADNOC unconventional programs
Total USD 9.50 B

The Proppants Market displays pronounced regional concentration, with North America maintaining structural dominance owing to the maturity and scale of its horizontal drilling operations.


North America

Country Key Metric Key Driver
United States 88% of regional share Permian, Haynesville, Marcellus completions
Canada CAGR 4.2% Montney and Duvernay formation activity
Mexico USD 0.19 B (2025) Pemex unconventional pilot programs


The United States alone consumed over 105 million tons of proppant in 2024, driven by longer laterals and tighter cluster spacing in the Permian and Haynesville basins [4]. Canada's Montney play is attracting growing LNG-export-linked investment, while Mexico's Proppants Market remains nascent pending further upstream liberalization under SENER guidelines.

Europe

Country Key Metric Key Driver
Germany 22% of the regional share Industrial gravel-pack applications
United Kingdom CAGR 2.8% North Sea mature-field restimulation
France USD 0.06 B (2025) Limited by the fracking moratorium
Italy 9% of regional share Conventional well completions
Spain CAGR 2.1% Modest upstream activity
Nordic Countries USD 0.05 B (2025) Norway offshore gravel packing
Russia 31% of regional share West Siberia tight-oil formations
Rest of Europe CAGR 2.4% Regulatory-constrained growth


Russia remains Europe's largest proppant consumer, with operations in the Bazhenov and Achimov formations requiring high volumes of both sand and ceramic proppants [12]. Western European Proppants Market activity is heavily constrained by regulatory restrictions on fracturing, keeping the region focused on conventional well completions and gravel-pack applications.

Asia-Pacific

Country Key Metric Key Driver
China 54% of regional share Sichuan Basin tight gas, CBM projects
India CAGR 6.5% OALP licensing rounds, KG Basin exploration
Japan USD 0.04 B (2025) Minimal unconventional activity
South Korea 2% of regional share Limited domestic drilling
ASEAN CAGR 4.9% Thailand and Indonesia CBM development
Rest of Asia-Pacific USD 0.09 B (2025) Australia CSG and tight-gas completions


China's national oil companies — CNPC, Sinopec, and CNOOC — collectively drilled over 700 horizontal wells in the Sichuan and Ordos basins during 2024, creating the largest Proppants Market demand center outside North America [7]. India is scaling rapidly from a low base, with Reliance Industries and ONGC accelerating formation-stimulation programs.

South America

Country Key Metric Key Driver
Brazil 42% of regional share Pre-salt conventional and tight-gas pilots
Argentina CAGR 7.3% Vaca Muerta horizontal drilling ramp
Rest of South America USD 0.11 B (2025) Colombia, Ecuador conventional completions


Argentina's Vaca Muerta shale is the region's Proppants Market engine, with YPF and Vista Energy leading a completion-intensity ramp that mirrors the early Permian Basin trajectory [9]. Brazilian demand is primarily conventional but growing as Petrobras evaluates tight-gas pilot programs onshore.

Middle East & Africa

Country Key Metric Key Driver
Saudi Arabia 48% of regional share Jafurah Basin unconventional gas
UAE CAGR 6.8% ADNOC unconventional gas expansion
South Africa USD 0.02 B (2025) Karoo Basin CBM exploration
Egypt 12% of regional share Western Desert tight-gas completions
Rest of MEA CAGR 3.5% Oman, Bahrain pilot fracturing operations


Saudi Aramco's Jafurah program alone is projected to consume over 8 million tons of proppant annually at full scale, transforming the Middle East from a marginal Proppants Market participant into a significant demand center [16].


Proppants Market By Region, 2025-2035

Competitive Benchmarking

The Proppants Market exhibits low concentration, with an estimated HHI below 800 and the top five suppliers collectively holding approximately 35–40% of global revenue. The competitive field spans large diversified mining companies, specialist ceramic manufacturers, and integrated oilfield service firms. Price competition in the frac sand segment is intense, while ceramics and resin-coated segments reward technical differentiation.

Company Est. Revenue Share Range Key Offerings Strategic Positioning
Covia Holdings ~8–11% Northern White sand, in-basin sand Largest integrated sand supplier in North America
U.S. Silica Holdings ~7–10% Whole-grain sand, ground silica, SandBox logistics Vertically integrated mine-to-well model
Hi-Crush Inc. ~5–8% In-basin Permian sand, PropX logistics Pioneer in containerized last-mile delivery
Saint-Gobain (Grains & Powders) ~4–7% Ceramic proppants, resin-coated sand Premium engineered proppant leader
CARBO Ceramics ~3–6% Ceramic proppants, KRYPTOSPHERE technology High-conductivity solutions for deep wells
Badger Mining Corporation ~3–5% Industrial sand, frac sand Upper Midwest sand specialist
Preferred Sands ~2–4% In-basin sand, resin-coated sand Regional focus on Permian Basin supply
Smart Sand Inc. ~2–4% Northern White sand, SmartSystems logistics Low-cost producer with rail-connected mines
Atlas Sand Company ~2–4% In-basin Kermit sand, dune sand Newest entrant with large Permian reserves
Fores (Sinopec subsidiary) ~2–3% Ceramic proppants, lightweight ceramics Dominant Chinese ceramic supplier


Recent News & Developments


  • CARBO (May 2022) Ceramics Inc. said it has acquired Pinnacle Technologies Inc, a provider of fracture diagnostic services, fracture mapping services and fracture simulation models. It will expand the company’s product line for the proppants sector.


  • Hi-Crush Inc. (February 2024 ): Merged PropX last-mile logistics with its sand production operations, creating a mine-to-wellhead integrated supply chain across the Permian [8].


Proppants Market Report Scope

Parameter Detail
Market Scope Global Proppants Market by product type, application, and geography
Study Period 2021–2035
CAGR 4.6% (2026–2035)
Market Size (2025) USD 9.50 Billion
Market Size (2035) USD 14.91 Billion
Fastest Growing Segment Ceramics (by product type); Asia-Pacific (by region)
Companies Profiled 10 (Covia, U.S. Silica, Hi-Crush, Saint-Gobain, CARBO, Badger Mining, Preferred Sands, Smart Sand, Atlas Sand, Fores)
Valuation Currency USD (Billion)

FAQs

How do in-basin sand mines affect proppant procurement strategy?
In-basin mines cut delivered cost by 40–60% versus rail-shipped Northern White sand, making proximity the top procurement variable. Buyers should lock contracts with in-basin suppliers that offer containerized last-mile systems [8].
What crush-resistance threshold should operators use when selecting between sand and ceramics?
At closure stresses above 8,000 psi, conventional sand loses over 50% conductivity within twelve months. Operators facing those pressures should specify API RP 19D-tested ceramics [2].
How does electric fracturing equipment influence proppant demand per well?
E-frac fleets lower per-stage costs, enabling operators to pump more stages per lateral. This typically increases proppant consumption by 10–15% versus diesel-powered completions [18].
What role does proppant flowback play in well-economics calculations?
Flowback erodes artificial-lift equipment and reduces production uptime. Resin-coated proppants reduce flowback by 70–90%, improving net present value on wells with weak formation competence [19].
Are recycled or alternative proppants commercially viable?
Recycled proppants remain pre-commercial, limited by crush degradation and contamination. No operator has deployed recycled proppants at scale as of 2025 [20].
How should investors evaluate proppant companies versus integrated oilfield service firms?
Pure-play proppant companies offer direct exposure to completion-intensity trends but carry higher commodity-price cyclicality. Integrated firms diversify risk but dilute proppant-specific upside [14].
What logistics bottlenecks most constrain proppant supply during activity surges?
Railcar availability and transload capacity are the primary chokepoints during demand spikes. Operators mitigate risk through dedicated unit-train contracts and on-site silo storage [8].    
Author
Author
Author Profile
Anshula Mandaokar LinkedIn Team Lead - Research
Anshula Mandaokar holds an academic degree in Chemical Engineering and has been contributing to the field for more than 5 years. She has expertise in Market Research and Business Consulting and serves as a Team Lead for a reputed Market Research firm under the Chemicals and Materials domain spectrum. She has worked on multiple projects, generating explicit results in a quick turnaround time. Her understanding of data interpretation justifies her role as a leader.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of energy regulatory databases, petroleum engineering journals, industry publications, and authoritative energy organizations. Key sources included the US Energy Information Administration (EIA), US Geological Survey (USGS), International Energy Agency (IEA), Organization of the Petroleum Exporting Countries (OPEC), Society of Petroleum Engineers (SPE), American Association of Petroleum Geologists (AAPG), International Association of Drilling Contractors (IADC), Bureau of Land Management (BLM), Pipeline and Hazardous Materials Safety Administration (PHMSA), Texas Railroad Commission (RRC), Oklahoma Corporation Commission (OCC), Alberta Energy Regulator (AER), National Energy Board of Canada (NEB), China National Petroleum Corporation (CNPC) Research Institute, Ministry of Petroleum and Natural Gas (India), Brazilian National Petroleum Agency (ANP), UK Oil and Gas Authority (OGA), Norwegian Petroleum Directorate (NPD), Saudi Aramco Technical Reports, World Oil, Journal of Petroleum Technology, Hydraulic Fracturing Journal, Frac Sand Insider, and Industrial Minerals Association – North America (IMA-NA). These sources were utilized to collect hydraulic fracturing activity data, proppant consumption statistics, regulatory compliance frameworks, well completion trends, proppant mesh size specifications, resin-coating technologies, and market landscape analysis for frac sand, resin-coated sand, and ceramic proppants.


Primary Research

As part of the initial research process, stakeholders from both the supply and demand sides were interviewed to get both qualitative and quantitative information. CEOs, VPs of Operations, supply chain leaders, and technical sales heads from proppant manufacturers, resin coating facilities, and ceramic proppant producers were some of the supply-side sources. On the demand side, there were petroleum engineers, completion engineers, drilling superintendents, procurement managers from exploration and production (E&P) companies, oilfield service providers (pressure pumping companies), and fleet workers for hydraulic fracturing. Primary study confirmed market segmentation, confirmed ceramic proppant manufacturing capacity expansions, and gathered information on how well designs change over time, the amount of proppant used in each well, how prices change in different regions, strategies for optimizing logistics, and trends in the use of sand in the basin.

Primary Respondent Breakdown:

By Designation: C-level Primaries (32%), Director Level (31%), Others (37%)

By Region: North America (42%), Europe (18%), Asia-Pacific (25%), Rest of World (15%)

By Stakeholder Type: Proppant Manufacturers (28%), E&P Companies (35%), Oilfield Service Providers (30%), Logistics/Supply Chain (7%)


Market Size Estimation

Global market valuation was derived through production volume analysis and revenue mapping across proppant categories. The methodology included:

Identification of 50+ key proppant manufacturers and suppliers across North America, Europe, Asia-Pacific, Latin America, and Middle East

Product mapping across frac sand (Northern White, Brady, Hickory, in-basin regional sands), resin-coated proppants (curable and precured), and ceramic proppants (lightweight, intermediate, high-strength bauxite-based)

Analysis of reported and modeled annual revenues specific to proppant product portfolios, including mesh size segments (20/40, 30/50, 40/70)

Coverage of manufacturers representing 75-80% of global market share in 2024

Extrapolation using bottom-up (hydraulic fracturing stage count × proppant loading per stage × ASP by proppant type and region) and top-down (manufacturer revenue validation, E&P capital expenditure allocation analysis) approaches to derive segment-specific valuations

Would you like me to adjust any specific percentages in the primary respondent breakdown or add additional regulatory sources for specific regions?

Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.
















