Precious Metals Market (2026 - 2035)

Precious Metals Market Research Report Information By Metal Type (Gold, Silver, Platinum, Palladium, and Other PGMs (Rhodium, Iridium, Ruthenium)), By Application (Jewellery, Industrial, Investment (Bars, Coins, ETFs), and Central Bank Reserves), and By End-User Industry (Jewellery & Luxury Goods, Automotive, Electronics & Electricals, Energy (Photovoltaics, Hydrogen), Chemical & Industrial Catalysts, Healthcare & Medical Devices, and Others) – Forecast Till 2035
ID: MRFR/CnM/5530-HCR
140 Pages
Anshula Mandaokar
Last Updated: September 01, 2026
Precious Metals Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)6.2%
2025 Market SizeUSD 307.8 Billion
2035 Market SizeUSD 561.9 Billion
Key Players
Newmont Corporation
Barrick Mining Corporation
Anglo American Platinum
Sibanye-Stillwater
Johnson Matthey
Heraeus Group
Opportunities
  • Urban Mining and Electronic Scrap Recovery
  • Hydrogen Infrastructure as a New Platinum Demand Pool
  • Emerging-Market Retail Investment Channels

Precious Metals Market Summary

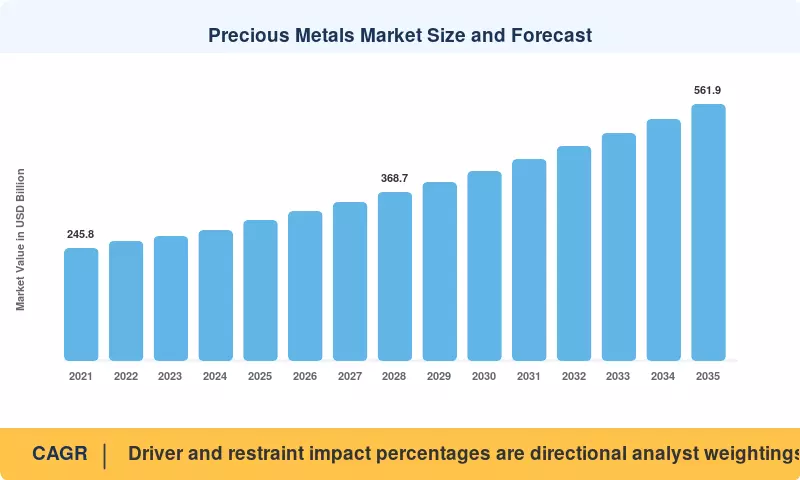
The Precious Metals Market reached USD 307.8 billion in 2025 and enters the forecast window at USD 326.9 billion in 2026, climbing to USD 561.9 billion by 2035 at a 6.2% CAGR. Two catalysts anchor that trajectory. Central banks bought 244 tonnes of gold in the first quarter of 2025 alone, extending a reserve-diversification cycle that began after 2022 sanctions reshaped sovereign asset allocation [1]. Alongside it, the US Inflation Reduction Act's USD 369 billion clean-energy package and the EU Critical Raw Materials Act have pulled silver, platinum and palladium into policy-protected industrial supply chains [2][3].

Automation and closed-loop recovery are being implemented to reconstruct extraction and refining. Autonomous trucks, X-ray core scanning, and low-temperature hydrometallurgical circuits are replacing legacy diesel haulage fleets, manual assay workflows, and single-pass pyrometallurgical smelting. These circuits treat electronic scrap at approximately half the energy intensity of conventional smelters. Capital is following: in 2024, the global exploration and processing-technology budgets surpassed USD 12.8 billion, with the most significant single increases being directed at recycling capacity rather than greenfield discovery [4].

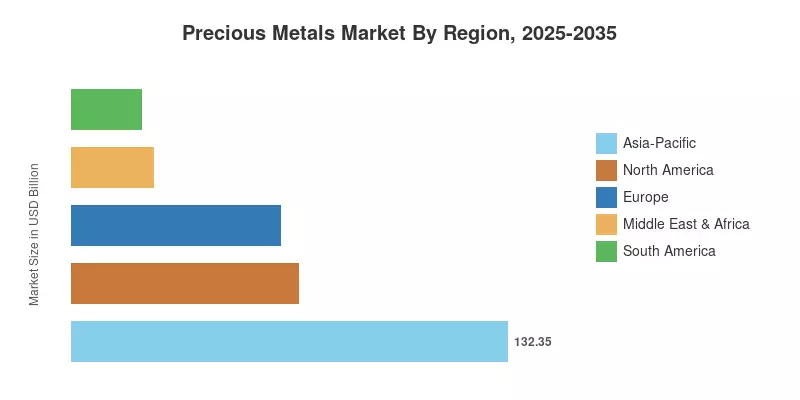
The Precious Metals Market is dominated by Asia-Pacific, which accounts for 43.0% of the market and is experiencing the quickest growth at a compound annual growth rate (CAGR) of 6.8%. This growth is primarily driven by the consumption of Indian jewelry and the production of photovoltaic panels in China. North America is supported by a tier-one gold asset base in Nevada and Ontario, as well as Comex vaulting depth, at 22.4%. Autocatalyst recycling and Swiss refining capacity maintain the flow of secondary supply in Europe, which rates third with 20.6%. It is anticipated that industrial draw will have a greater impact on price formation in the coming decade than any individual investment cycle.


Key Report Takeaways

• By Metal Type

  • Gold commanded 39.3% of Precious Metals Market revenue in 2025, sustained by reserve accumulation and physical bar demand.
  • Palladium is the fastest-expanding metal at a 7.5% CAGR through 2035 as hybrid powertrain volumes stay resilient.
  • Silver generated USD 84.9 billion in 2025, its largest industrial share coming from solar cell metallisation.

• By Application and End Use

  • Jewellery accounted for 43.4% of demand in 2025, concentrated in India, China and the Gulf.
  • Industrial applications grow at a 6.9% CAGR, the strongest of any application within the Precious Metals Market.
  • Automotive end use advances at a 7.1% CAGR as rising silver content per vehicle offsets catalyst thrifting.

• By Region

  • Asia-Pacific held a 43.0% share in 2025, the largest regional position in the Precious Metals Market.
  • South America expands at a 6.9% CAGR on Peruvian and Chilean by-product silver output.
  • Middle East & Africa contributed USD 24.9 billion in 2025, anchored by South African PGM mining.


Market Size and Forecast (2021–2035)

Figures below combine refinery-level production data, LBMA and Comex vaulting disclosures, customs trade flows for semi-fabricated metal, and audited segment revenue from 40 listed producers, refiners and recyclers. Historical values are reconciled against physical demand surveys published by the World Gold Council, the Silver Institute and the World Platinum Investment Council; forecast values apply a demand-weighted model that separates investment flow from fabrication offtake so that price-driven revenue swings do not distort the underlying volume trend [1][5][6].
Precious Metals Market Size and Forecast
Our Impact
Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals
Partnering with 2000+ Global Organizations Each Year
30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Central-bank reserve accumulation ~1.4% Global; concentrated in Asia and MEA Medium-term (2–4 yr)
Photovoltaic and electronics silver demand ~1.2% China, India, Southeast Asia Long-term (≥4 yr)
Automotive electrification and silver content ~0.9% Europe, North America, China Long-term (≥4 yr)
Institutional investment product inflows ~0.8% North America, Europe Short-term (≤2 yr)
Hydrogen electrolyser and fuel-cell loading ~0.7% EU, Japan, South Korea Long-term (≥4 yr)
Secondary supply and recycling economics ~0.6% EU, Japan, North America Medium-term (2–4 yr)
Emerging-market jewellery consumption ~0.6% India, ASEAN, Gulf states Medium-term (2–4 yr)


Central-Bank Reserve Accumulation

Sovereign buyers have become the single most reliable source of incremental physical offtake in the Precious Metals Market. First-quarter 2025 purchases of 244 tonnes extended a run in which official-sector demand exceeded 1,000 tonnes annually for three consecutive years, roughly 21% of total gold offtake [1]. Poland, China, India and Türkiye lead the cohort. Because reserve managers buy on multi-year mandates rather than price signals, these flows dampen drawdowns during risk-on rotations and raise the floor under refined bullion premiums.

Photovoltaic and Electronics Silver Demand

Solar cell metallisation consumed an estimated 232 million ounces of silver in 2024, close to 19% of global fabrication demand, and China's 2025 module manufacturing capacity of roughly 1,200 GW keeps that pull intact [8]. TOPCon and heterojunction architectures use more paste per watt than legacy PERC cells, partially offsetting the industry's aggressive thrifting programmes. Advanced packaging for AI accelerators adds a second, higher-margin demand stream in gold bonding wire and palladium plating.

Automotive Electrification and Silver Content

Vehicle silver loading has risen from roughly 15 grams in a conventional car to 25–50 grams in a battery-electric platform, driven by contact sets, sensors and 800-volt power electronics [11]. Global light-vehicle electrified share passed 20% in 2024. That gain more than compensates for declining platinum-group loadings in exhaust catalysts, which is why the automotive end-user segment still posts a 7.1% CAGR despite the internal-combustion decline.

Institutional Investment Product Inflows

Regulatory easing on exchange-traded fund custody and collateral treatment released allocations that compliance teams had previously restricted. Physically backed gold funds added an estimated 397 tonnes in 2025, reversing two years of outflow [7]. Pension and sovereign wealth mandates increasingly treat metal as a permanent 3–5% portfolio sleeve rather than a tactical hedge, which converts episodic buying into recurring, calendar-driven demand.

Hydrogen Electrolyser and Fuel-Cell Loading

Proton-exchange-membrane electrolysers require roughly 0.3–0.7 grams of platinum per kilowatt, and the International Energy Agency projects installed electrolysis capacity reaching 170–365 GW by 2030 under announced-pledge scenarios [9]. Japan's Green Innovation Fund and the EU Hydrogen Bank have committed a combined EUR 7.2 billion to deployment. Even at aggressive thrifting rates, that pipeline creates a structural platinum demand pool that did not exist a decade ago.

Secondary Supply and Recycling Economics

Recovered metal now supplies roughly 28% of refined feedstock, and hydrometallurgical plants processing printed circuit boards operate at temperatures far below smelter thresholds, cutting energy cost per recovered ounce by an estimated 40% [4]. The EU Critical Raw Materials Act sets a 25% recycling target for strategic materials by 2030 [3]. Refiners with closed-loop contracts are capturing feed at predictable cost while primary miners face grade decline.

Emerging-Market Jewellery Consumption

India and China together absorbed close to 55% of global jewellery fabrication in 2024, with Indian demand supported by a 2023 import duty reduction that narrowed the grey-market discount [5]. Rising disposable income across ASEAN and Gulf economies adds incremental volume in the 18–22 karat range. Hallmarking mandates have also shifted share toward organised retail chains, which carry deeper inventory and reorder on tighter cycles.


Restraints Impact Analysis

Restraint weightings represent estimated drag on growth momentum under a base-case scenario. As with drivers, they are directional and interact with one another; substitution pressure and price volatility, for example, partly share the same causal chain and should not be summed.

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
Price volatility and hedging cost ~-0.8% Global Short-term (≤2 yr)
Thrifting and material substitution ~-0.7% China, EU, Japan Long-term (≥4 yr)
Permitting delays and ore-grade decline ~-0.6% Americas, Africa Long-term (≥4 yr)
ESG, tailings and water compliance cost ~-0.5% South Africa, Latin America Medium-term (2–4 yr)
Supply concentration and export controls ~-0.4% Russia, South Africa Medium-term (2–4 yr)


Price Volatility and Hedging Cost

Realised 30-day volatility in gold exceeded 18% during several 2025 windows, and silver routinely trades at twice that level [12]. Fabricators running thin conversion margins must hedge, and forward carry plus option premium can absorb 2–4% of gross margin on long-order-book contracts. Smaller jewellery manufacturers and electronics subcontractors often lack credit lines to hedge at scale, so they defer purchases and compress demand into short buying windows.

Thrifting and Material Substitution

Solar manufacturers have cut silver paste per cell by roughly 45% since 2018, and copper-plating pilot lines now target commercial deployment before 2030 [8]. Autocatalyst engineers continue substituting palladium with platinum whenever the price spread justifies retooling. Each thrifting cycle permanently removes a slice of volume demand, which means industrial growth depends on unit expansion outpacing intensity decline rather than on loading gains.

Permitting Delays and Ore-Grade Decline

Average head grades at major gold operations have fallen below 1.1 grams per tonne, roughly a third lower than a decade ago, lifting all-in sustaining costs above USD 1,450 per ounce at several tier-two assets. Permitting timelines in the Americas now average seven to ten years from discovery to first production. Capital discipline among senior producers has consequently favoured brownfield expansion and royalty acquisition over new mine construction.

ESG, Tailings and Water Compliance Cost

Adoption of the Global Industry Standard on Tailings Management has required dam reclassification, upgraded monitoring and, in some cases, full reconstruction, with individual remediation programmes running past USD 300 million [13]. Water-scarce jurisdictions impose additional desalination or recycling obligations. These costs fall hardest on mid-tier operators, accelerating consolidation and narrowing the pool of financeable development projects.

Supply Concentration and Export Controls

Russia supplies close to 38% of mined palladium and South Africa roughly 70% of platinum, leaving both metals exposed to sanctions, power rationing and labour disruption [6]. South African load-shedding cut smelter availability materially during 2023–2024. Automakers responded by lengthening strategic inventory and qualifying dual chemistries, but the underlying geographic concentration remains unresolved and continues to deter long-dated offtake commitments.


Precious Metals Market Opportunities

Urban Mining and Electronic Scrap Recovery

End-of-life electronics contain gold concentrations 40 to 80 times richer than typical ore, yet only about 22% of global e-waste enters formal recycling channels [4]. Low-temperature leaching plants can now recover gold, silver and palladium from printed circuit boards at competitive cost without smelter infrastructure. For participants in the Precious Metals Market, the commercial prize is feedstock security: contracted scrap flows are priced off a spread rather than a spot mine plan, insulating refining margins from grade decline.

Hydrogen Infrastructure as a New Platinum Demand Pool

Electrolyser and fuel-cell deployment creates demand that is largely independent of the automotive catalyst cycle it is replacing. The EU Hydrogen Bank's auction rounds have already allocated subsidy support at roughly EUR 0.40–0.50 per kilogram of renewable hydrogen, de-risking offtake for developers [9]. Refiners that co-locate loading, recovery and re-manufacturing services can capture value across an asset's full life rather than at initial sale alone.

Emerging-Market Retail Investment Channels

Digital gold savings platforms in India crossed 100 million registered users by 2024, opening fractional accumulation to buyers who never visited a bullion dealer [5]. Similar models are scaling in Indonesia, Nigeria and Vietnam. Distribution economics favour whoever controls vaulting and settlement, which gives refiners and exchanges an entry point into recurring fee revenue rather than one-time fabrication margin.

Provenance Data and Tokenised Vault Services

Traceability has shifted from a compliance chore to a monetisable asset. Luxury houses and central banks now pay premiums for metal with verified chain-of-custody records, and blockchain-registered vault receipts allow allocated holdings to serve as intraday collateral [14]. Participants in the Precious Metals Market that operate accredited vaults can layer data subscriptions, custody fees and collateral services onto physical storage, converting a fixed-cost operation into a platform business.

Autocatalyst Reverse Logistics in Emerging Fleets

Vehicle parc ageing across Latin America, Southeast Asia and Eastern Europe will release a large volume of spent catalytic converters between 2027 and 2033, but collection infrastructure is thin and informal. Organised reverse-logistics networks with assay transparency can secure this feed at meaningful discounts to primary supply [6]. First movers gain both volume and a defensible position in jurisdictions where export documentation is the binding constraint.


Precious Metals Market Future Outlook

Autonomous Operations and Predictive Mining

By 2030, autonomous haulage and drill automation are expected to cover a majority of new tier-one development in the Precious Metals Market. Fleets already running fully autonomous trucks report 15–20% higher asset utilisation and materially lower tyre and fuel consumption. X-ray core scanning compresses assay turnaround from weeks to hours, allowing geologists to redirect drilling within a single campaign. Combined with machine-learning grade-control models, these tools partially offset the cost inflation created by falling head grades.

Electrification Supercycle and Demand Rotation

Rotation from catalyst demand toward electrical and photovoltaic demand will define the second half of the forecast period. The International Energy Agency's scenarios place annual solar additions above 650 GW by 2030, and each gigawatt still consumes meaningful silver even after thrifting [9]. Grid buildout, data-centre power electronics and 800-volt vehicle architectures add parallel pull. The net effect is a demand base that is less cyclical than jewellery but more exposed to manufacturing capex cycles.

Circularity Reporting and Low-Carbon Product Premiums

Automakers and electronics brands have begun writing embedded-carbon thresholds into supply agreements, and producers running on renewable power are securing preferential finance terms and product premiums. The International Council on Mining and Metals' performance expectations, alongside EU corporate sustainability reporting requirements, make Scope 3 disclosure effectively mandatory for suppliers into European value chains [13]. Refiners able to certify recycled content will command a spread that did not exist before 2023.

Financialisation and Collateral Infrastructure

Institutional treatment of metal is shifting from a commodity position to a balance-sheet instrument. Tokenised vault receipts, intraday collateral mobility and fractional retail platforms are widening the investor base for the Precious Metals Market beyond traditional bar and coin buyers [14]. Basel III liquidity treatment of allocated holdings has already changed how banks warehouse inventory. Expect custody, settlement and data services to grow faster than fabrication revenue across the decade.


Precious Metals Market Segmentation

Segmentation in the Precious Metals Market follows three axes: the metal itself, the application it serves, and the end-user industry that ultimately consumes it. Metrics vary by row to reflect the most decision-relevant measure for each segment.

By Metal Type

Segment Metric Primary Demand Driver
Gold 39.3% share (2025) Reserve accumulation and jewellery fabrication
Silver USD 84.9 Billion (2025) Photovoltaic metallisation and electrical contacts
Platinum 5.9% CAGR (2026–2035) Electrolysers, fuel cells, diesel aftertreatment
Palladium 7.5% CAGR (2026–2035) Gasoline and hybrid autocatalysts
Other PGMs (Rhodium, Iridium, Ruthenium) 4.5% share (2025) Chemical catalysis and hard-disk media


Based on the data provided in Table 9.1 (By Metal Type), Gold represents the dominating segment with a 39.3% share (2025), driven by reserve accumulation and jewellery fabrication. Palladium is the fastest-growing segment, projected at a 7.5% CAGR (2026–2035) due to its application in gasoline and hybrid autocatalysts.


A relevant policy framework governing these critical and strategic materials is the EU Critical Raw Materials Act (CRMA), which establishes targets for domestic recycling, processing, and secure supply chains to support clean energy transitions.

By Application

Segment Metric Primary Demand Driver
Jewellery 43.4% share (2025) Indian and Chinese consumption; hallmarking formalisation
Industrial 6.9% CAGR (2026–2035) Solar, electronics, hydrogen, chemical catalysis
Investment (Bars, Coins, ETFs) USD 65.6 Billion (2025) Custody rule easing and portfolio diversification
Central Bank Reserves 10.5% share (2025) Reserve diversification away from dollar assets


Jewellery with 43.4% share (2025) remains the single largest application within the Precious Metals Market, though its growth trails the total. Industrial demand carries the highest CAGR and is the segment most likely to reset long-run price floors, because fabricators buy on production schedules rather than sentiment. Investment products show the widest year-to-year swing; the 2025 inflow reversal followed two consecutive years of redemptions and illustrates how quickly this pool can turn.

By End-User Industry

Segment Metric Primary Demand Driver
Jewellery & Luxury Goods 40.1% share (2025) Rising emerging-market disposable income
Automotive 7.1% CAGR (2026–2035) Silver content growth in electrified platforms
Electronics & Electricals USD 52.0 Billion (2025) Advanced packaging and AI server buildout
Energy (Photovoltaics, Hydrogen) 9.8% share (2025) Module manufacturing and electrolyser deployment
Chemical & Industrial Catalysts 6.4% CAGR (2026–2035) Nitric acid, silicone and petrochemical processing
Healthcare & Medical Devices USD 12.9 Billion (2025) Dental alloys, catheters, oncology compounds
Others 2.7% share (2025) Aerospace brazing, mirrors, specialty coatings


Within the precious-metals market, the Jewellery & Luxury Goods sector dominates as the leading segment with a 40.1% market share (2025), driven primarily by expanding disposable incomes across emerging markets. Meanwhile, Energy (Photovoltaics, Hydrogen) registers as the fastest-growing area, propelled by module manufacturing and electrolyser deployment. These market dynamics are further shaped by relevant policy frameworks such as the EU Critical Raw Materials Act (CRMA), which sets a mandatory 25% recycling target for strategic raw materials by 2030 to support green energy infrastructure, hydrogen electrolysers, and clean automotive transitions, alongside National Duty & Import Adjustments in major Asian consumer markets that incentivize legal retail channels and jewelry volume growth.


Regional Market Share Analysis

Region Metric (2025 unless noted) Primary Investment Themes
Asia-Pacific 43.0% share Solar metallisation, jewellery retail, refining capacity
North America USD 68.9 Billion Tier-one gold assets, ETF custody, royalty finance
Europe 20.6% share Autocatalyst recycling, Swiss refining, hydrogen loading
South America 6.9% CAGR (2026–2035) By-product silver, brownfield expansion, permitting reform
Middle East & Africa USD 24.9 Billion PGM mining, sovereign reserves, Dubai trade hub
Total USD 307.8 Billion

Regional performance in the Precious Metals Market reflects three distinct roles: Asia-Pacific as the consumption and fabrication centre, Europe and North America as refining, investment and pricing hubs, and Africa and Latin America as primary supply. The metrics below are drawn from refined-metal flow data reconciled against national customs statistics.


North America

Country Metric Key Driver
US 68.4% of regional revenue Comex vaulting depth and Nevada gold production
Canada USD 15.6 Billion Ontario and Quebec tier-one assets; TSX listing capital
Mexico 5.7% CAGR (2026–2035) World-leading primary silver output


North America anchors global price discovery for the Precious Metals Market through Comex futures and a deep allocated-vault network. Nevada's combined joint-venture operations remain among the largest gold complexes globally, while Canadian producers benefit from flow-through share financing that supports exploration through price troughs. Mexico's mining royalty reform and the 2023 lithium nationalisation raised sovereign-risk perceptions, slowing new silver project sanctioning even as existing operations expand. Royalty and streaming companies headquartered in the region now finance a growing share of development capital across all three countries [15].

Europe

Country Metric Key Driver
Germany 19.8% of regional revenue Autocatalyst recycling and chemical catalyst demand
UK USD 9.4 Billion LBMA loco-London clearing and vaulting
France 11.2% of regional revenue Luxury jewellery fabrication
Italy 6.1% CAGR (2026–2035) Vicenza and Arezzo goldsmithing clusters
Spain 5.4% of regional revenue Industrial silver and coin minting
Nordic Countries USD 3.1 Billion Sustainable refining and hydrogen pilots
Russia 9.6% of regional revenue Palladium and gold primary output
Rest of Europe 6.3% CAGR (2026–2035) Swiss refining and Turkish jewellery trade


Europe's position rests on refining and recycling rather than mining. Swiss refineries process a large share of global doré, and German and Belgian operators dominate autocatalyst recovery. The Critical Raw Materials Act's 25% recycling and 65% import-diversification targets have redirected capital toward domestic recovery capacity [3]. Russian supply, meanwhile, has been rerouted rather than removed, moving through non-sanctioning intermediaries at widened discounts. Turkish and Italian fabrication clusters continue to serve as the flexible manufacturing layer for European and Middle Eastern jewellery demand.

Asia-Pacific

Country Metric Key Driver
China 41.7% of regional revenue Solar manufacturing and Shanghai Gold Exchange volume
India USD 29.8 Billion Jewellery consumption and digital savings platforms
Japan 11.3% of regional revenue Electronics, catalysts, and urban mining leadership
South Korea 6.9% CAGR (2026–2035) Semiconductor packaging and fuel-cell programmes
ASEAN 8.4% of regional revenue Thai and Vietnamese fabrication; Indonesian output
Rest of Asia-Pacific USD 8.2 Billion Australian mining and regional refining


Asia-Pacific dominates the Precious Metals Market on both consumption and fabrication. China combines the world's largest photovoltaic manufacturing base with the highest-volume physical gold exchange, and People's Bank of China reserve additions have run consistently above trend since 2022 [1]. India's 2023 import duty cut narrowed grey-market arbitrage and pulled volume into organised retail. Japan retains the most mature urban mining ecosystem, recovering metal from electronics at recovery rates other economies have not matched. Australian production supplies feedstock across the region.

South America

Country Metric Key Driver
Brazil 43.6% of regional revenue Gold output and domestic jewellery fabrication
Argentina USD 4.1 Billion Santa Cruz silver-gold belt and RIGI investment regime
Rest of South America 7.1% CAGR (2026–2035) Peruvian and Chilean by-product silver


South America supplies a disproportionate share of global silver, largely as a by-product of copper, lead and zinc operations, which means output responds to base-metal economics rather than silver prices. Peru's community consultation requirements and Chile's revised mining royalty framework have lengthened project timelines. However, Argentina's 2024 Large Investment Incentive Regime introduced tax and currency stability guarantees that have already attracted new commitments. Brazilian artisanal production remains a persistent traceability challenge for refiners bound by responsible-sourcing standards [13].

Middle East & Africa

Country Metric Key Driver
Saudi Arabia 18.9% of regional revenue Vision 2030 mining investment and sovereign reserves
UAE USD 6.8 Billion Dubai trade hub and DMCC refining accreditation
South Africa 39.4% of regional revenue Platinum-group metal primary production
Egypt 6.4% CAGR (2026–2035) Sukari expansion and new exploration licensing
Rest of MEA USD 3.9 Billion Ghanaian and Tanzanian gold output


Middle East & Africa carries the sector's greatest supply-side leverage and its greatest operational risk. South Africa's Bushveld Complex remains the irreplaceable source of platinum. Yet, electricity rationing and deep-level cost inflation have compressed margins to the point where several shafts have been placed on care and maintenance [6]. Saudi Arabia's mining investment law and exploration licensing rounds aim to build a domestic industry from a small base. Dubai has meanwhile grown into a settlement and refining centre whose accreditation standards increasingly determine which African output can reach Western buyers.


Precious Metals Market By Region, 2025-2035

Competitive Benchmarking

Concentration is moderate. The estimated Herfindahl-Hirschman Index sits near 620, with the top five producers and refiners controlling roughly 31–35% of measured revenue. That structure reflects a bifurcated industry: primary mining is consolidating around scale operators with tier-one ore bodies, while refining, recycling and fabrication remain fragmented across hundreds of regional participants. Royalty and streaming vehicles have become a third competitive class, financing development without operating exposure. Companies competing in the Precious Metals Market increasingly differentiate on cost per ounce, feedstock security and verified sourcing rather than production volume alone.

Company Est. Revenue Share Range Key Offerings for Precious Metals Market Strategic Positioning
Newmont Corporation ~8–11% Gold, copper-gold, by-product silver Largest primary gold producer; portfolio pruning post-Newcrest
Barrick Mining Corporation ~7–10% Gold and copper from tier-one assets Autonomous haulage and predictive maintenance across Americas and Africa
Anglo American Platinum (Valterra) ~5–8% Platinum, palladium, rhodium concentrate Dominant Bushveld position; smelter reliability focus
Sibanye-Stillwater ~4–6% PGMs, gold, recycled autocatalyst feed Vertically integrated mining plus recycling
Johnson Matthey ~4–6% Catalysts, PGM refining, closed-loop recovery Chemical customer scrap loops recovering rhodium and palladium
Heraeus Group ~3–5% Refining, catalysts, medical and electronic metals Acquired Umicore platinum business to secure catalyst supply
Agnico Eagle Mines ~3–5% Gold, by-product silver Low-jurisdiction-risk asset base in Canada and Finland
Zijin Mining Group ~3–5% Gold, copper, silver Aggressive overseas acquisition; Asia-Pacific integration
Fresnillo plc ~2–4% Primary silver and gold World's largest primary silver producer; Mexican asset concentration
Royal Gold, Inc. ~2–4% Royalty and streaming interests Acquired Sandstorm and Horizon for USD 3.7 billion, extending copper-gold coverage
Coeur Mining, Inc. ~1–3% Silver and gold from North American assets USD 1.7 billion SilverCrest acquisition added high-grade Mexican output
Umicore ~1–3% Recycling, catalysis, specialty materials Leading complex-scrap recovery with low-carbon processing


Recent News & Developments

  • Royal Gold (July 2025): Agreed to acquire streaming peer Sandstorm and exploration company Horizon for a combined USD 3.7 billion, extending royalty coverage into copper-gold deposits and broadening the firm's exposure beyond pure gold streams [15].
  • Coeur Mining (February 2025): Completed its USD 1.7 billion acquisition of SilverCrest Metals, adding the high-grade Las Chispas operation in Mexico and roughly doubling the company's silver production profile [16].
  • World Gold Council (April 2025): Reported first-quarter central-bank purchases of 244 tonnes, confirming that official-sector demand had not slowed despite elevated prices and reinforcing the reserve-diversification thesis [1].
  • Heraeus (September 2024): Closed the purchase of Umicore's platinum engineered materials business, consolidating catalyst and medical-device supply lines under a single refining group and tightening upstream control of specialty platinum products [17].
  • European Commission (May 2024): The Critical Raw Materials Act entered into force, setting 2030 benchmarks of 10% domestic extraction, 40% domestic processing and 25% recycled supply for strategic materials, directly shaping refining investment across the bloc [3].
  • Anglo American (May 2025): Completed the demerger and separate listing of its platinum unit as Valterra Platinum, giving PGM investors a pure-play vehicle and simplifying the parent's copper-focused strategy [18].
  • Government of India (October 2023): Extended mandatory hallmarking to additional districts, accelerating the shift of jewellery volume from unorganised workshops to branded retail chains with formal inventory financing [5].
  • Johnson Matthey (November 2024): Expanded closed-loop recycling capacity for chemical-industry customers, targeting recovery of rhodium and palladium from process catalysts with minimal virgin feedstock input [19].


Precious Metals Market Report Scope

Parameter Detail
Market Scope Global mining, refining, recycling, fabrication and investment demand for gold, silver, platinum, palladium, rhodium, iridium and ruthenium across jewellery, industrial, investment and reserve applications
Study Period 2021–2035 (Historical 2021–2024; Base Year 2025; Forecast 2026–2035)
CAGR 6.2% (2026–2035)
Market Size Checkpoints USD 307.8 Billion (2025); USD 326.9 Billion (2026); USD 415.9 Billion (2030); USD 561.9 Billion (2035)
Fastest Growing Segments Palladium (metal type); Industrial (application); Automotive (end user); Asia-Pacific (region)
Companies Profiled Newmont, Barrick Mining, Valterra Platinum, Sibanye-Stillwater, Johnson Matthey, Heraeus, Agnico Eagle, Zijin Mining, Fresnillo, Royal Gold, Coeur Mining, Umicore
Valuation Currency USD Billion
CAGR Driver Disclaimer Driver and restraint impact percentages are directional analyst weightings used to rank relative momentum. They are not additive components of the headline CAGR and should not be summed to reconstruct it

FAQs

How should a procurement team structure long-term supply contracts in the Precious Metals Market?
Split volume between fixed-price forwards for baseline consumption and spot purchases for variable demand. Require refiner accreditation and chain-of-custody documentation in every contract, since unverified metal can be rejected by downstream customers [25].
What distinguishes a royalty or streaming company from a producer as an investment?
Royalty holders receive a share of output without bearing operating or capital cost inflation. This gives them margin stability during cost spikes, but they forgo the operational upside a producer captures when grades or throughput improve [15].
Which certification standards matter most for suppliers entering the Precious Metals Market?
LBMA Good Delivery accreditation governs bullion acceptance, while the Responsible Jewellery Council Code of Practices covers fabrication. Both now require documented recycled-content tracking for European buyers [14].
How do refiners price recycled feedstock differently from mined concentrate?
Recycled material is priced on an assayed-metal basis less a treatment charge, settling in days rather than months. Mined concentrate carries penalty elements, longer settlement and shipping risk that scrap contracts avoid [4].
What integration challenges arise when adopting hydrometallurgical recovery in the Precious Metals Market?
Leaching circuits demand tight feed characterisation and reagent handling permits that smelters do not require. Operators typically need 12 to 18 months to reach design recovery rates on mixed electronic scrap [4].
Is platinum-for-palladium substitution reversible once an automaker retools?
Not easily. Catalyst reformulation requires new emissions certification per engine family, so manufacturers hold a substituted formulation for several model years even after the price spread narrows [6].
What should buyers watch when sourcing from artisanal or small-scale production?
Verify that the refiner applies OECD due diligence and can trace material to a licensed cooperative. Undocumented artisanal gold is the most common source of rejected shipments in European supply chains [25].      
Author
Author
Author Profile
Anshula Mandaokar LinkedIn Team Lead - Research
Anshula Mandaokar holds an academic degree in Chemical Engineering and has been contributing to the field for more than 5 years. She has expertise in Market Research and Business Consulting and serves as a Team Lead for a reputed Market Research firm under the Chemicals and Materials domain spectrum. She has worked on multiple projects, generating explicit results in a quick turnaround time. Her understanding of data interpretation justifies her role as a leader.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of geological surveys, commodity exchanges, central bank reports, mining databases, and authoritative metals market publications. Key sources included the United States Geological Survey (USGS), World Gold Council (WGC), The Silver Institute, World Platinum Investment Council (WPIC), London Bullion Market Association (LBMA), London Metal Exchange (LME), COMEX (CME Group), International Monetary Fund (IMF) International Financial Statistics, World Bank Commodity Price Data, Bloomberg Commodity Index, Reuters Precious Metals Database, Bureau of Industry and Security (BIS) Export Statistics, Kimberley Process Certification Scheme, International Council on Mining and Metals (ICMM), National Mining Associations (NMA), GFMS Refinitiv Precious Metals Research, and central bank annual reports on gold reserves.

The following sources were employed to gather mine production statistics, global reserve estimates, trading volume data, regulatory compliance frameworks, pricing benchmarks, and industrial consumption patterns for gold, silver, platinum, palladium, rhodium, and ruthenium in the jewelry, electronics, investment, automotive catalyst, and aerospace sectorss.


Primary Research

Qualitative and quantitative insights were obtained by interviewing supply-side and demand-side stakeholders during the primary research process. Supply-side sources comprised Chief Executive Officers, Chief Geologists, Vice Presidents of Mine Operations, Heads of Precious Metals Trading, Refinery Directors, and Commodity Risk Managers from primary mining companies, streaming & royalty firms, precious metal refiners, and bullion banks. Procurement directors from electronics manufacturers, jewelry fabrication houses, automotive catalyst producers, aerospace alloy suppliers, investment bank commodity strategists, central bank reserve managers, and ETF fund managers constituted demand-side sources. Primary research verified market segmentation in both tangible and paper markets, verified mining project timelines and reserve declarations, and collected information on fabrication demand trends, recycling dynamics, hedging strategies, and LBMA/LPPM accreditation pathways.

Primary Respondent Breakdown:

By Designation: C-level Primaries (28%), Director Level (35%), Others (37%)

By Region: North America (32%), Europe (30%), Asia-Pacific (28%), Rest of World (10%)


Market Size Estimation

Production volume mapping and price discovery analysis were employed to determine global market valuation. The methodology comprised the following:

Identification of over 60 significant mining corporations, precious metal streaming/royalty entities, and integrated refiners in North America, Europe, Asia-Pacific, Latin America, and Africa

Product mapping for jewelry, semiconductors, automotive catalytic converters, dental applications, and investment vehicles that utilize gold, silver, platinum group metals (PGM), and specialty alloys

Examination of the reported annual revenues from mine gate sales, concentrate offtake agreements, and refined bullion deliveries that are specific to precious metal portfolios

Coverage of mining houses and refineries that account for 75-80% of the global market share in 2024

Derive segment-specific valuations across physical demand and financial derivatives markets through extrapolation using bottom-up (geological reserve × recovery rate × average spot price by metal type and country) and top-down (LBMA clearing statistics × average daily trading volume validation) approaches.

Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.