Pet Insurance Market (2026 - 2035)

Pet Insurance Market Size, Share and Research Report By Coverage Type (Accident Only, Accident and Illness, Wellness), By Animal Type (Dogs, Cats, Birds, Exotic Pets), By Distribution Channel (Direct Insurance, Brokers, Online), By Policy Type (Comprehensive Coverage, Limited Coverage, Time-Limited Coverage) and By Regional (North America, Europe, South America, Asia Pacific, Middle East and Africa) - Industry Forecast Till 2035

Forecast Period
2026-2035
CAGR
10.30%
2025 Market Size
USD 17.08 Billion
2035 Market Size
USD 46.06 Billion
BFSI ● Updated August 24, 2026 Report ID: MRFR/BS/10877-HCR | Pages: 200 | Author: Nirmit Biswas

Pet Insurance Market Summary

The Pet Insurance Market reached a valuation of USD 17.08 billion in 2025 and is projected to grow from USD 19.06 billion in 2026 to USD 46.06 billion by 2035, advancing at a CAGR of 10.30% during 2026–2035. Two structural forces anchor this trajectory: veterinary cost inflation that consistently outpaces the general consumer price index, and a widening "protection gap" where the vast majority of companion animals in major economies still carry no coverage. Pet owners increasingly view insurance as a budgeting tool rather than a luxury, and that behavioral shift is attracting capital from both legacy carriers and venture-backed insurtechs [1][2].

The technology layer underpinning the Pet Insurance Market is evolving rapidly. Manual claims adjudication and paper-based underwriting — once standard — are giving way to straight-through processing powered by large language models and optical character recognition. Embedded distribution, where coverage is offered at the veterinary checkout counter or within pet-retail e-commerce flows, is compressing the traditional sales funnel. Insurers deploying these digital pipelines report loss-adjustment expense ratios 15–20% lower than peers still reliant on legacy workflows [3][4].

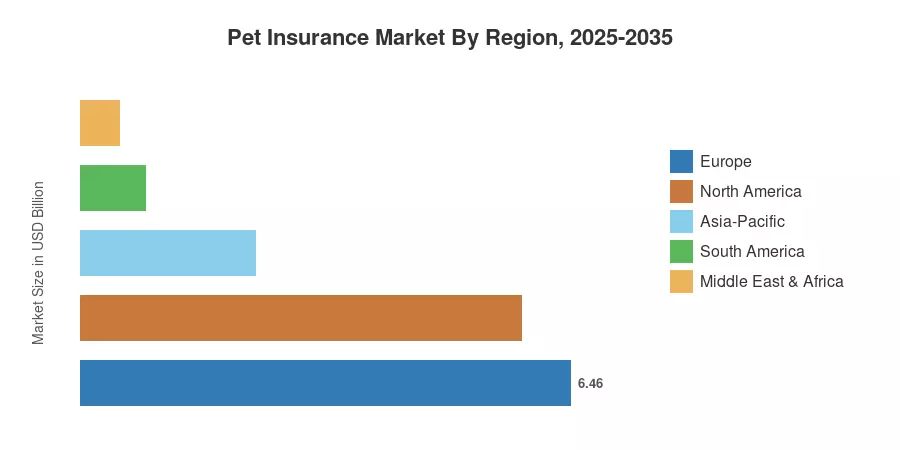
Europe commands the largest share of the Pet Insurance Market at roughly 38% of global premiums, driven by mature Scandinavian markets where penetration among dog owners exceeds 40%. Asia-Pacific is the fastest-growing region with a projected CAGR of 13.50%, fueled by rising middle-class pet ownership in China, Japan, and South Korea. North America holds roughly 34% of the market, and the runway there remains substantial, given U.S. penetration sits below 5%[6]. The decade ahead will reward insurers that can marry frictionless digital distribution with actuarially sound product design.

Key Report Takeaways

• By Policy Type

  • Accident & illness policies accounted for 76.8% of the Pet Insurance Market in 2025, reflecting owner preference for comprehensive coverage over limited plans.
  • Wellness and preventive-care add-ons are projected to expand at a 14.20% CAGR through 2035, driven by growing demand for routine-care reimbursement.

• By Animal Type

  • Dogs captured 69.7% of the Pet Insurance Market share in 2025, supported by higher average claim values and longer policy retention rates.
  • Other companion animals — including exotic pets and rabbits — are the fastest-growing category with a projected CAGR of 12.90%.

• By Region

  • Europe leads the global Pet Insurance Market, underpinned by regulatory frameworks in Sweden, the UK, and Germany that normalize coverage.
  • Asia-Pacific is expanding at a 13.50% CAGR, the fastest of any region, as urbanization and pet humanization trends accelerate adoption.


Pet Insurance Market Size and Forecast (2021–2035)

Market sizing draws on premium written volume reported by national insurance regulators, NAPHIA enrollment data, company filings, and proprietary survey instruments covering 35 countries. Historical figures reflect actual premium collections; forecast values apply a calibrated compound growth model adjusted for penetration ceilings, veterinary inflation indices, and regulatory pipeline analysis [1].
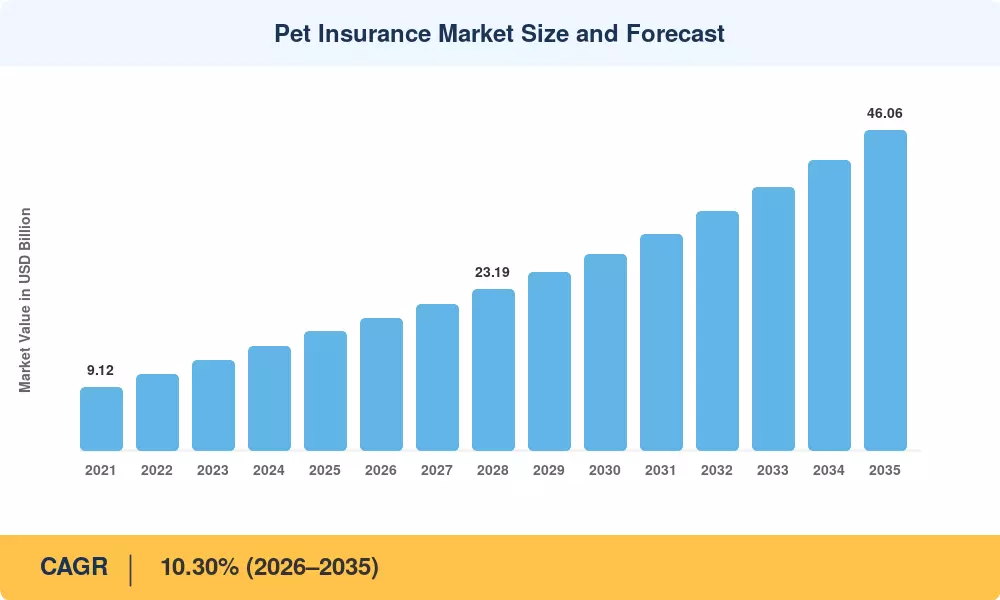
Pet Insurance Market Size and Forecast
Our Impact
Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals
Partnering with 2000+ Global Organizations Each Year
30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
Veterinary cost inflation +2.8% Global Short-term (≤2 yr)
Embedded distribution at point of care +1.9% North America, Europe Medium-term (2–4 yr)
Insurtech automation & AI claims processing +1.6% Global Medium-term (2–4 yr)
Rising pet ownership in Asia-Pacific +1.4% Asia-Pacific Long-term (≥4 yr)
Employer-sponsored voluntary benefits +1.1% North America Medium-term (2–4 yr)
Regulatory mandates (e.g., UK pet welfare reforms) +0.8% Europe Long-term (≥4 yr)
Humanization of pets & premiumization +0.7% Global Long-term (≥4 yr)


Veterinary Cost Inflation

Veterinary services account for approximately 30% of annual household pet spending in the United States, and the American Veterinary Medical Association reports that per-visit costs have risen at roughly double the rate of headline CPI over the past five years [1]. This persistent inflation creates a natural pull toward insurance as owners seek predictable monthly outlays over unpredictable emergency bills. The dynamic is self-reinforcing: wider coverage enables owners to approve more advanced treatments, which in turn drives further cost growth and strengthens the insurance value proposition.

Embedded Distribution at Point of Care

Presenting insurance offers at the moment a pet owner is paying a veterinary bill or completing an online pet-supply purchase shortens the consideration window dramatically. NAPHIA data show that conversion rates for embedded offers are two to three times higher than for standalone digital marketing campaigns [3]. Retailers such as Chewy and veterinary networks like VCA have integrated underwriting APIs that can bind a policy in under two minutes, and this channel accounted for an estimated 18% of new policy originations in North America during 2024 [8].

Insurtech Automation and AI Claims Processing

Digital-native carriers have compressed the average claim turnaround from 10–14 days to under 48 hours by deploying optical character recognition, LLM-based invoice parsing, and automated fraud-scoring models [4]. Straight-through processing rates above 60% allow these firms to operate with combined ratios competitive with traditional carriers despite smaller books of business. The customer-experience advantage translates into higher net promoter scores and stronger retention curves, creating a flywheel that threatens incumbents lacking comparable digital stacks.

Employer-Sponsored Voluntary Benefits

Roughly 25% of Fortune 500 companies in the United States now offer pet insurance as a voluntary payroll-deducted benefit, up from fewer than 10% in 2019 [8]. Because the employer bears no premium cost, the channel offers a low-friction acquisition path for carriers while providing employees a perceived workplace perk. Group discount structures typically reduce individual premiums by 5–10%, further lowering the adoption barrier within the Pet Insurance Market.

Restraints Impact Analysis

Restraint impacts below represent estimated negative pressure on market growth. They are not directly subtracted from the CAGR and should be read as qualitative severity assessments.

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
Pre-existing condition exclusions limiting perceived value –1.4% Global Short-term (≤2 yr)
Consumer awareness gaps in underpenetrated markets –1.2% Asia-Pacific, South America Long-term (≥4 yr)
Premium affordability amid cost-of-living pressures –1.0% Europe, North America Short-term (≤2 yr)
Regulatory fragmentation across jurisdictions –0.7% Global Medium-term (2–4 yr)
Claims denial disputes eroding trust –0.5% North America Medium-term (2–4 yr)


Pre-Existing Condition Exclusions

Unlike human health insurance in many jurisdictions, the Pet Insurance Market universally excludes pre-existing conditions, and ambiguity around what qualifies as "pre-existing" remains the single largest source of consumer complaints [10]. A 2024 survey by the National Association of Insurance Commissioners found that 37% of policyholders who filed a claim reported confusion over condition-classification language. Until the industry converges on standardized definitions — or regulators mandate them — the trust deficit will suppress conversion among price-sensitive segments.

Consumer Awareness Gaps

In markets such as China, India, and Brazil, pet ownership is surging, but insurance awareness remains negligible. Fewer than 2% of pet owners in these countries can name a single carrier, and distribution infrastructure beyond metropolitan areas is virtually nonexistent. Building brand recognition and agent networks in fragmented retail environments requires sustained investment with long payback periods, constraining near-term penetration growth in the Pet Insurance Market.

Premium Affordability

Rising cost-of-living pressures in Western economies create downward price sensitivity. Industry data indicate that lapse rates for the Pet Insurance Market climbed roughly 3 percentage points between 2022 and 2024 in the UK, correlating with periods of elevated consumer inflation [11]. Carriers face a delicate balancing act: raising premiums to match veterinary inflation while avoiding lapse acceleration.

Pet Insurance Market Opportunities

Telehealth and Digital Wellness Platforms

Insurers offering virtual veterinary consultations as part of insurance policies can lower the costs of low-acuity claims and enhance the perceived value of coverage. Early movers say policyholders having access to 24/7 telemedicine triage have 12-15% lower claims frequency, a win-win for retention and loss ratios[13].

Emerging-Market Penetration in Southeast Asia and Latin America

Pet populations in Indonesia, Vietnam and Colombia are expanding at double-digit rates, although insurance penetration in these countries is essentially zero. Microinsurance solutions, priced at less than USD 5 per month and supplied via mobile wallets and super-apps, provide a greenfield opportunity in the Pet Insurance Market.

Data Monetization and Predictive Underwriting

Claims databases that compile millions of veterinary invoices contain rich signals on breed-specific disease trajectories, regional treatment-cost curves, and prescription patterns. Carriers can monetise anonymized data sets through collaborations with pharmaceutical businesses and pet-food producers while using the same data internally to improve risk selection[14].

Lifetime and Multi-Pet Policy Innovation

The pet insurance market is still largely based on annual renewal cycles, which leaves providers open to adverse selection at each renewal window. Policies that offer lifetime protection regardless of claims history (already prevalent in the UK) have room to grow in North America and Asia-Pacific, where such products are scarce[15].

Integration with Pet Wearables and IoT

Connected collars and health-monitoring devices generate real-time activity, heart-rate, and sleep data. Insurers partnering with wearable manufacturers can develop usage-based pricing models that reward proactive pet health management, similar to the telematics revolution in auto insurance[16].

Pet Insurance Market Future Outlook

AI-Driven Underwriting and Personalized Pricing

Within the Pet Insurance Market, breed-specific risk models will give way to individualized pricing engines that ingest veterinary history, wearable telemetry, and genomic predisposition data. By 2030, carriers deploying these models could achieve loss ratios 8–12 percentage points below the industry average, fundamentally altering competitive positioning [14][16].

Platform Economics and Ecosystem Bundling

The next decade will see the Pet Insurance Market increasingly embedded within broader pet-care platforms that bundle food subscriptions, telehealth, grooming, and insurance into single monthly memberships. Platform operators capturing the pet-owner relationship at the e-commerce layer will extract distribution economics that standalone carriers cannot match, mirroring the super-app model already visible in China [17].

Regulatory Standardization and Consumer Protection

Regulators in the UK, Australia, and select U.S. states are advancing product-disclosure requirements that mandate standardized definitions of "pre-existing condition," "waiting period," and "bilateral exclusion." The NAIC Pet Insurance Model Act, adopted by a growing number of states, is expected to create a more uniform regulatory floor for the Pet Insurance Market by the early 2030s [9][12].

Climate-Linked and Parametric Products

Rising temperatures are expanding the geographic range of tick-borne diseases, heartworm, and heat-related illness in companion animals. Parametric products that trigger automatic payouts when regional temperature or disease-incidence thresholds are breached represent a frontier product class. The convergence of climate data, veterinary epidemiology, and parametric insurance design could unlock a new growth vector for the Pet Insurance Market during the second half of the forecast period [20][21].

Pet Insurance Market Segmentation

By Policy Type

Segment Key Metric Primary Demand Driver
Accident & Illness 76.8% market share (2025) Comprehensive coverage preference
Accident-Only 8.20% CAGR (2026–2035) Budget-conscious entry-level buyers
Wellness / Preventive Add-Ons 14.20% CAGR (2026–2035) Routine-care reimbursement demand


Accident & illness policies dominate the Pet Insurance Market because pet owners increasingly expect coverage that mirrors human health insurance breadth. Plans typically reimburse 70–90% of eligible veterinary expenses after a deductible, and the average annual premium for dogs under these plans ranges from USD 500 to USD 700, depending on breed and geography. Wellness add-ons — covering vaccinations, dental cleanings, and annual checkups — are the fastest-growing sub-segment as carriers use them to deepen policyholder engagement and reduce lapse rates [2].

By Animal Type

Segment Key Metric Primary Demand Driver
Dogs 69.7% market share (2025) Higher claim frequency and average claim value
Cats 9.80% CAGR (2026–2035) Growing indoor-cat ownership trends
Other Pets 12.90% CAGR (2026–2035) Exotic pet popularity and specialist vet costs


Dogs anchor the Pet Insurance Market on both a premium and a claims basis: average annual claims for insured dogs run 40–50% higher than for cats, and dog owners show a higher willingness to approve advanced diagnostics and surgical interventions. The "other pets" category — spanning rabbits, birds, reptiles, and exotic mammals — is gaining traction as specialist veterinary care costs for these animals rise and dedicated products emerge from niche carriers [2][10].

By Provider Type

Segment Key Metric Primary Demand Driver
Traditional Carriers 64.9% market share (2025) Brand trust and multi-line bundling
Insurtech / Digital Providers 15.20% CAGR (2026–2035) Speed, UX, and cost-efficiency advantages


Traditional carriers retain the majority of the Pet Insurance Market through established brand recognition and the ability to bundle pet coverage with homeowners or auto policies. Insurtechs, however, are gaining share rapidly by offering mobile-first enrollment, instant claims settlement, and transparent pricing — attributes that resonate strongly with millennial and Gen-Z pet owners who now represent the majority of first-time policy buyers [3][4].

By Sales Channel

Segment Key Metric Primary Demand Driver
Direct-to-Consumer 42.1% market share (2025) Digital marketing and mobile app enrollment
Intermediated (Brokers/Agents) 12.80% CAGR (2026–2035) Employer-benefit and veterinary-clinic partnerships
Embedded / Affinity 16.40% CAGR (2026–2035) Point-of-sale integration at retail and vet checkout


Direct-to-consumer remains the largest channel within the Pet Insurance Market, powered by SEO-driven comparison shopping and carrier-branded mobile apps. The embedded and affinity channel is growing fastest as retailers and veterinary networks integrate API-based underwriting into checkout flows [3][8].

Regional Market Share Analysis

Region Key Metric Primary Investment Themes
North America 34.1% market share Employer benefits expansion, DTC digital platforms
Europe 37.8% market share Regulatory normalization, lifetime policy adoption
Asia-Pacific 13.50% CAGR (2026–2035) Rising middle-class pet ownership, mobile distribution
South America USD 0.86 Billion (2025) Microinsurance pilots, urban pet humanization
Middle East & Africa USD 0.52 Billion (2025) Expat-driven demand, luxury pet segment
Total USD 17.08 Billion (2025)

The Pet Insurance Market exhibits pronounced regional asymmetry. Mature European markets with decades of consumer familiarity anchor the global premium pool, while rapid pet-ownership growth in Asia-Pacific is reshaping the competitive map.


North America

Country Key Metric Key Driver
US 82.4% of regional share Low penetration ceiling headroom
Canada 12.60% CAGR Trupanion-led market maturation
Mexico USD 0.18 Billion (2025) Growing urban pet ownership


The United States is the single largest national Pet Insurance Market, yet penetration remains below 5% of insurable pets, leaving immense runway compared to Scandinavian benchmarks. Canada's regulatory clarity around insurance product classification has enabled faster carrier entry, while Mexico's nascent market is catalyzed by private veterinary chain expansion [6][8].

Europe

Country Key Metric Key Driver
Germany 8.90% CAGR Mandatory liability insurance spillover
UK 26.3% of regional share Mature direct and comparison-site distribution
France USD 0.68 Billion (2025) Government pet welfare initiatives
Italy 9.40% CAGR Digital insurer market entry
Spain USD 0.34 Billion (2025) Growing urban pet adoption
Nordic Countries 31.2% of regional share Highest global penetration rates
Russia 11.10% CAGR Early-stage market formation
Rest of Europe USD 0.47 Billion (2025) Regulatory harmonization efforts


Sweden's penetration rate — where roughly half of dogs carry coverage — serves as the global benchmark the Pet Insurance Market aspires to replicate elsewhere. The UK's price-comparison ecosystem makes it the most competitive European arena, and recent FCA guidance on product-value assessments is pushing carriers toward more transparent policy wordings [9][15].

Asia-Pacific

Country Key Metric Key Driver
China 16.20% CAGR E-commerce embedded distribution
India 17.80% CAGR Pet-tech startup ecosystem
Japan 28.5% of regional share Aging society, pet-as-family culture
South Korea 15.30% CAGR Government pet registration mandates
ASEAN USD 0.12 Billion (2025) Mobile-first microinsurance pilots
Rest of Asia-Pacific 11.40% CAGR Urbanization and income growth


Japan's Pet Insurance Market is the most mature in the region, with Anicom Holdings and ipet Insurance commanding significant market presence. China's pet economy exceeded USD 50 billion in 2024, and platform giants like Ant Group and Ping An are embedding coverage within broader pet-services super-apps[17].

South America

Country Key Metric Key Driver
Brazil 64.3% of regional share Largest pet population in the region
Argentina 12.50% CAGR Veterinary chain formalization
Rest of South America USD 0.11 Billion (2025) Early-stage consumer education


Brazil's pet population — the third largest globally — provides a massive addressable base, though insurance awareness outside São Paulo and Rio de Janeiro remains low. Fintech-led distribution through Nubank and MercadoLibre checkout flows is beginning to shift the demand curve [18].

Middle East & Africa

Country Key Metric Key Driver
Saudi Arabia 13.70% CAGR Vision 2030 quality-of-life programs
UAE 38.5% of regional share Affluent expat pet-owner base
South Africa USD 0.08 Billion (2025) Veterinary network expansion
Egypt 14.10% CAGR Emerging urban pet culture
Rest of MEA USD 0.06 Billion (2025) Limited formal market structures


The UAE's Pet Insurance Market is anchored by a high-income expatriate community accustomed to comprehensive insurance bundles. Saudi Arabia's quality-of-life diversification under Vision 2030 is catalyzing new pet-related commerce, though regulatory frameworks for specialty insurance lines are still developing [19].


Pet Insurance Market By Region, 2025-2035

Competitive Benchmarking

The Pet Insurance Market exhibits low concentration with a fragmented competitive structure. The top five carriers collectively control an estimated 30–38% of global premiums, and no single player holds more than 12% share. The HHI index sits well below 1,000, indicative of a competitive arena where digital disruptors can gain footholds without dislodging incumbents. Regional specialization remains strong — European leaders like Agria and Animal Friends hold limited presence in North America, while U.S.-centric players like Trupanion have minimal European enrollment.

Company Est. Revenue Share Range Key Offerings for Pet Insurance Market Strategic Positioning
Trupanion ~8–11% Direct pay model, comprehensive A&I Vet-clinic integration leader in North America
Nationwide Pet Insurance ~5–8% Multi-species coverage, wellness plans Largest U.S. multi-line carrier offering pet
Petplan (Allianz) ~4–7% Lifetime policies, UK/EU focus European market leader with brand heritage
Agria Pet Insurance ~3–6% Breed-specific products, Nordic dominance Highest penetration in Scandinavian markets
ManyPets (Bought By Many) ~3–5% AI-driven pricing, multi-market expansion Digital-native pan-European disruptor
Lemonade Pet ~2–4% Instant claims, app-first UX Insurtech with cross-sell from renters/home
Embrace Pet Insurance ~2–4% Diminishing deductible, wellness rewards Customer loyalty focus in U.S. market
Anicom Holdings ~3–5% In-hospital instant settlement, Japan market Dominant player in Asia's most mature market
ASPCA Pet Health Insurance ~2–4% Brand trust via ASPCA affiliation Affinity distribution through nonprofit partnership
Figo / Independence Pet ~2–4% Cloud-based platform, B2B2C model White-label underwriting for partner brands


Recent News & Developments

  • Trupanion (October 2024): Expanded its direct-pay veterinary network to over 10,000 hospitals across North America, reducing out-of-pocket friction for policyholders at the point of care [8].
  • UK Financial Conduct Authority (March 2024): Published final guidance on pet insurance product-value assessments, requiring carriers to demonstrate that claims ratios meet minimum consumer-value thresholds [9].
  • NAIC (July 2023): Released the updated Pet Insurance Model Act establishing standardized definitions for waiting periods and pre-existing conditions, with 15 U.S. states adopting or introducing legislation by year-end [12].


Pet Insurance Market Report Scope

Attribute Detail
Market Scope Global Pet Insurance Market — all policy types, animal types, provider types, sales channels
Study Period 2021–2035
CAGR (Forecast) 10.30% (2026–2035)
Market Size (2025) USD 17.08 Billion
Market Size (2035) USD 46.06 Billion
Fastest Growing Segment Wellness / preventive add-ons (by policy type); Other pets (by animal type)
Companies Profiled 10
Valuation Currency USD Billion

FAQs

How do reimbursement models differ across the Pet Insurance Market, and which model benefits policyholders most?
Most carriers use a percentage-of-invoice reimbursement model (typically 70–90%) after a deductible, while Trupanion offers direct payment to veterinary clinics. Direct-pay models eliminate the upfront out-of-pocket burden for pet owners [8].
What underwriting data points do insurers evaluate when pricing a new Pet Insurance Market policy?
Carriers assess breed, age, zip code, species, and prior claims history to set premiums. Some digital providers now incorporate wearable health data and genomic risk scores into their pricing algorithms [14].
How does the Pet Insurance Market handle hereditary and congenital condition coverage?
Policies vary widely — some exclude hereditary conditions entirely, while comprehensive plans cover them after waiting periods of 6–14 months. Buyers should compare exclusion schedules before binding a policy [10].
What role do comparison aggregators play in shaping competition within the Pet Insurance Market?
In the UK, aggregators like GoCompare and Comparethemarket drive over 40% of new policy originations and intensify price competition. This dynamic compresses margins but accelerates consumer adoption [15].
How are multi-pet discount structures evolving within the Pet Insurance Market?
Leading carriers offer 5–10% discounts per additional pet on the same policy. Bundled multi-pet plans also reduce administrative costs, improving retention and lifetime customer value [6].
What claims-processing benchmarks separate top-performing carriers in the Pet Insurance Market?
Best-in-class digital carriers settle claims within 24–48 hours with straight-through processing rates above 60%. Legacy carriers average 10–14 business days, creating a measurable experience gap [4].
How might breed-specific legislation influence the Pet Insurance Market over the next decade?
Breed-specific bans or restrictions — such as the UK's Dangerous Dogs Act — directly narrow the insurable population. Regulatory shifts expanding or relaxing breed lists would reshape risk pools for carriers [9].    
Author
Author
Author Profile
Nirmit Biswas LinkedIn Senior Research Analyst
With 5+ years of expertise in Market Intelligence and Strategic Research, Nirmit Biswas specializes in ICT, Semiconductors, and BFSI. Backed by an MBA in Financial Services and a Computer Science foundation, Nirmit blends technical depth with business acumen. He has successfully led 100+ projects for global enterprises and startups, including Amazon, Cisco, L&T and Huawei, delivering market estimations, competitive benchmarking, and GTM strategies. His focus lies in transforming complex data into clear, actionable insights that drive growth, innovation, and investment decisions. Recognized for bridging engineering innovation with executive strategy, Nirmit helps businesses navigate dynamic markets with confidence.
Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.
















