Packaging Robots Market (2026 - 2035)

Packaging Robots Market Size, Share and Research Report By Robot Type (Articulated Robots, SCARA Robots, Delta Robots, Cartesian/Gantry Robots, Collaborative Robots, and Others), By Gripper Type (Clamp, Claw, Vacuum, and Others), By Application (Packing, Pick and Place, Palletizing, and Others), And By End-User Industry (Food, Beverage, Pharmaceutical, Personal Care and Cosmetics, Electronics and Semiconductor, E-commerce, and Others) – Industry Forecast Till 2035
ID: MRFR/SEM/23011-HCR 128 Pages Aarti Dhapte, Aarti Dhapte Last Updated: October 13, 2026
Packaging Robots Market
Market Size
Forecast Period2026-2035
CAGR (2026-2035)11.2%
2025 Market SizeUSD 7.85 Billion
2035 Market SizeUSD 22.70 Billion
Key Players
FANUC Corporation
ABB Ltd
KUKA AG
Yaskawa Electric Corporation
Universal Robots
Kawasaki Heavy Industries
Opportunities
  • Outcome-Based Service and Data Monetization
  • Emerging-Market Food and Beverage Capacity
  • Recyclable-Format Line Changeovers

Packaging Robots Market Summary

The global Packaging Robots Market was valued at USD 7.85 billion in 2025 and is forecast to reach USD 8.73 billion in 2026, rising to USD 22.70 billion by 2035 at a CAGR of 11.2% over 2026–2035. Two catalysts anchor this outlook. U.S. retail e-commerce sales crossed USD 1.19 trillion in 2024, about 16% of total retail [3], pushing parcel hubs and brand owners to automate order assembly. In Europe, the Packaging and Packaging Waste Regulation (EU) 2025/40 is forcing manufacturers to re-engineer lines for recyclable and reusable formats [6].

Manufacturers are retiring fixed-function case packers and manual end-of-line stations in favor of vision-guided articulated arms, delta pickers, and collaborative robots that can be redeployed between SKUs in minutes. The International Federation of Robotics recorded 541,302 industrial robot installations worldwide in 2023, the second-highest annual total on record [1], and food, consumer goods, and logistics users are absorbing a growing share of that capacity. Robotics-as-a-Service contracts are lowering the entry barrier for mid-sized plants that previously could not justify a capital purchase.

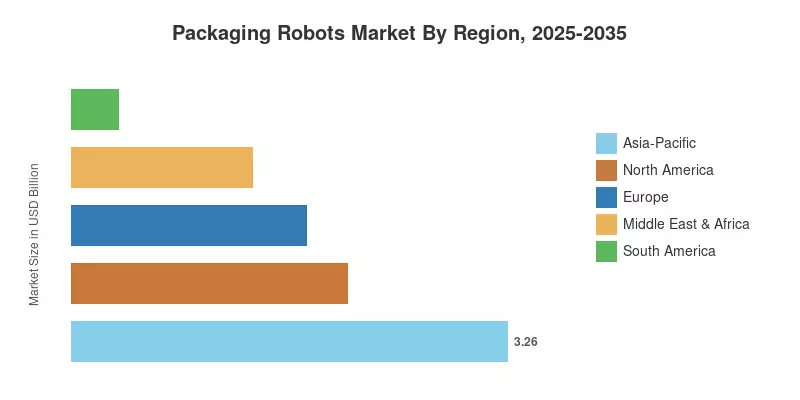
Asia-Pacific leads with a 41.5% share in 2025, supported by China's robot-density goals under its 14th Five-Year Robot Industry Development Plan . Middle East & Africa is the fastest-growing region at a 17.2% CAGR, while North America ranks second with a 26.2% share as reshoring and wage inflation accelerate retrofits. Over the next decade, software-defined grasping and flexible financing will decide which vendors capture the Packaging Robots Market's next wave of demand.

Key Report Takeaways

The takeaways below summarize where value and growth concentrate across the Packaging Robots Market by segment and geography.

• By Robot Type

  • Articulated Robots held a 39.4% share of the Packaging Robots Market in 2025, reflecting six-axis versatility from bottle loading to pallet stacking
  • Collaborative Robots are projected to expand at a 14.3% CAGR through 2035 as cage-free deployment gains regulatory acceptance

• By Gripper Type

  • Clamp grippers accounted for a 35.0% revenue share in 2025, serving rigid cartons and cans on fast-moving consumer goods lines
  • Claw grippers are forecast to grow at a 13.3% CAGR, driven by irregular e-commerce SKUs

• By Application

  • Packing generated a 42.4% revenue share in 2025, covering primary through tertiary containment
  • Pick and Place is expected to post a 14.3% CAGR as omnichannel retailers automate order assembly

• By End-User Industry

  • Food processors represented a 41.1% share of the Packaging Robots Market in 2025, driven by hygiene and throughput requirements
  • E-commerce is the fastest-growing end user at a 17.6% CAGR

• By Region

  • Asia-Pacific commanded a 41.5% share in 2025
  • Middle East & Africa is set to grow at a 17.2% CAGR
  • Europe held a 22.4% share, anchored by German and Italian machinery clusters

Market Size and Forecast (2021–2035)

Estimates for the Packaging Robots Market combine shipment data from the International Federation of Robotics [1][2] and the Association for Advancing Automation [5], company filings from leading robot OEMs, and more than 350 interviews with integrators, packaging machinery builders, and end users. Historical values were reconciled against installed-base and average-selling-price trends, and forecasts were built bottom-up by end-user industry before top-down validation against industrial capital expenditure.
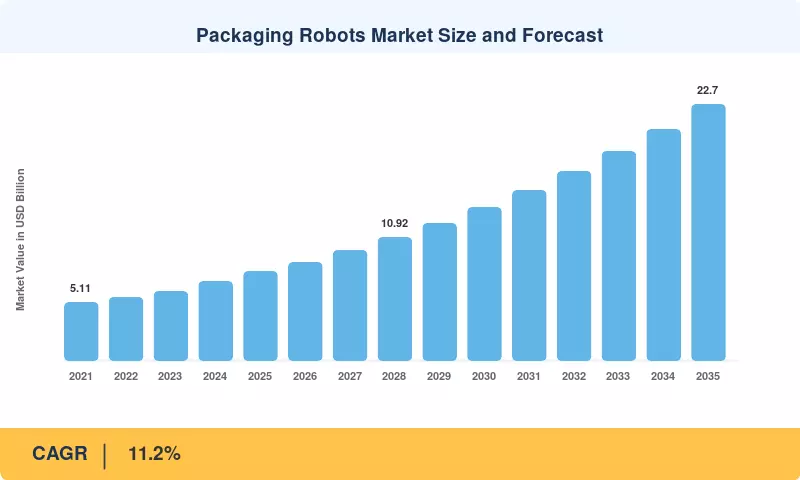
Packaging Robots Market Size and Forecast
Our Impact

Enabled $4.3B Revenue Impact for Fortune 500 and Leading Multinationals

Partnering with 2000+ Global Organizations Each Year

30K+ Citations by Top-Tier Firms in the Industry

Driver Impact Analysis

Driver ~% Impact on CAGR Geographic Relevance Impact Timeline
E-commerce fulfillment volumes +2.4% Global; strongest in North America and China Short-term (≤2 yr)
Manufacturing labor shortages +2.1% North America, Europe, Japan, South Korea Medium-term (2–4 yr)
AI vision and predictive maintenance +1.6% Global Medium-term (2–4 yr)
Robotics-as-a-Service financing +1.2% North America, Europe Medium-term (2–4 yr)
Updated collaborative safety standards +1.0% Global Long-term (≥4 yr)
Traceability and serialization mandates +0.9% United States, Europe Short-term (≤2 yr)

E-commerce Fulfillment Volumes

Online retail continues to reshape packaging demand. U.S. e-commerce reached USD 1.19 trillion in 2024 [3], and each order requires individual picking, packing, and labeling rather than case-level handling. Amazon reported more than 750,000 robots operating across its network in 2023 [12], setting a benchmark that third-party logistics providers and brand owners now chase. Single-piece flow multiplies the number of robotic touches per unit shipped, lifting demand for pick-and-place and case-packing cells.

Manufacturing Labor Shortages

and The Manufacturing Institute estimate U.S. manufacturers will need 3.8 million workers by 2033, with as many as 1.9 million roles potentially unfilled . Packing and palletizing are repetitive, injury-prone jobs with high turnover, making them the first stations owners automate. Plants replacing manual end-of-line packaging systems typically redeploy two to three operators per shift into quality and maintenance roles, which improves retention while protecting output during peak seasons.

AI Vision and Predictive Maintenance

Embedded machine vision lets robots identify product orientation and adjust grips without fixtures, cutting changeover time on mixed-SKU lines. research indicates predictive maintenance can reduce machine downtime by 30–50% . For packaging lines where one stoppage idles fillers, labelers, and conveyors, these savings are significant. Vendors are bundling condition-monitoring software with new arms, turning uptime guarantees into a central part of the commercial proposal.

Robotics-as-a-Service Financing

Subscription models convert a six-figure capital purchase into a predictable monthly fee covering hardware, integration, and service. The Association for Advancing Automation reported North American companies ordered 31,311 robots in 2024 [5], with growing interest from first-time buyers in food and consumer goods. RaaS removes balance-sheet hurdles for small and mid-sized co-packers, which historically lacked the engineering staff and capital budgets to justify automation.

Updated Collaborative Safety Standards

The 2025 revisions of ISO 10218-1 and ISO 10218-2 consolidated collaborative-application requirements into the core robot safety standard [9]. Clearer rules shorten risk assessments and give insurers and plant safety managers a defined compliance path. Collaborative robots already represented about 10.5% of global industrial installations in 2023 [1], and the revised standards should accelerate cage-free deployments on space-constrained packing lines.

Traceability and Serialization Mandates

The U.S. Drug Supply Chain Security Act requires interoperable, package-level tracing across pharmaceutical supply chains , while the FDA's FSMA Section 204 Food Traceability Rule adds record-keeping for high-risk foods, with compliance now targeted for July 2028 . Robots integrated with vision and code readers verify, aggregate, and log serialized units at line speed. Manual aggregation simply cannot match that accuracy, making automation a compliance tool rather than a discretionary upgrade.

Restraints Impact Analysis

Restraint ~% Impact on CAGR Geographic Relevance Impact Timeline
High upfront capital and integration costs −1.8% Global; acute for SMEs Short-term (≤2 yr)
Shortage of robot programming and maintenance skills −1.3% North America, Europe Medium-term (2–4 yr)
Handling of flexible and irregular packages −0.9% Global Medium-term (2–4 yr)
Cybersecurity and connected-cell compliance −0.6% Europe, North America Long-term (≥4 yr)
Trade measures on imported robots and components −0.7% United States Short-term (≤2 yr)

High Upfront Capital and Integration Costs

The robot arm is often less than half of total project cost. PMMI surveys show integration, end-of-arm tooling, guarding, and conveyors commonly double or triple the hardware price [14]. For co-packers running low-margin contracts, a USD 250,000 cell can be difficult to justify without multi-year volume commitments, delaying purchases even where labor savings are clear.

Shortage of Robot Programming and Maintenance Skills

Owners need technicians who can program, troubleshoot, and recalibrate robotic cells. The same skills gap driving automation also limits it: identifies digital and technical skills as the hardest manufacturing roles to fill . Plants without in-house expertise rely on integrators for routine changes, which raises operating costs and slows SKU introductions.

Handling of Flexible and Irregular Packages

Conventional grippers distort polybags, pouches and thin-wall recyclable containers. Integrators polled by Market Research Future report mispick rates of 1-3% on soft packaging, but well under 0.5% on rigid boxes. Every failure demands manual intervention and reduces the labor savings that justified the expenditure, causing purchasers to select more costly specialized tooling.

Cybersecurity and Connected-Cell Compliance

Networked robots expand the plant attack surface. The EU Cyber Resilience Act, Regulation (EU) 2024/2847, imposes security-by-design and vulnerability-reporting duties on connected products, with core obligations applying from December 2027 [15]. Compliance adds engineering cost for OEMs and lengthens IT approval cycles for buyers connecting robots to cloud analytics.

Trade Measures on Imported Robots and Components

Most of the packing robots and precision reducers are made in Japan, Europe and China. In 2025, the U.S. Department of Commerce initiated a Section 232 investigation on imports of robots and industrial machinery [16], which created price uncertainty for U.S. buyers. Some projects postponed until tariff exposure is clearer.

Packaging Robots Market Opportunities

Several gaps in the Packaging Robots Market offer above-average returns for vendors that move early.

Outcome-Based Service and Data Monetization

Vendors can market uptime and throughput guaranties, not only hardware margins. Connected cells send fleet data into benchmarking dashboards, predictive spare-parts programs, and per-pick pricing. This concept has a natural pairing with the RaaS financing discussed in Section 4.4 and produces recurrent revenue less sensitive to capital investment cycles .

Emerging-Market Food and Beverage Capacity

Saudi Arabia's National Industrial Strategy targets major growth in local manufacturing output , while India's Production Linked Incentive scheme for food processing supports new plants built with modern lines [21]. Greenfield facilities in these markets can install robots from day one rather than retrofitting, giving vendors with local service partners a clear entry point.

Recyclable-Format Line Changeovers

The PPWR requires all packaging placed on the EU market to be recyclable by 2030 [6]. Switching to mono-material films and fiber-based trays changes product stiffness and surface friction, which means many existing grippers and pick patterns must be redesigned. Suppliers offering soft-touch end effectors and rapid recipe changeovers stand to win replacement business across European brand owners.

Micro-Fulfillment and Mixed-SKU Picking

Retailers are bringing order assembly closer to consumers via urban micro-fulfillment centers. Such tiny venues require flexible pick-and-place cells that work along with warehouse robotics such as autonomous mobile robots and goods-to-person storage. The crucial enabler is AI understanding models that can handle thousands of SKUs without manual education.

Aseptic and Pharmaceutical Packaging

Biologics and sterile injectables require packaging with minimal human presence to reduce contamination risk. Robots designed for isolators and hydrogen-peroxide decontamination address this need while also supporting serialization under DSCSA . Vendors offering validated, pre-qualified cells can shorten commissioning for drug manufacturers.

Packaging Robots Market Future Outlook

Four themes will shape how the Packaging Robots Market evolves over the coming decade.

AI-Native Grasping and Self-Programming Cells

Foundation models trained on millions of grasp attempts will let robots handle unfamiliar items without teaching. By the early 2030s, most new pick-and-place cells should ship with self-learning vision, cutting integration hours and making low-volume SKUs economical to automate. This shift will move value from mechanical hardware toward software and data .

Platform Economics and Ecosystems

Collaborative robot vendors are building app-store-style ecosystems of certified grippers, vision kits, and palletizing software. SoftBank's agreement in 2025 to acquire ABB's robotics division signals how investors view robotics as a platform play. Buyers will increasingly choose vendors based on the breadth of compatible accessories rather than arm specifications alone.

Sustainability and Circular Packaging

The PPWR's recyclability and reuse targets for 2030 and 2040 [6] will force repeated line reconfigurations. Robots that switch between returnable crates, fiber trays, and mono-material films with software changes will replace fixed machinery. Energy-efficient drives and regenerative braking will also matter as brand owners report Scope 2 emissions.

Regionalized Supply Chains

Trade measures [16] and reshoring incentives are pushing production closer to consumers in North America and Europe. Smaller, distributed plants need flexible automation rather than dedicated high-speed lines, which favors modular robotic cells. Regional assembly by robot OEMs will expand as they seek to reduce tariff exposure.

Regional Market Share Analysis

Region Key Metric (2025) Primary Investment Themes
North America 26.2% share Labor replacement, e-commerce fulfillment, reshoring
Europe 22.4% share Sustainable packaging changeovers, machinery compliance
Asia-Pacific 41.5% share Electronics and food capacity, government robot-density targets
South America USD 0.35 Billion Beverage and protein export lines
Middle East & Africa 17.2% CAGR Greenfield food plants, industrial diversification
Total USD 7.85 Billion —

Regional demand in the Packaging Robots Market follows manufacturing density, labor costs, and the maturity of local integrator networks.

North America

Country Key Metric Key Driver
US 78.4% share of region E-commerce volumes and labor scarcity
Canada USD 0.21 Billion Food processing and agri-food export lines
Mexico 12.6% CAGR Nearshoring of consumer goods manufacturing

The United States dominates regional spending, with North American robot orders reaching 31,311 units in 2024 [5]. Food, consumer goods, and logistics buyers account for a rising portion of orders as automotive demand moderates. Canada's protein and bakery processors are automating to offset rural labor shortages, while Mexico benefits from nearshoring as U.S. brand owners relocate packaging operations closer to end markets.

Europe

Country Key Metric Key Driver
Germany 27.8% share of region Packaging machinery OEM cluster
UK USD 0.27 Billion Post-Brexit labor constraints
France 10.9% CAGR Dairy, cosmetics, and wine packaging
Italy 11.3% share of region Packaging Valley machine builders
Spain USD 0.12 Billion Food and beverage export growth
Nordic Countries 12.4% CAGR High wages and sustainability leadership
Russia 4.2% share of region Import substitution in food processing
Rest of Europe USD 0.29 Billion Central European contract manufacturing

Germany and Italy host the world's densest concentration of packaging machinery builders, and VDMA data show automation suppliers expanding exports of integrated lines [23]. The EU Machinery Regulation (EU) 2023/1230, applicable from January 2027, updates conformity rules for robotic cells [7], while the PPWR drives format changes across food and personal care lines. The UK and Nordic markets show strong per-capita adoption because of high labor costs.

Asia-Pacific

Country Key Metric Key Driver
China 44.6% share of region National robot-density targets and domestic OEMs
India 15.8% CAGR PLI-backed food processing investment
Japan USD 0.62 Billion Aging workforce and robot OEM base
South Korea 9.1% share of region Highest robot density globally
ASEAN 14.7% CAGR Electronics and food export manufacturing
Rest of Asia-Pacific USD 0.21 Billion Australian food and beverage automation

China installed roughly 295,000 industrial robots in 2024, more than half the global total [2], and its robot industry plan aims to double manufacturing robot density . Domestic brands are gaining share with lower-cost articulated and SCARA models. Japan's government robot strategy supports adoption in food and logistics , while South Korea leads the world at 1,012 robots per 10,000 manufacturing employees [1].

South America

Country Key Metric Key Driver
Brazil 58.3% share of region Protein and beverage processing
Argentina 12.1% CAGR Agri-food export modernization
Rest of South America USD 0.09 Billion Chilean and Colombian food exporters

Brazil anchors regional demand through its meat, poultry, and beverage sectors, where export customers increasingly audit hygiene and traceability. The Brazilian Packaging Association tracks steady growth in packaging output that supports line upgrades [24]. Currency volatility and import duties raise robot prices, so many buyers prefer leased or refurbished equipment and local integrators.

Middle East & Africa

Country Key Metric Key Driver
Saudi Arabia 19.4% CAGR National Industrial Strategy and food security
UAE 23.6% share of region Logistics hubs and e-commerce fulfillment
South Africa USD 0.07 Billion Beverage and FMCG manufacturing
Egypt 16.8% CAGR Food processing export capacity
Rest of MEA 21.5% share of region Gulf dairy and packaged water plants

Saudi Arabia's industrial strategy and food-security priorities are funding new dairy, poultry, and bottled-water plants built with automated lines . The UAE's free-zone logistics hubs are adopting robotic order packing to serve regional e-commerce. Growth starts from a small base, and vendors that establish local service centers are best placed to capture greenfield projects.

Packaging Robots Market By Region, 2025-2035

Packaging Robots Market Segmentation

By Robot Type

Segment Key Metric Primary Demand Driver
Articulated Robots 39.4% share Six-axis versatility across packing and stacking
SCARA Robots USD 0.94 Billion Precise top-loading at moderate speed
Delta Robots 12.1% CAGR High-speed picking of light products
Cartesian/Gantry Robots 10.6% share Heavy payloads and large work envelopes
Collaborative Robots 14.3% CAGR Cage-free deployment and easy programming
Others USD 0.31 Billion Niche and specialty handling tasks

Within the Packaging Robots Market, Articulated Robots lead because one platform covers bottle loading, case packing, and pallet stacking. Collaborative Robots grow fastest as drag-and-drop programming and built-in force sensing allow them to share space with operators. SCARA Robots retain a role in precise top-loading, Delta Robots dominate confectionery and bakery flow-wrap feeding, and Cartesian/Gantry Robots serve heavy, large-format loads.

By Gripper Type

Segment Key Metric Primary Demand Driver
Clamp 35.0% share Rigid cartons, cases, and cans
Claw 13.3% CAGR Irregular and mixed e-commerce items
Vacuum USD 2.20 Billion Flat surfaces, bags, and lightweight products
Others 9.4% share Magnetic, needle, and hybrid end effectors

Gripper choice in the Packaging Robots Market follows package format. Clamp designs lead because rigid cartons and cans dominate consumer goods lines, and soft-touch silicone pads now protect thin-wall recyclable containers. Claw grippers grow fastest by grasping irregular items common in online orders. Vacuum tooling remains essential for bags and flat products, while hybrid end effectors cut tool changes on mixed lines.

By Application

Segment Key Metric Primary Demand Driver
Packing 42.4% share Primary to tertiary containment automation
Pick and Place 14.3% CAGR Omnichannel order assembly
Palletizing USD 1.92 Billion Heavy, repetitive end-of-line loads
Others 8.1% share Labeling, inspection, and depalletizing

Packing is the largest application in the Packaging Robots Market, spanning continuous-motion top-load cartoning and wrap-around case erecting that favor multi-axis arms. Pick and Place grows fastest as retailers automate order assembly and AI learning lets one robot alternate between boxed electronics and bagged apparel. Palletizing remains a high-value application where payload and cycle-time demands exceed safe human capacity.

By End-User Industry

Segment Key Metric Primary Demand Driver
Food 41.1% share Hygiene rules and high throughput
Beverage USD 1.34 Billion Repetitive crate and case loading
Pharmaceutical 12.8% CAGR Serialization and aseptic handling
Personal Care and Cosmetics 6.3% share SKU proliferation and premium formats
Electronics and Semiconductor 11.9% CAGR Precision handling and ESD control
E-commerce 17.6% CAGR SKU diversity and one-piece flow
Others USD 0.39 Billion Chemicals, tobacco, and household goods

Food processors are the largest buyers in the Packaging Robots Market, using washdown stainless robots for tray sealing, case packing, and lot-code logging under traceability rules . E-commerce grows fastest as parcel hubs automate single-item packing across vast SKU ranges. Pharmaceutical firms invest to meet serialization requirements , while beverage bottlers automate crate loading where payload and cycle time exceed human limits.

Competitive Benchmarking

The Packaging Robots Market is moderately concentrated, with an estimated Herfindahl-Hirschman Index of 1,100–1,300 and the top five suppliers holding roughly 45% of revenue. Japanese and European robot OEMs dominate arm supply, while packaging machinery builders and system integrators capture much of the project value through tooling, software, and line integration. Chinese manufacturers are gaining share in price-sensitive Asian markets.

Company Est. Revenue Share Range Key Offerings for Packaging Robots Market Strategic Positioning
FANUC Corporation ~10–13% Delta, articulated, and CRX collaborative robots Largest installed base; high reliability and global service
ABB Ltd ~9–12% IRB articulated and FlexPicker delta robots, palletizing software Software-led solutions; robotics division moving to SoftBank
KUKA AG ~7–10% KR QUANTEC and KR AGILUS robots, hygienic variants Strong in European food lines; backed by Midea Group
Yaskawa Electric Corporation ~7–10% Motoman palletizing and picking robots Broad payload range; expanding U.S. production
Universal Robots (Teradyne) ~3–6% UR series collaborative robots, UR30 for palletizing Cobot leader with large accessory ecosystem
Kawasaki Heavy Industries ~3–5% Heavy-payload palletizing robots Strength in high-payload end-of-line tasks
Mitsubishi Electric Corporation ~2–4% MELFA SCARA and articulated robots Integrated PLC, drive, and robot control
Stäubli International AG ~2–4% HE hygienic and stericlean robots Leader in washdown food and pharma cells
Krones AG ~2–4% Robotic palletizers and line systems for beverages Turnkey beverage line integration
Gerhard Schubert GmbH ~1–3% Robot-based top-loading packaging machines Modular, highly flexible packaging lines

Recent News & Developments

  • Universal Robots (June 2023): Launched the UR30 collaborative robot with a 30 kg payload, extending cobots into heavier palletizing duties previously reserved for industrial arms [17]
  • European Union (June 2023): Published Machinery Regulation (EU) 2023/1230, which applies from January 2027 and updates conformity requirements for robotic packaging cells [7]
  • ABB (January 2024): Acquired Sevensense, adding AI-based navigation that strengthens mobile manipulation for order fulfillment
  • U.S. FDA (November 2024): Concluded the DSCSA stabilization period for enhanced drug distribution security, sustaining pharmaceutical demand for automated serialization and aggregation
  • European Union (February 2025): The Packaging and Packaging Waste Regulation (EU) 2025/40 entered into force, triggering line redesigns for recyclable formats [6]
  • ISO (2025): Published revised ISO 10218-1 and ISO 10218-2, integrating collaborative application requirements and simplifying cobot risk assessments [9]
  • SoftBank Group (October 2025): Agreed to acquire ABB's robotics division for about USD 5.4 billion, reshaping the competitive landscape among top suppliers

Packaging Robots Market Report Scope

Parameter Details
Market Scope Robots, grippers, and integrated robotic cells used for packing, pick and place, palletizing, and related packaging tasks across food, beverage, pharmaceutical, personal care, electronics, e-commerce, and other end uses.
Study Period 2021–2035
Base Year 2025
Historical Data 2021–2024
Forecast Period 2026–2035
Market Size in 2025 USD 7.85 Billion
Market Size in 2035 USD 22.70 Billion
CAGR (2026–2035) 11.2%
Fastest Growing Segments E-commerce (17.6% CAGR); Collaborative Robots (14.3% CAGR); Pick and Place (14.3% CAGR); Claw (13.3% CAGR)
Regions Covered North America, Europe, South America, Asia Pacific, Middle East and Africa and ROW
Companies Profiled FANUC Corporation, ABB Ltd, KUKA AG, Yaskawa Electric Corporation, Universal Robots (Teradyne), Kawasaki Heavy Industries, Mitsubishi Electric Corporation, Stäubli International AG, Krones AG, Gerhard Schubert GmbH
Valuation Currency USD Billion
Methodology 350+ primary expert interviews; bottom-up market sizing; top-down validation; data triangulation; scenario-based forecasting; real-time project tracking

FAQs

What payback period do buyers typically see on projects in the Packaging Robots Market?
Across the Packaging Robots Market, two-shift case-packing and palletizing cells usually recover their cost in 18 to 36 months. Single-shift lines with frequent changeovers often take longer than four years, so operating hours matter more than robot list price.
Which ingress protection rating matters for washdown food applications?
Raw meat, poultry, and dairy lines generally specify IP67 arms with IP69K-rated wrists and food-grade H1 lubricants. These ratings let robots withstand high-pressure, high-temperature sanitation without seal failure.
How do pharmaceutical buyers validate robots before production use?
Validation follows GAMP 5 risk-based guidance, with installation, operational, and performance qualification documented for each cell. Suppliers offering pre-written qualification packages can shorten commissioning by several weeks.
How does PackML simplify robot integration in the Packaging Robots Market?
PackML, defined in ISA-TR88.00.02, standardizes machine states and tags so robots, fillers, and labelers share one control language. Within the Packaging Robots Market, lines built on PackML and OPC UA integrate faster and report comparable OEE data across vendors.
When should a buyer choose a delta robot over a SCARA robot?
Delta robots suit light products under roughly 3 kg moving at 150-plus picks per minute from a conveyor. SCARA robots offer better rigidity and reach for precise top-loading into fixed cartons at moderate speeds.
Are refurbished robots a viable entry point into the Packaging Robots Market?
Refurbished six-axis arms can cost 40–60% less than new units and suit simple palletizing duties. Buyers in the Packaging Robots Market should confirm spare-parts availability and controller software support, because obsolete controllers raise long-term maintenance risk.
What safety documentation is required before commissioning a robotic cell?
Integrators must complete a risk assessment under ISO 12100, apply ISO 10218-2 cell requirements, and issue CE conformity documentation for EU sites. Collaborative applications also require force and pressure verification against ISO/TS 15066 biomechanical limits.
Author
Author Author Profile Aarti Dhapte LinkedIn AVP - Research
A consulting professional focused on helping businesses navigate complex markets through structured research and strategic insights. I partner with clients to solve high-impact business problems across market entry strategy, competitive intelligence, and opportunity assessment. Over the course of my experience, I have led and contributed to 100+ market research and consulting engagements, delivering insights across multiple industries and geographies, and supporting strategic decisions linked to $500M+ market opportunities. My core expertise lies in building robust market sizing, forecasting, and commercial models (top-down and bottom-up), alongside deep-dive competitive and industry analysis. I have played a key role in shaping go-to-market strategies, investment cases, and growth roadmaps, enabling clients to make confident, data-backed decisions in dynamic markets.
Co-Author Co-Author Profile Aarti Dhapte LinkedIn AVP - Research
A consulting professional focused on helping businesses navigate complex markets through structured research and strategic insights. I partner with clients to solve high-impact business problems across market entry strategy, competitive intelligence, and opportunity assessment. Over the course of my experience, I have led and contributed to 100+ market research and consulting engagements, delivering insights across multiple industries and geographies, and supporting strategic decisions linked to $500M+ market opportunities. My core expertise lies in building robust market sizing, forecasting, and commercial models (top-down and bottom-up), alongside deep-dive competitive and industry analysis. I have played a key role in shaping go-to-market strategies, investment cases, and growth roadmaps, enabling clients to make confident, data-backed decisions in dynamic markets.

Research Approach


Secondary Research

The secondary research process involved comprehensive analysis of regulatory databases, industry publications, robotics technology journals, automation whitepapers, and authoritative industrial organizations. Key sources included the International Federation of Robotics (IFR), International Organization for Standardization (ISO) Technical Committee 299 (Robotics), Robotic Industries Association (RIA - Association for Advancing Automation), European Robotics Association (EUnited Robotics), Japan Robot Association (JARA), Korea Association of Robot Industry (KAR), Occupational Safety and Health Administration (OSHA) Robotics Safety Standards, National Institute of Standards and Technology (NIST) Manufacturing Robotics Program, European Committee for Standardization (CEN) Technical Committee 310, Food and Drug Administration (FDA) 21 CFR Part 11 (for pharmaceutical packaging compliance), European Medicines Agency (EMA) Good Manufacturing Practice (GMP) guidelines, International Electrotechnical Commission (IEC) 61508 (Functional Safety), IEEE Robotics & Automation Society publications, National Bureau of Statistics of China (Industrial Robot Production Data), U.S. Bureau of Labor Statistics (Manufacturing Employment Trends), EU Eurostat Industrial Production Database, World Economic Forum (WEF) Future of Jobs Report, MRFR Global Institute Automation Reports, and national industrial robotics associations from Germany (VDMA), France (Syrobo), and Italy (SIRI). These sources were used to collect installation statistics, regulatory compliance frameworks, safety standard certifications, technology adoption trends, and market landscape analysis for articulated robots, Cartesian robots, SCARA robots, delta robots, collaborative robots, and other packaging automation technologies across food and beverages, pharmaceuticals, electronics, automotive, and cosmetics sectors.


Primary Research

In order to gather both qualitative and quantitative insights, supply-side and demand-side stakeholders were interviewed during the primary research process. CEOs, VPs of Engineering, Chief Technology Officers, product line directors, and regional sales leaders from automation component suppliers, system integrators, and packaging robot manufacturers were examples of supply-side sources. Plant managers, packaging operations directors, automation engineers, procurement leads from food and beverage processing facilities, pharmaceutical manufacturing facilities, electronics assembly units, suppliers of automotive components, and cosmetics packaging facilities were among the demand-side sources. In addition to confirming product development roadmaps and gathering information on adoption barriers, integration challenges, total cost of ownership models, and return on investment timelines, primary research verified market segmentation by robot type (articulated, Cartesian, SCARA, delta, collaborative), payload capacity categories (below 10 kg, 10-50 kg, 50-150 kg, 150-500 kg, and above 500 kg), and functionality applications (picking and placing, palletizing and depalletizing, labeling, and quality control).

Primary Respondent Breakdown:

By Designation: C-level Primaries (28%), Director Level (32%), Others (40%)

By Region: North America (32%), Europe (30%), Asia-Pacific (33%), Rest of World (5%)


Market Size Estimation

Global market valuation was derived through revenue mapping and installation volume analysis. The methodology included:

Identification of 50+ key manufacturers and system integrators across North America, Europe, Asia-Pacific, and Latin America

Product mapping across articulated robots, Cartesian robots, SCARA robots, delta robots, collaborative robots, and specialized packaging automation systems

Analysis of reported and modeled annual revenues specific to packaging robot portfolios and automation solutions

Coverage of manufacturers representing 75-80% of global market share in 2024

Extrapolation using bottom-up (installation volume × ASP by country and payload category) and top-down (manufacturer revenue validation) approaches to derive segment-specific valuations for food and beverages, pharmaceuticals, electronics, automotive, and cosmetics applications

Download Free Sample

Kindly complete the form below to receive a free sample of this Report

Download PDF ×

We do not share your information with anyone. However, we may send you emails based on your report interest from time to time. You may contact us at any time to opt-out.


















